

“The way to build long-term returns is through preservation of capital and home runs.”
Stanley Druckenmiller
EQUITY MARKETS – INDICES
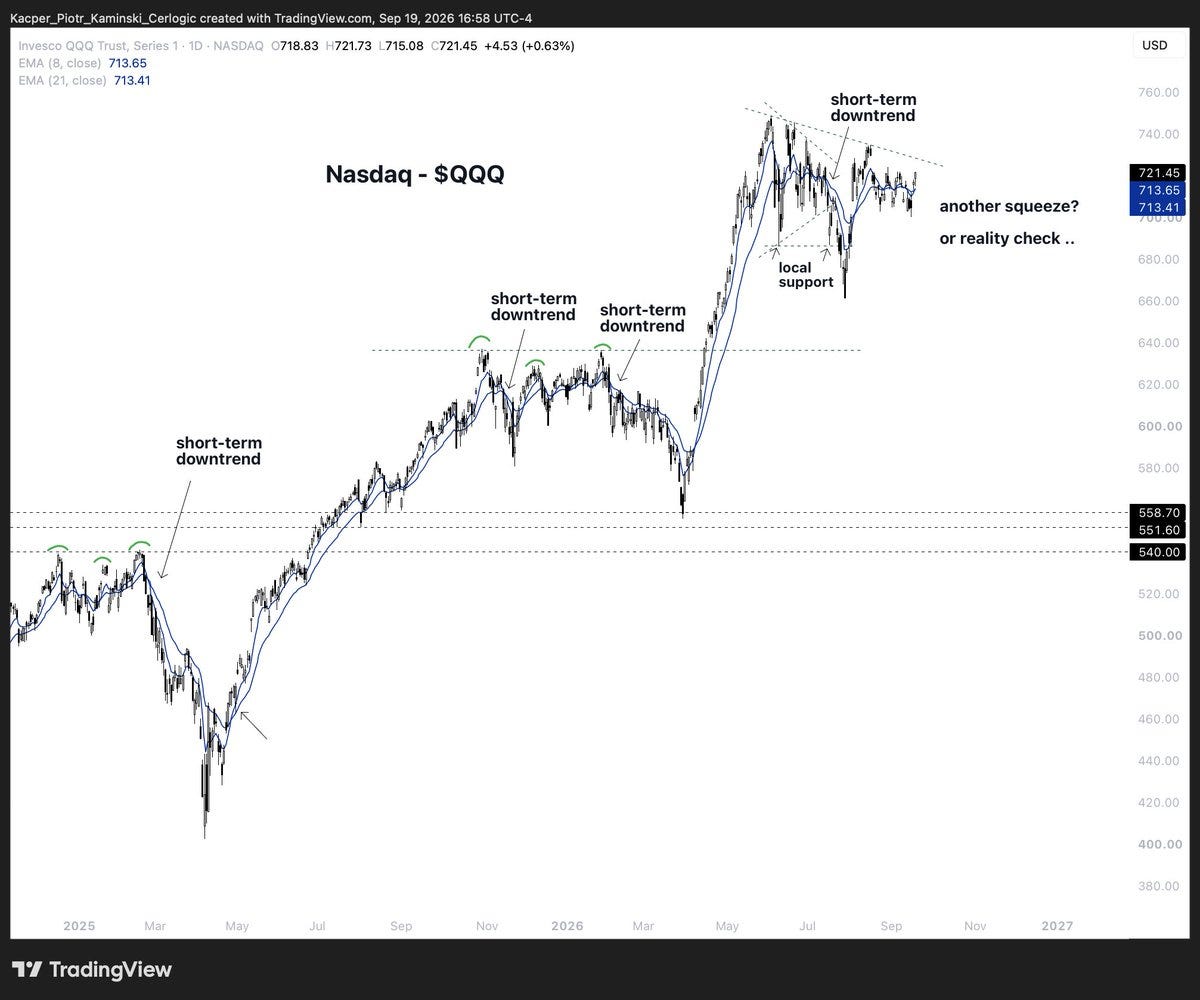
OpEx week is behind us. As we suspected, the indices stayed pinned. No magic here, that’s just how the fewest market participants get paid. This matters more and more, because options move the tape now, at least in the short term.
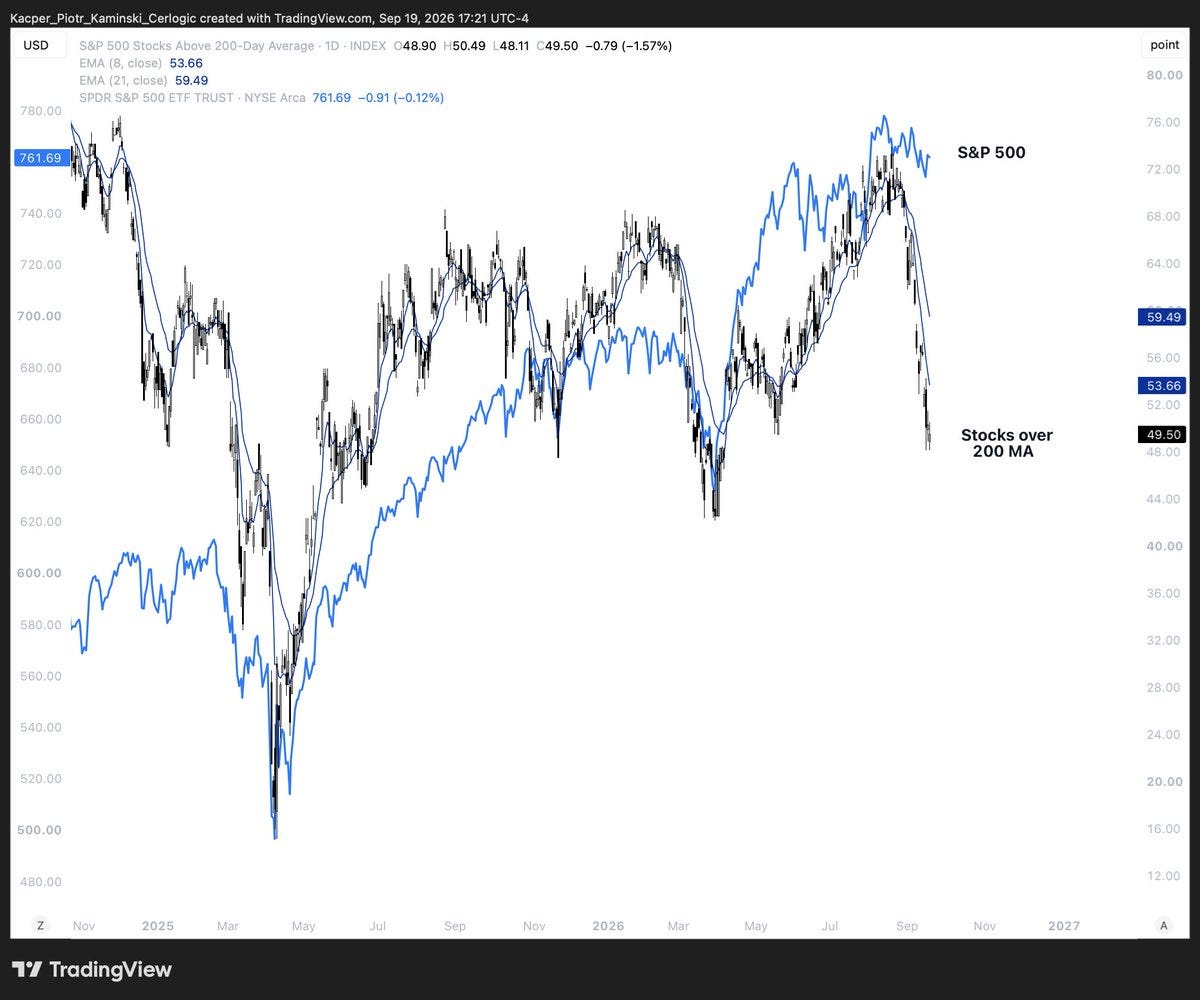
Beneath the surface of the indices it’s just super ugly. More than half the stocks have are trading below their 200-day. And so, here we are again, at a pivot, with two paths forward.
First path is the obvious reality check on the AI trade. And let’s be honest, almost everything is correlated to it right now. It cannot slow down. Growth and dreams are the whole story, because it certainly isn’t the financials. So we’ll treat the chat around it as “marketing” at best. Any advanced technology can be dangerous when you make it that way.
Second path is the engineered squeeze. Welcome a little decline, just enough to flip as many as possible short. Managed money, CTAs, vol and trend funds. Then rug-pull them and flip it all back to the upside.
We won’t predict. We’ll just trade by joining the winning side.
Whether they can pull off a squeeze, that is the question. We still don’t assume they can manage the tape forever. It’s the government after all, our friends, no strangers to mistakes or outright failure. So we lean, as we have for weeks now, toward this being able to tip into a real period of volatility. Quarter-end is dead ahead, elections not far behind.
Otherwise things stay the same. We wish we could say otherwise.
On the government’s side the outlook doesn’t change. They’re spending like there’s no tomorrow, social transfers, defense, energy, and maybe now picking up the tab for the private sector too.
So, does the global AI race stay on, funded by an unbelievable amount of debt, or do we take a pause here ..
We don’t know how, when, or if it ends. It really depends on the money creation, and that just never seems to stop, reinforcing the K-shaped economy, globally. Cycles point to a late phase: yields climbing, equities topping, commodities doing well. This week had a bit more of the topping.
But we’ll see, and follow the trends, as always.
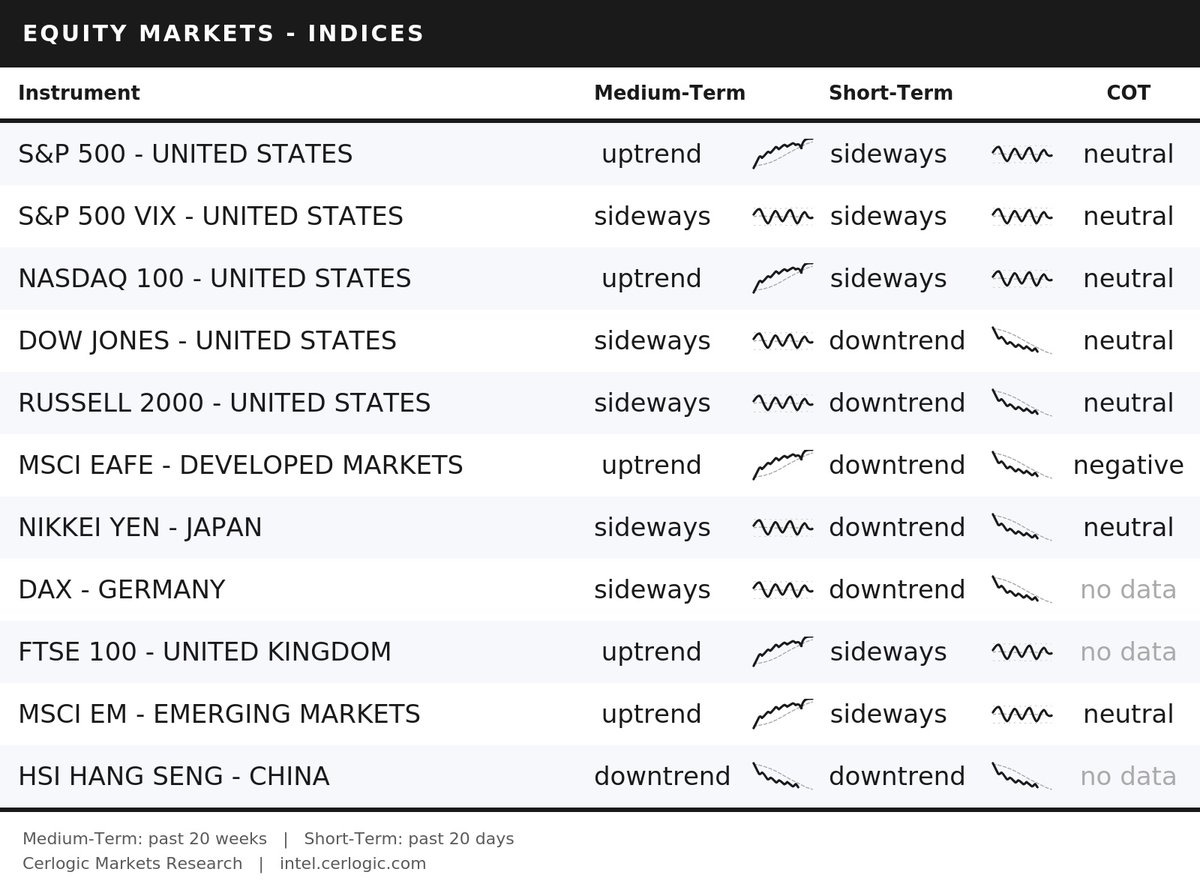
SHORT-TERM TREND CHANGES SINCE LAST WEEK
• S&P 500 VIX – UNITED STATES: downtrend ➝ sideways
• FTSE 100 – UNITED KINGDOM: downtrend ➝ sideways
• MSCI EM – EMERGING MARKETS: uptrend ➝ sideways
MEDIUM-TERM TREND CHANGES SINCE LAST WEEK
• S&P 500 VIX – UNITED STATES: downtrend ➝ sideways
• DOW JONES – UNITED STATES: uptrend ➝ sideways
• RUSSELL 2000 – UNITED STATES: uptrend ➝ sideways
• NIKKEI YEN – JAPAN: uptrend ➝ sideways
• DAX – GERMANY: uptrend ➝ sideways
• HSI HANG SENG – CHINA: sideways ➝ downtrend
COT CHANGES SINCE LAST WEEK
• NIKKEI YEN – JAPAN: negative ➝ neutral
FOREX
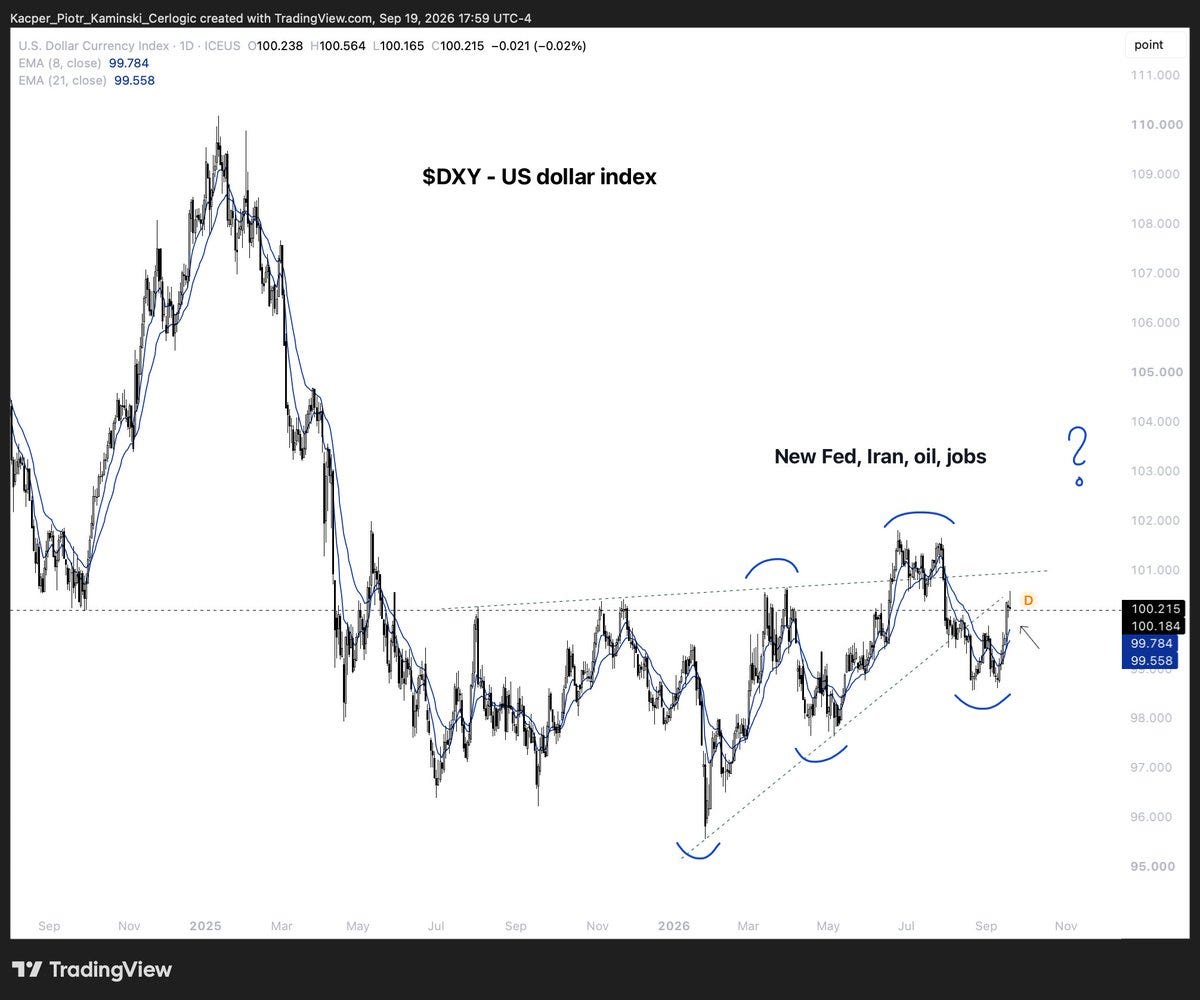
The last piece has fallen into place, the dollar. “Hawkish” Fed and more importantly, ongoing energy crisis, have made move it to the upside. re’s the piece that didn’t fit, fitting now.
The DXY index closed the week over 100 and entered short-term uptrend. And the whole bloc rolled over with it, the euro, the pound, the Loonie, the Aussie, the Peso, all giving back their gains, a proper forex risk-off week.
Is this the real turn or just the bounce we were waiting for? Too early to call it, we’ll see, one week of strength doesn’t undo all the structural problems, but hey, the competition is quite weak as well ..
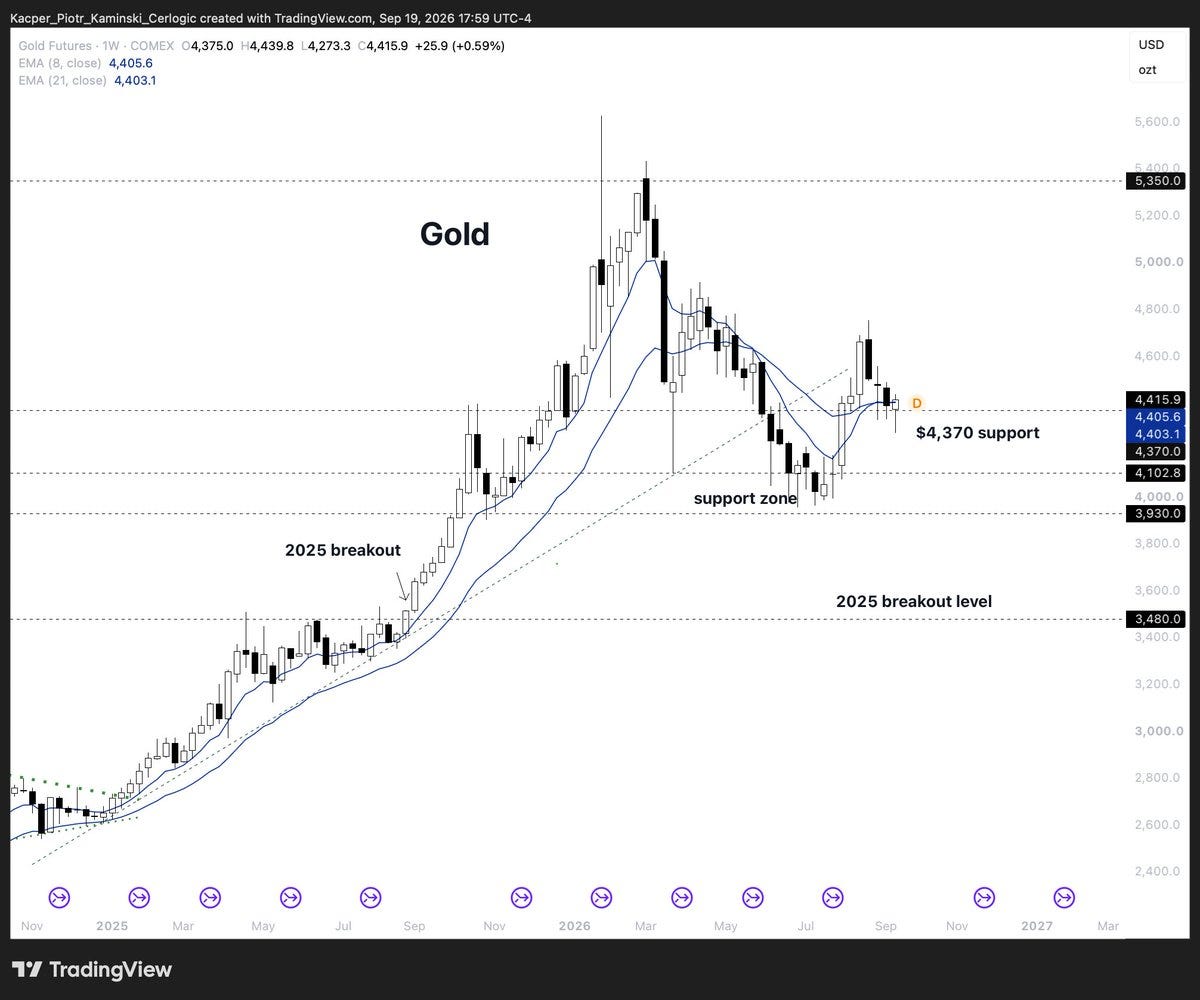
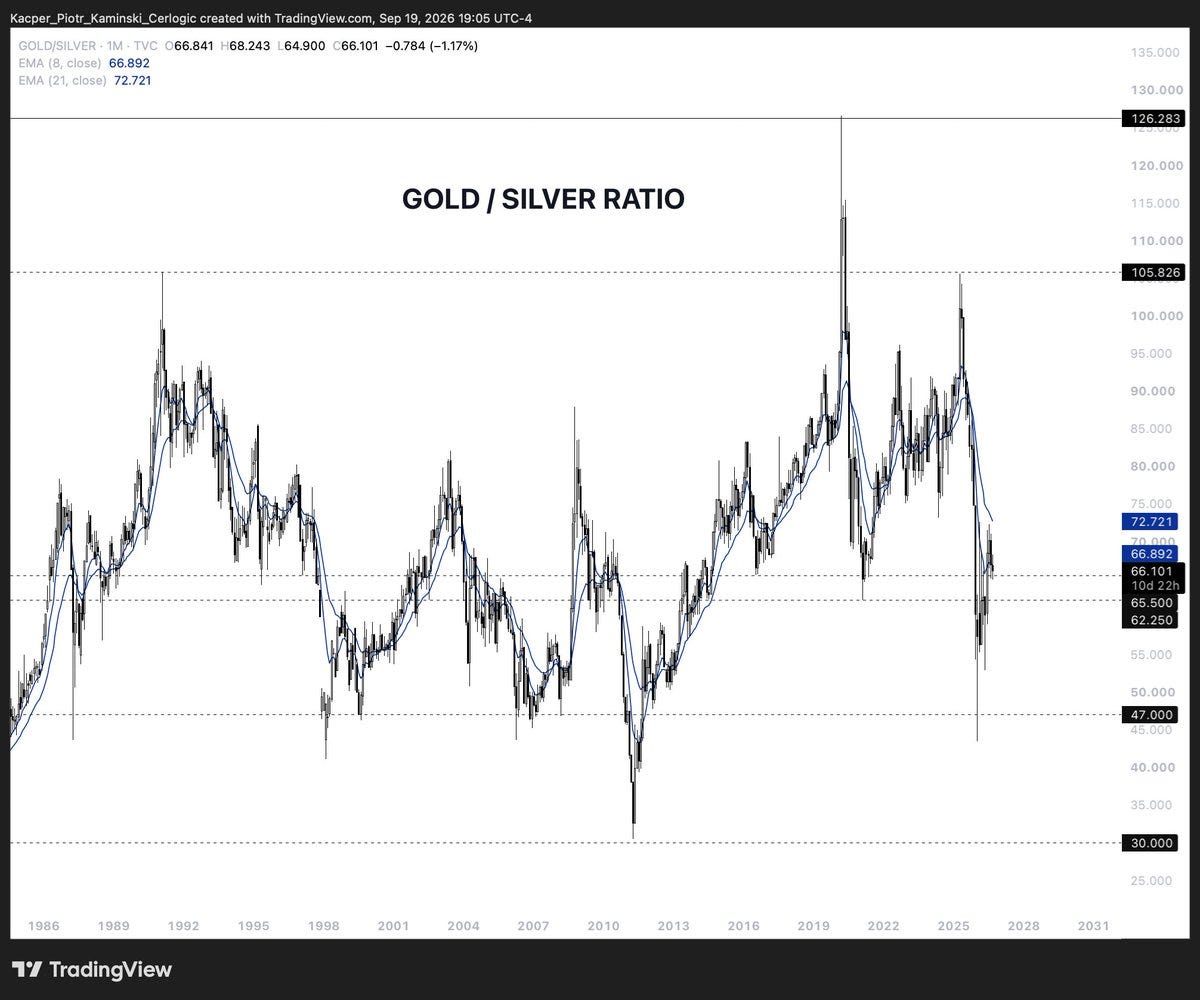
Despite true money of course, which is gold. And gold, sold off on Fed day, and got bought right back up, we may just have found a new strong support here. Overall it held sideways last week, right through the dollar’s bounce and the risk-off. That’s exactly what you want to see.
Still no FOMO out there, still the wall of worry. We’re well positioned already, so we’re just waiting and watching now, looking to trade more strategically, only as opportunities present themselves.
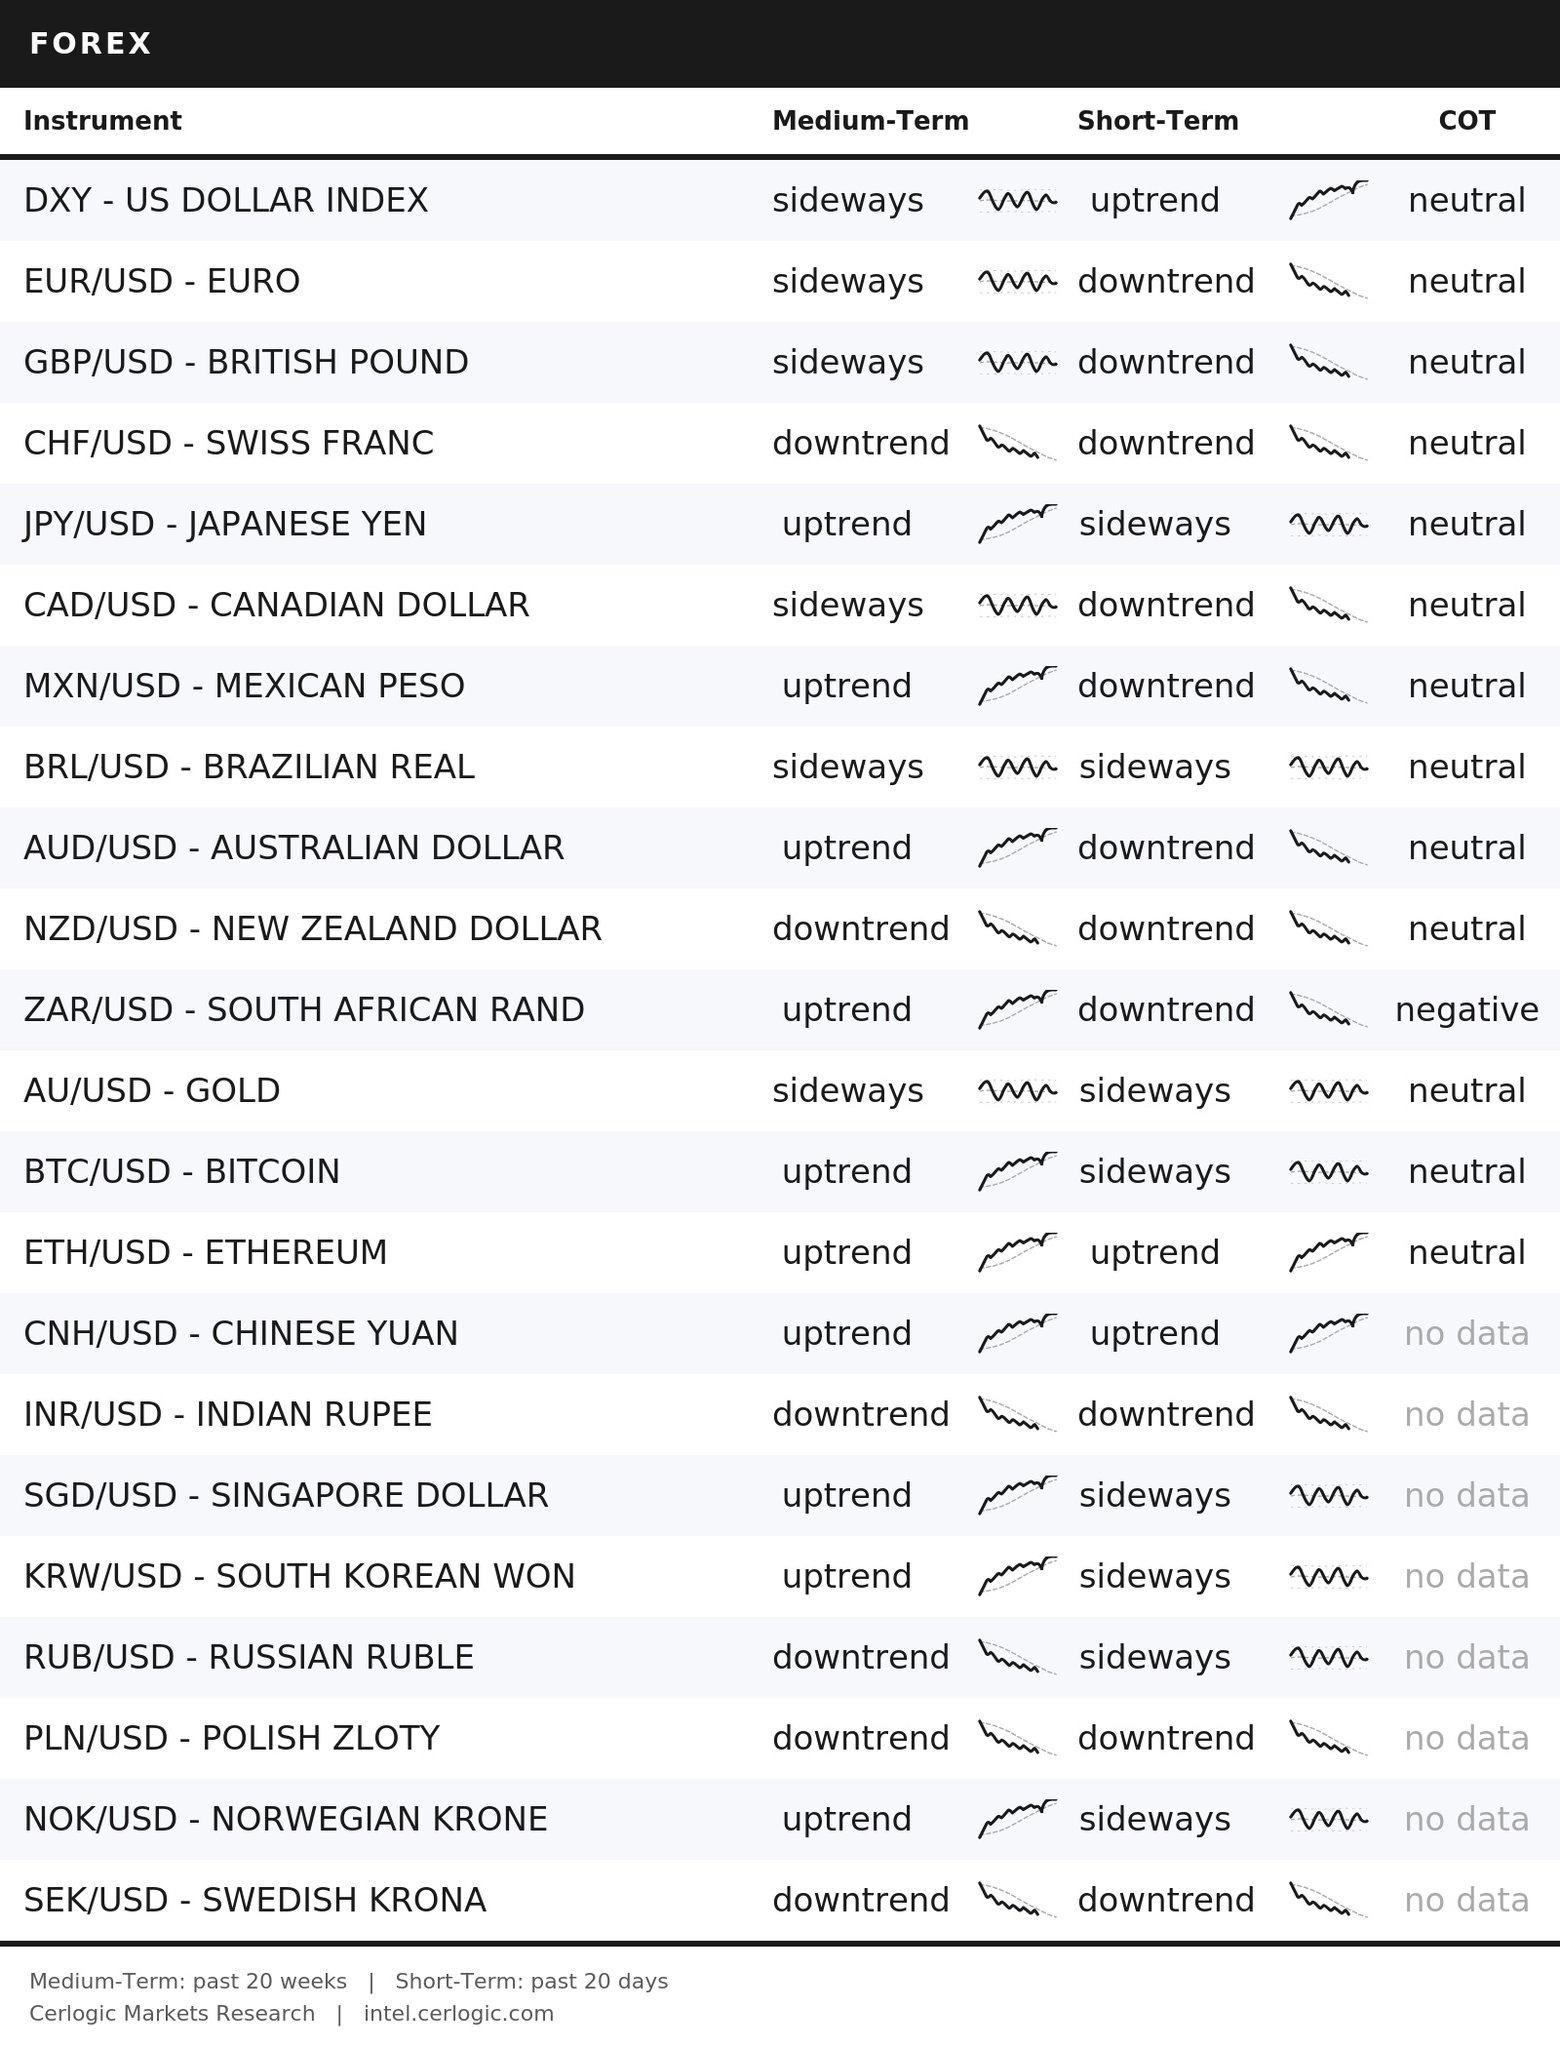
SHORT-TERM TREND CHANGES SINCE LAST WEEK
• DXY – US DOLLAR INDEX: downtrend ➝ uptrend
• EUR/USD – EURO: sideways ➝ downtrend
• GBP/USD – BRITISH POUND: sideways ➝ downtrend
• JPY/USD – JAPANESE YEN: uptrend ➝ sideways
• CAD/USD – CANADIAN DOLLAR: sideways ➝ downtrend
• MXN/USD – MEXICAN PESO: uptrend ➝ downtrend
• BRL/USD – BRAZILIAN REAL: uptrend ➝ sideways
• AUD/USD – AUSTRALIAN DOLLAR: uptrend ➝ downtrend
• ZAR/USD – SOUTH AFRICAN RAND: sideways ➝ downtrend
• INR/USD – INDIAN RUPEE: sideways ➝ downtrend
• SGD/USD – SINGAPORE DOLLAR: uptrend ➝ sideways
• KRW/USD – SOUTH KOREAN WON: uptrend ➝ sideways
• PLN/USD – POLISH ZLOTY: sideways ➝ downtrend
• NOK/USD – NORWEGIAN KRONE: uptrend ➝ sideways
MEDIUM-TERM TREND CHANGES SINCE LAST WEEK
• DXY – US DOLLAR INDEX: downtrend ➝ sideways
• EUR/USD – EURO: uptrend ➝ sideways
• GBP/USD – BRITISH POUND: uptrend ➝ sideways
• CAD/USD – CANADIAN DOLLAR: uptrend ➝ sideways
• NZD/USD – NEW ZEALAND DOLLAR: sideways ➝ downtrend
COT CHANGES SINCE LAST WEEK
• DXY – US DOLLAR INDEX: negative ➝ neutral
• ZAR/USD – SOUTH AFRICAN RAND: neutral ➝ negative
INDUSTRIAL METALS
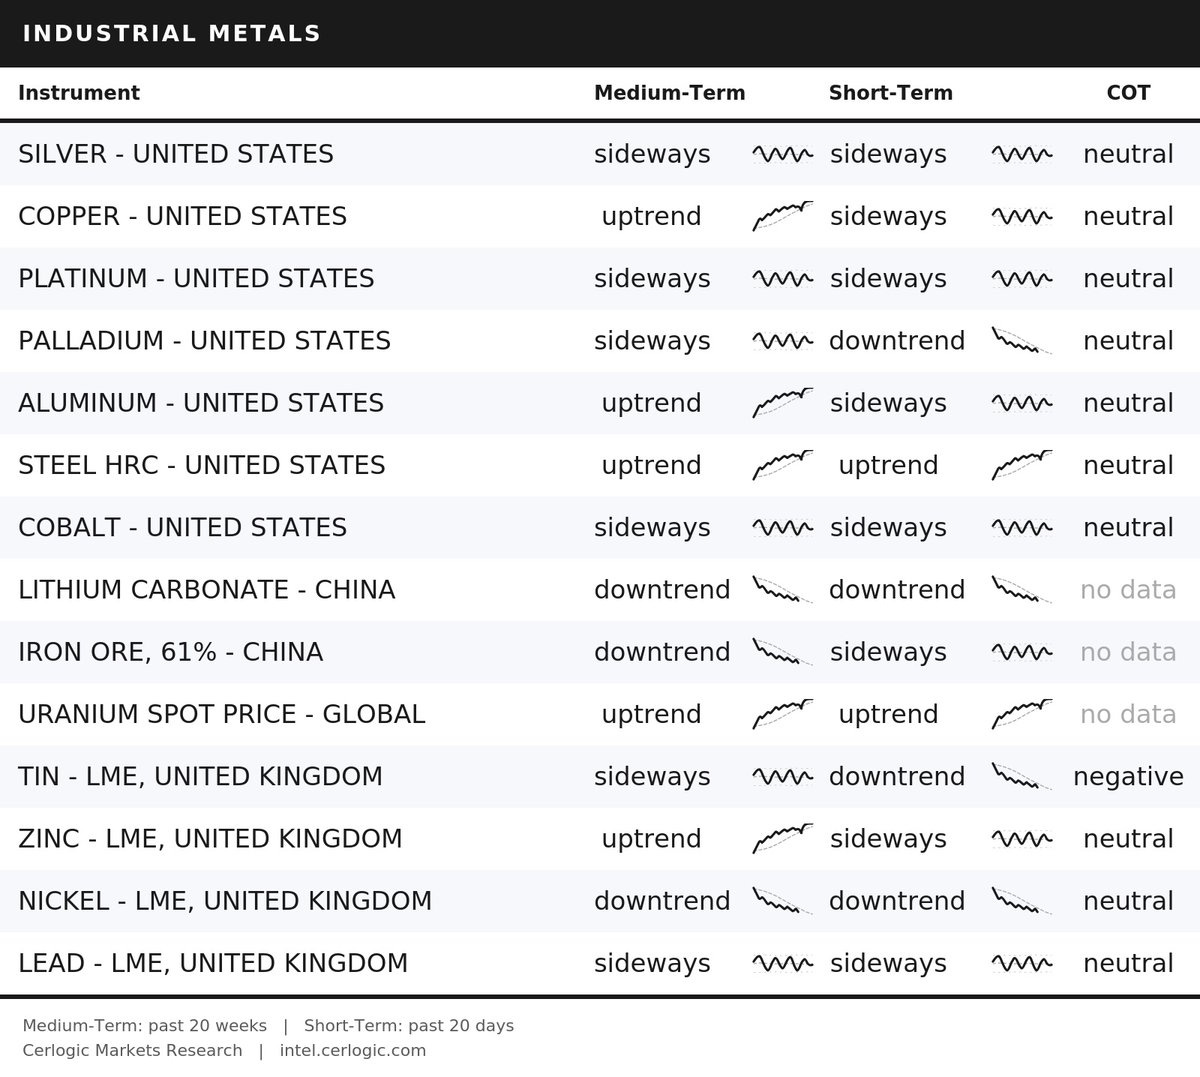
The consolidation rolls on, this week in base metals, with tin and zinc giving back some of the recent gains last week, off their short-term uptrends.
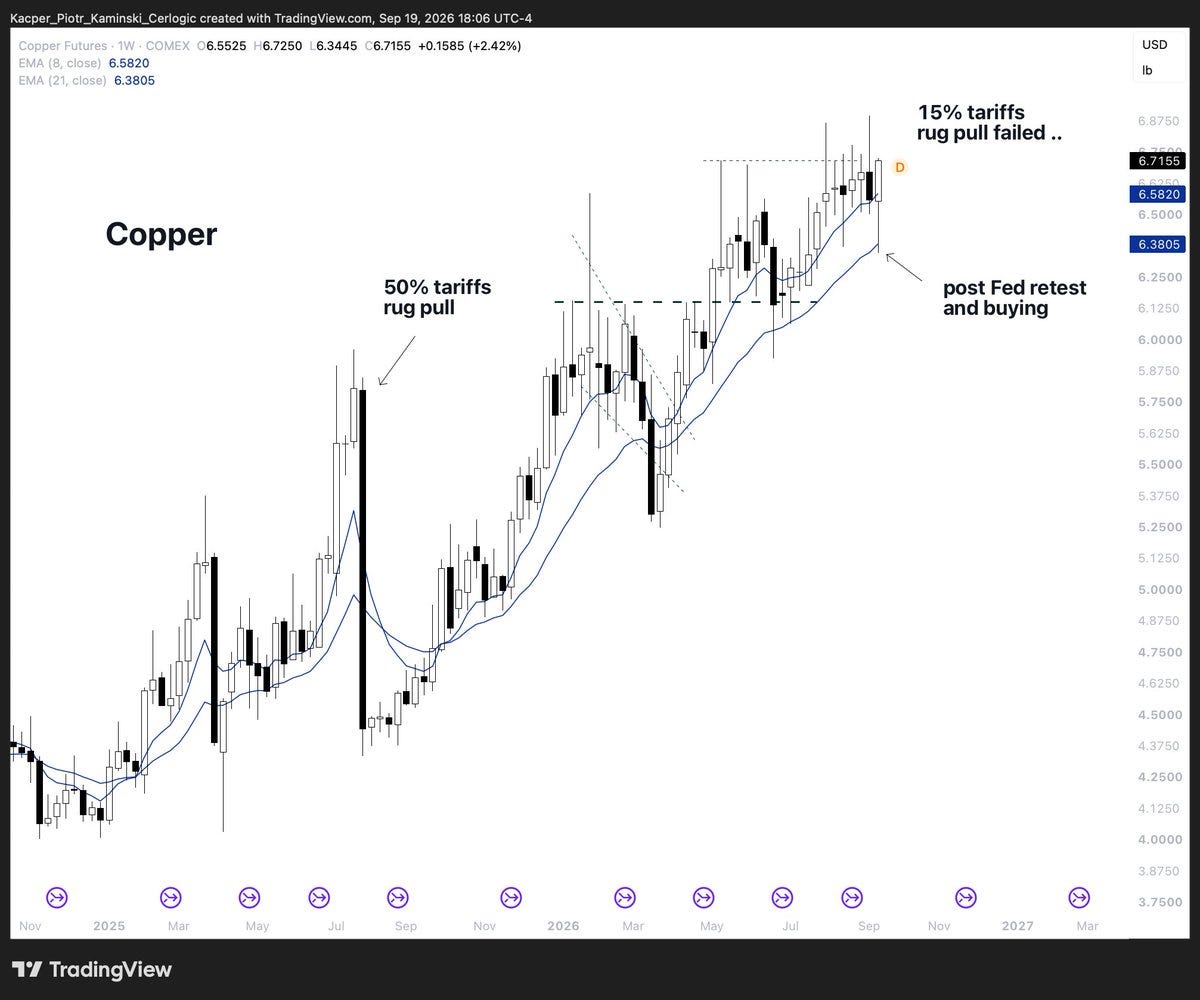
Copper sold after early 15% tariffs rug pull, and then a bit more into the Fed decision, only to be fiercely bought right back up. Back on the base case now, that is, we simply don’t have nearly enough. And with the energy prices where they are, production costs and issues could only intensify.
Physical uranium keeps its place in both uptrends, unbothered by all the chop, right on time as the seasonal strength usually kicks in. Equities are a different story, again, sold as a part of the AI trade to a large extent.
Where we go from here is still largely a political question, it’s tied to the energy crisis, same as last week, and pretty much every week since March.
Otherwise, as always, we do have our strong fundamental cases that will most probably play out, but in the short term, anything can happen. We stay flexible, keep what is working and cut what is not, early, just riding the waves.
SHORT-TERM TREND CHANGES SINCE LAST WEEK
• PALLADIUM – UNITED STATES: sideways ➝ downtrend
• TIN – LME, UNITED KINGDOM: sideways ➝ downtrend
• ZINC – LME, UNITED KINGDOM: uptrend ➝ sideways
MEDIUM-TERM TREND CHANGES SINCE LAST WEEK
• SILVER – UNITED STATES: downtrend ➝ sideways
• TIN – LME, UNITED KINGDOM: uptrend ➝ sideways
• LEAD – LME, UNITED KINGDOM: downtrend ➝ sideways
COT CHANGES SINCE LAST WEEK
• TIN – LME, UNITED KINGDOM: neutral ➝ negative
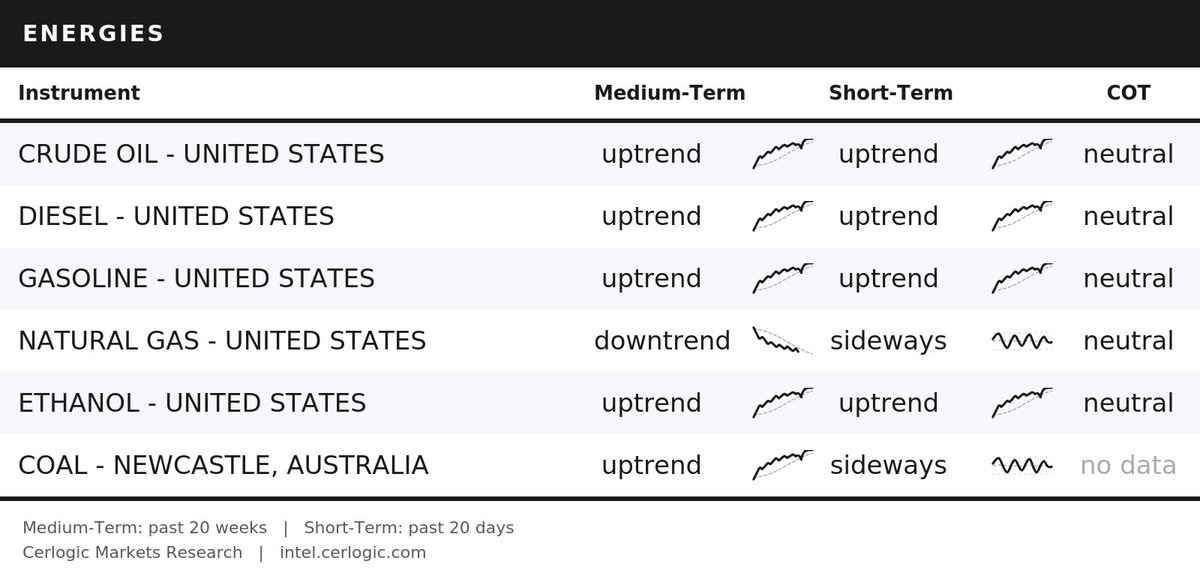
ENERGIES
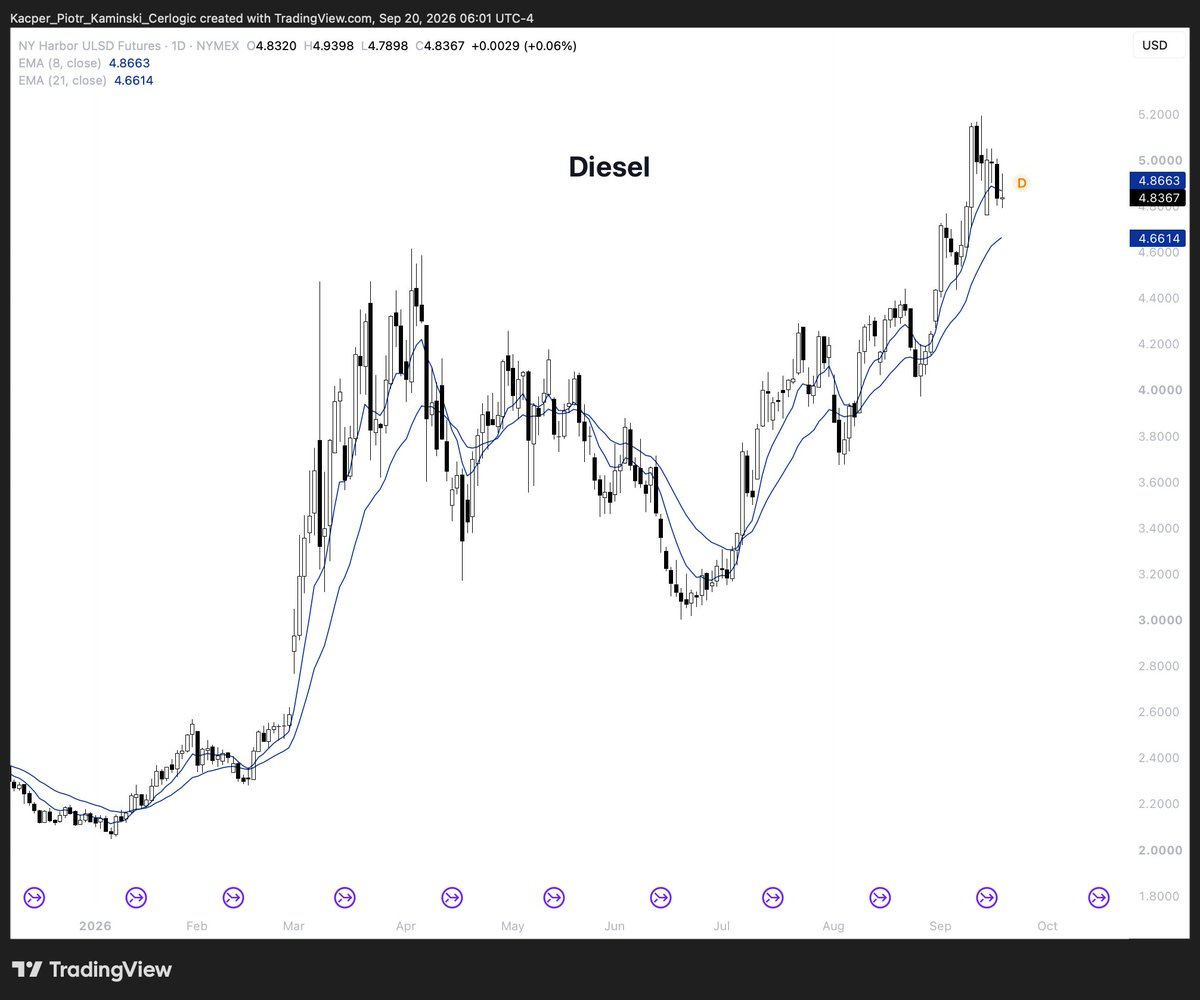
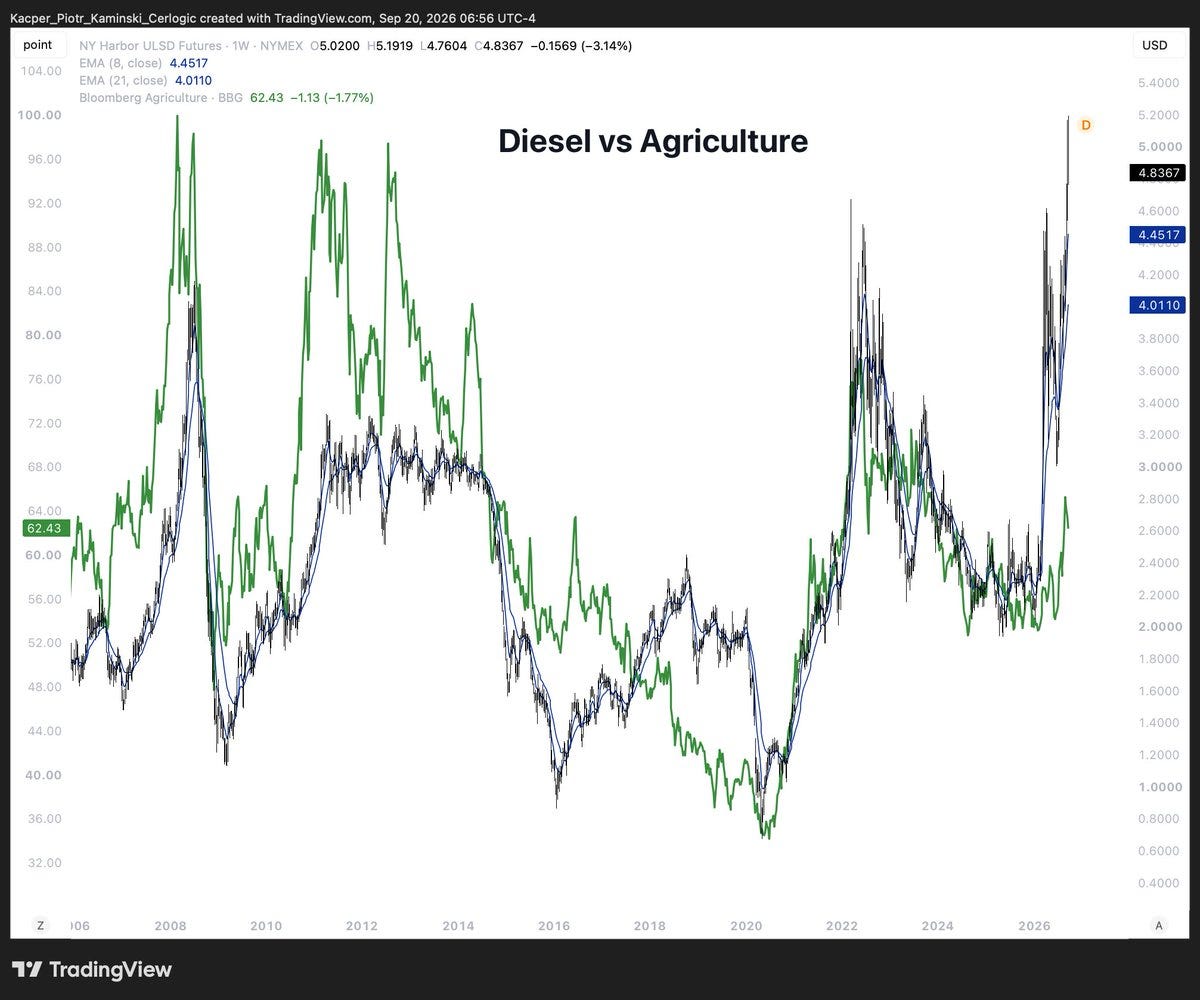
Diesel still pinned near all-time highs, Brent and WTI holding their uptrends, gasoline also way elevated. Energy crisis continues, and it hits especially strong in the developing economies.
Short-term direction remains dependent on the political decisions, same as every week since the war started. The Middle East, the Houthis and the Saudis now, still Russia, I won’t pretend to know what they’ll do next, but it doesn’t look like it’ll be over anytime soon.
What we can do is stick to facts. The damage to production capacity and the depletion of reserves is done, and it’ll be with us for years, likely extending right into what would anyway be an underinvestment crisis, the one set to bite by the end of this decade.
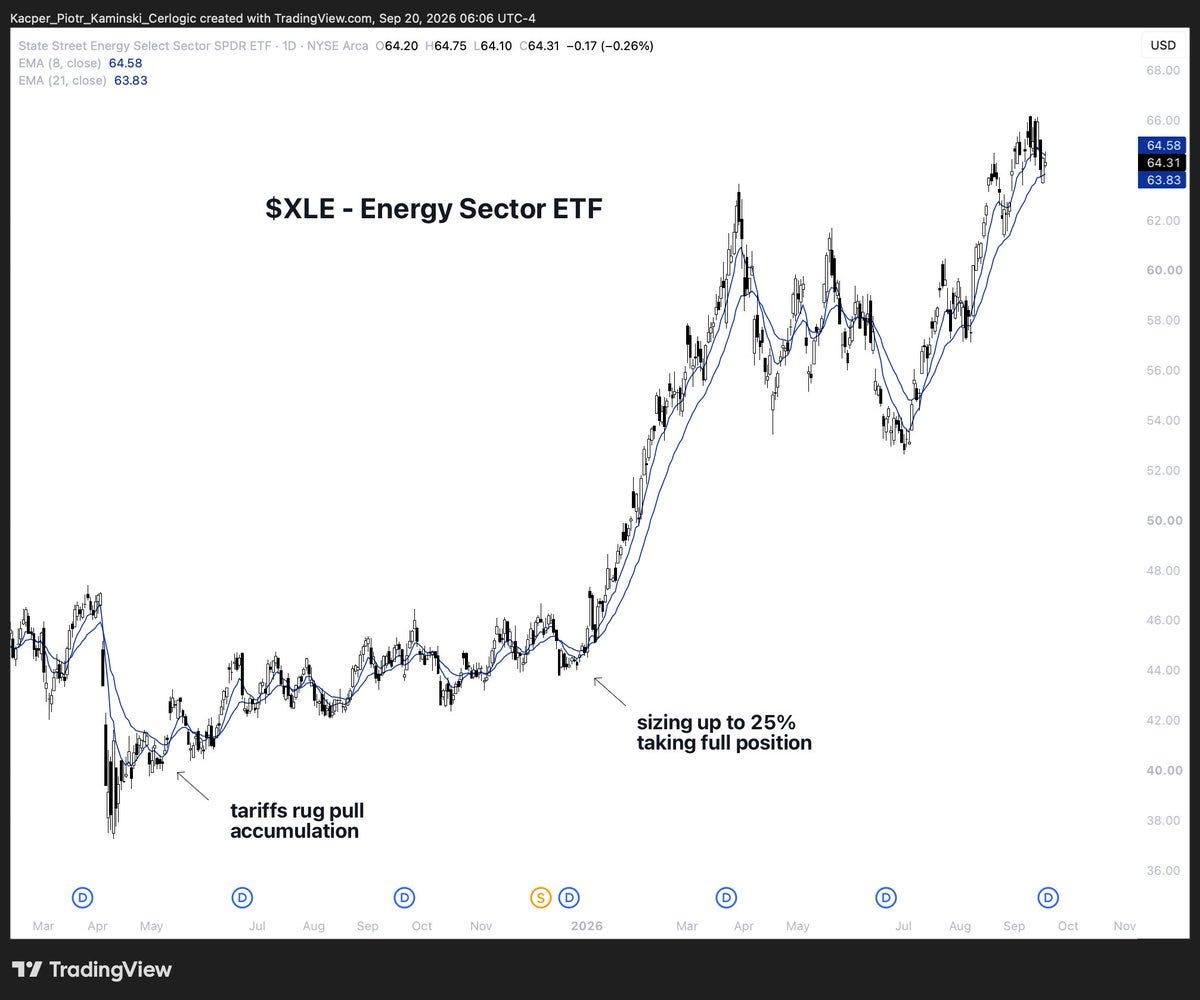
Easy money has been made, but there are a lot of opportunities here for patient and strategic investors, upstream, midstream, downstream, services, you name it, and we’re ready for it. Our core long-term energy equity positions stay on.
SHORT-TERM TREND CHANGES SINCE LAST WEEK
• COAL – NEWCASTLE, AUSTRALIA: uptrend ➝ sideways
MEDIUM-TERM TREND CHANGES SINCE LAST WEEK
• NONE
COT CHANGES SINCE LAST WEEK
• NONE
TREASURIES
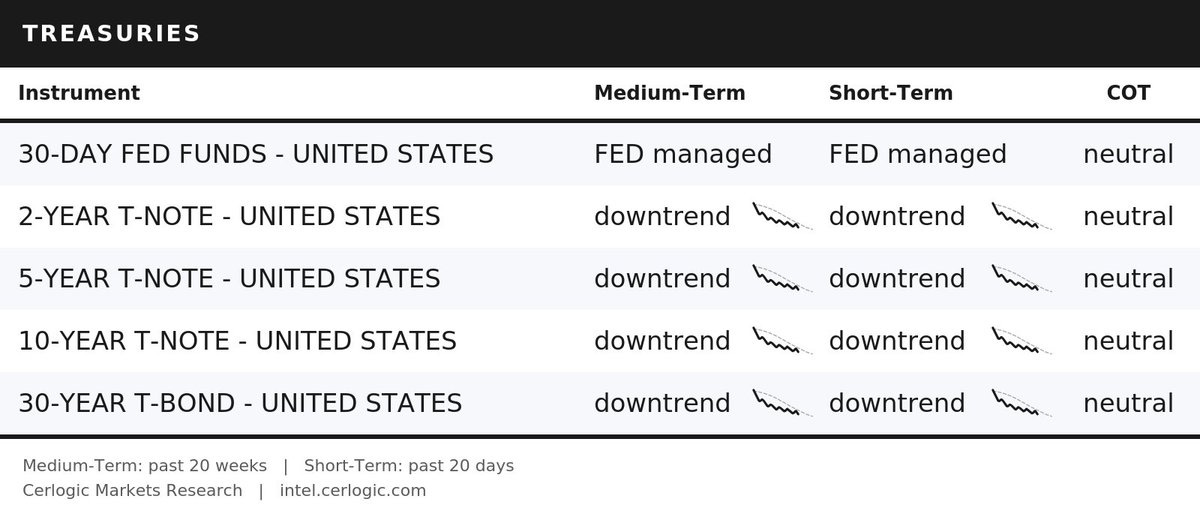
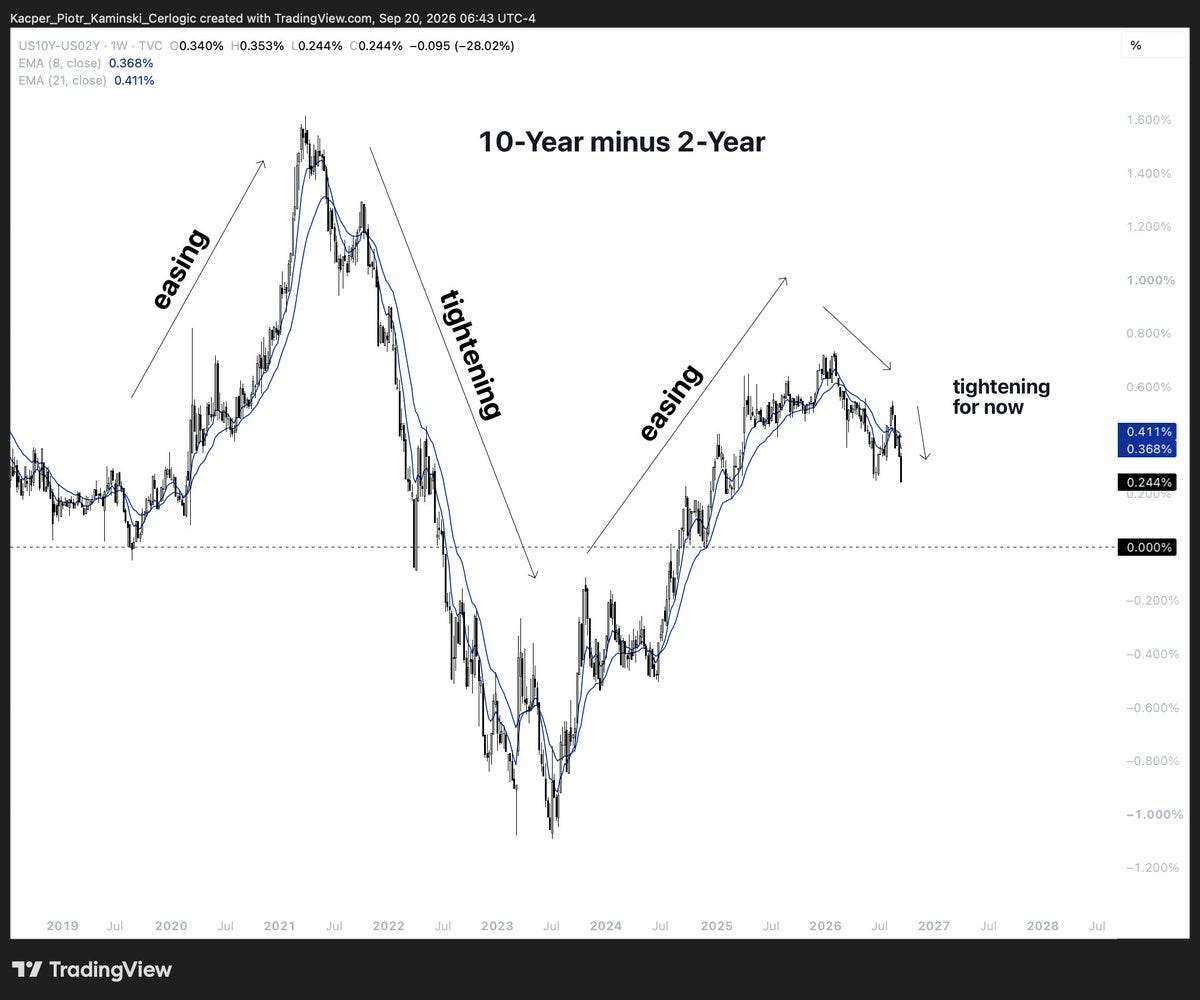
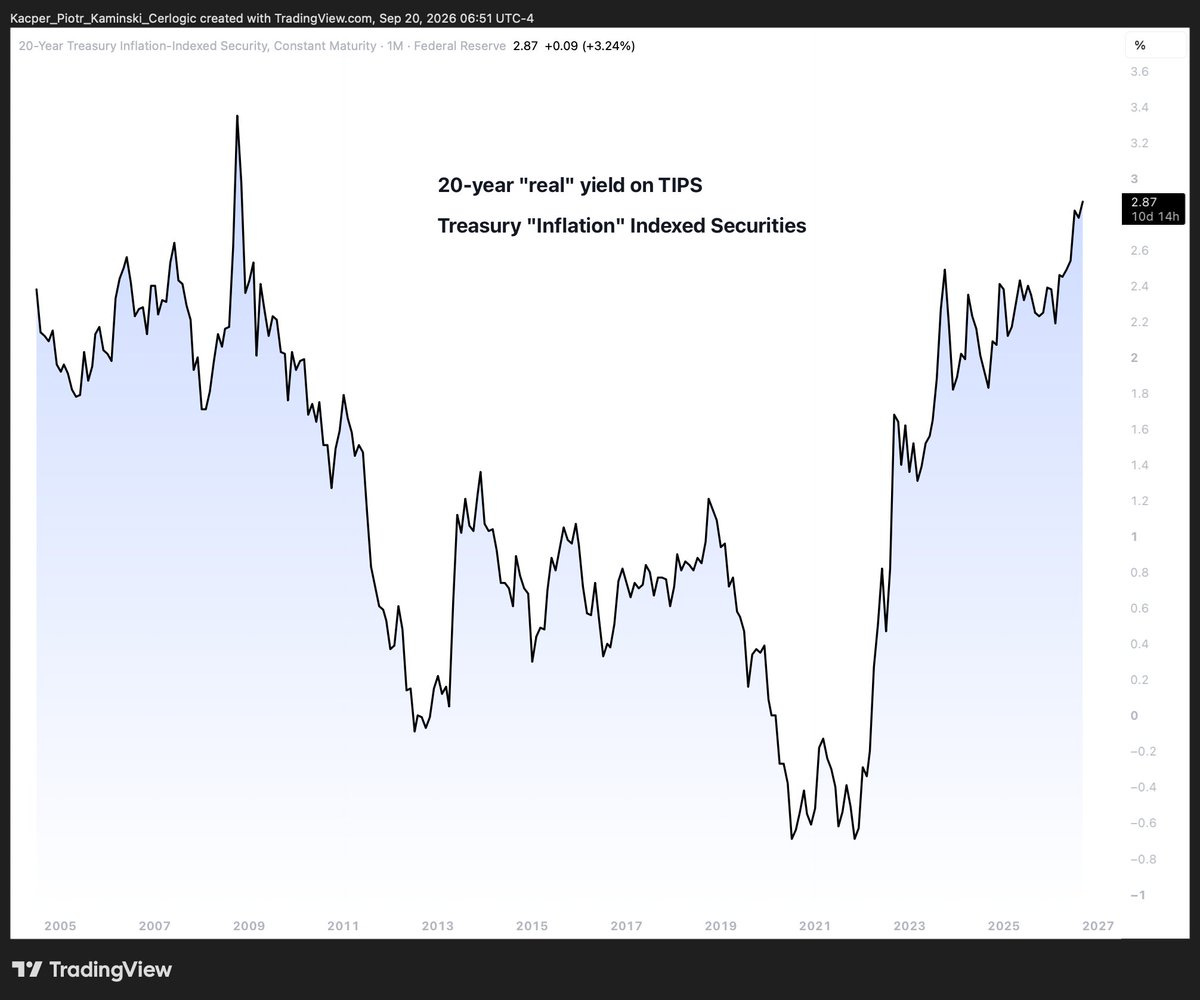
Beatings will continue until morale improves, no matter how “hawkish” the message. The Fed came and went, and nothing changed on the board, the whole curve still in a downtrend, yields parked up at the highs. Whatever they did or didn’t do with the rate, the long end couldn’t care less, which was rather the point.
I still think they’ve succeeded at removing the forward guidance for a reason, and along with it the reaction function, and that was probably the point all along. We still won’t know what data to trust, it’s produced by the government. What data they look at, up to task forces. The inflation measure, up to task forces. The balance sheet plan, you guessed it, task forces.
In any case, the long end is still heading the wrong way, and it’ll take a lot more than words, cosmetic buybacks, or a small move on the front end to change that. Nothing structural has changed, more deficits, more issuance, more money supply. We still take no longs here.
SHORT-TERM TREND CHANGES SINCE LAST WEEK
• NONE
MEDIUM-TERM TREND CHANGES SINCE LAST WEEK
• NONE
COT CHANGES SINCE LAST WEEK
• NONE
AGRICULTURE
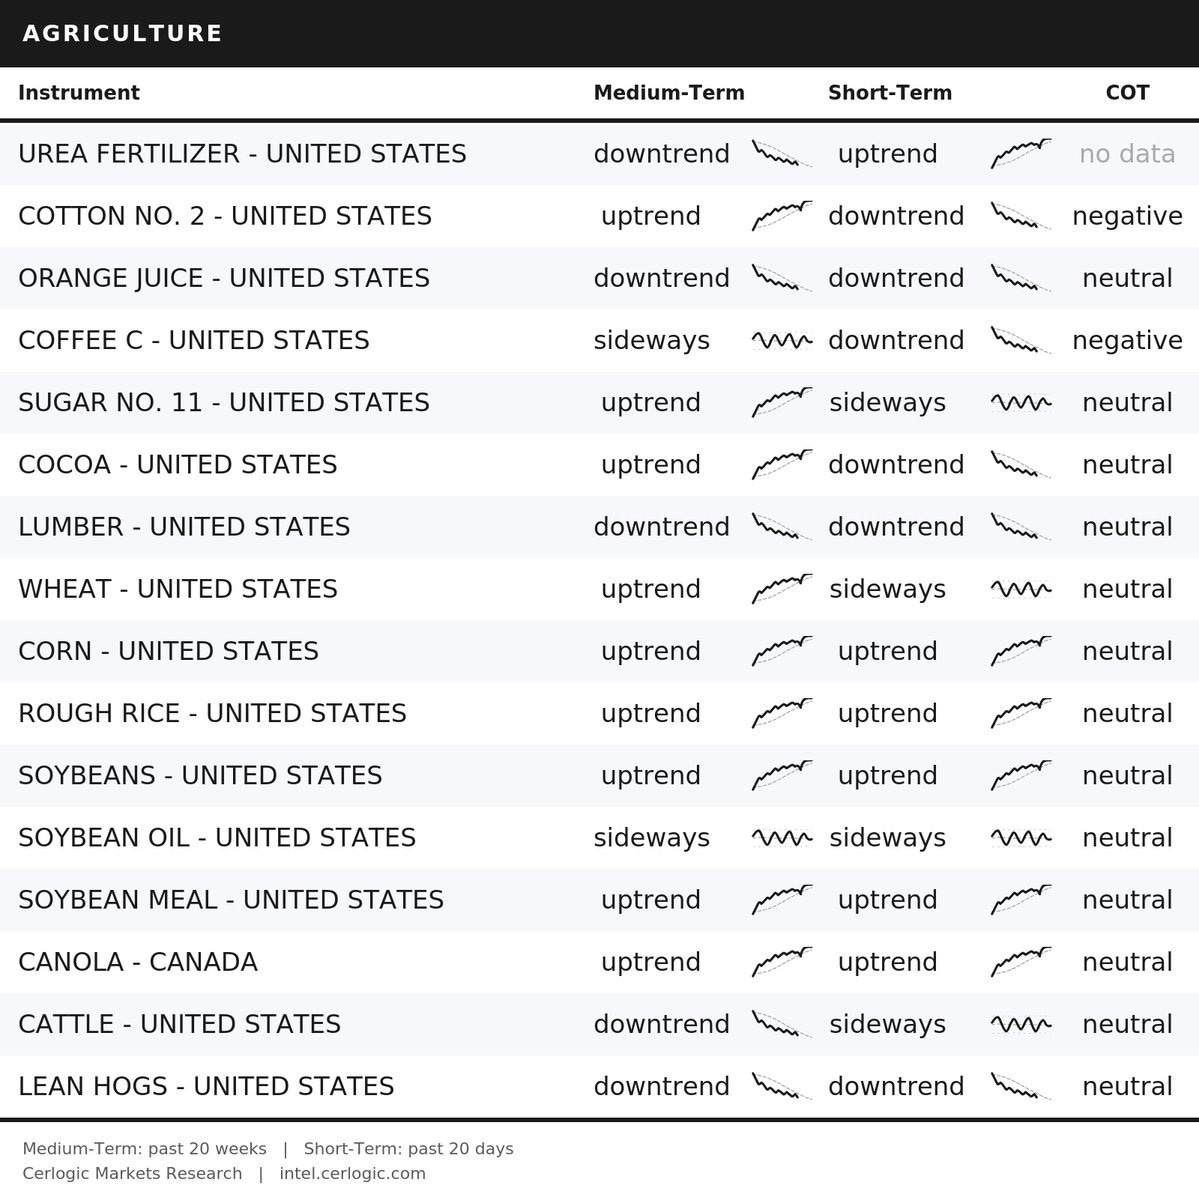
This week it’s the softs taking the bigger hit, cotton, orange juice and cocoa all rolling into short-term downtrends, sugar and wheat easing back to sideways as well.
But the grain and soy complex still holds firm underneath, corn, beans and meal all in their uptrends.
Same as always, sharp moves to new highs then violent pullbacks to higher lows, it’s just how they advance. Two ways to play it, swing the individual commodities short-term, or hold long-term and take the good with the bad of the bull run. Both depend on the trader’s psychology.
The bigger picture stays the same, and it points up. The fertilizer and energy damage is done, and El Niño is still out there. We stay long where the trends hold, and let the prices move as far as necessary to incentivize production.
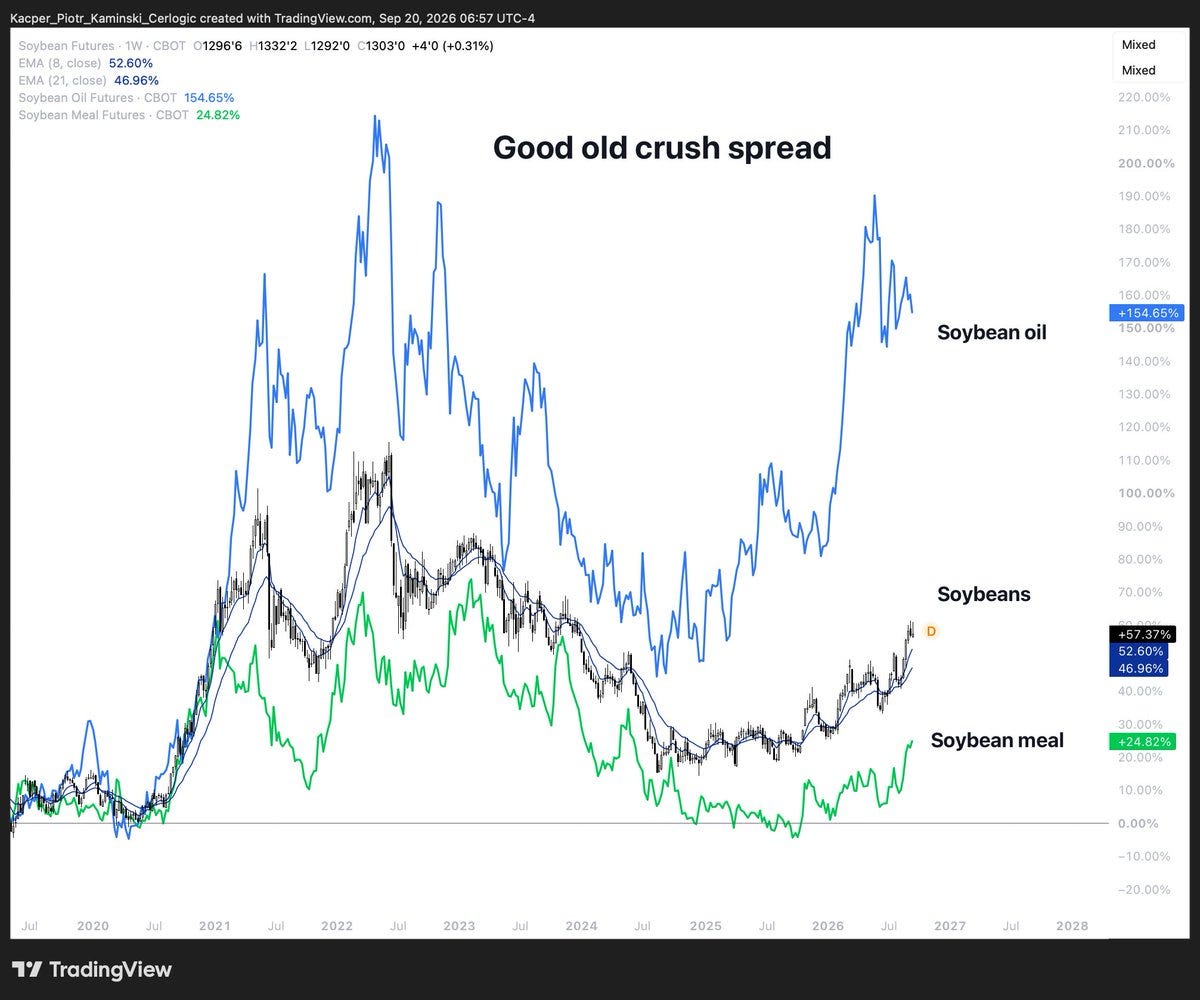
The crush spread setup we’ve got our eye started moving, way ahead of our base case for it to happen in 2027. We won’t complain, it’s working.
And on fertilizer equities, they typically move well into an ags bull market. Farmers need the money to buy them, so they need to sell their production at high prices into the future. Right now they’re struggling, fuel prices through the roof, and it’s usually right here that governments step in, subsidies, tax breaks, that’s the tell, it’s where the fertilizer cycle begins.
SHORT-TERM TREND CHANGES SINCE LAST WEEK
• COTTON NO. 2 – UNITED STATES: sideways ➝ downtrend
• ORANGE JUICE – UNITED STATES: sideways ➝ downtrend
• SUGAR NO. 11 – UNITED STATES: uptrend ➝ sideways
• COCOA – UNITED STATES: sideways ➝ downtrend
• WHEAT – UNITED STATES: uptrend ➝ sideways
MEDIUM-TERM TREND CHANGES SINCE LAST WEEK
• SOYBEAN OIL – UNITED STATES: uptrend ➝ sideways
COT CHANGES SINCE LAST WEEK
• COTTON NO. 2 – UNITED STATES: neutral ➝ negative
That’s it for now. Stay safe out there!
Kacper Piotr Kaminski, Cerlogic Markets Research – intel.cerlogic.com
This publication is for informational and educational purposes only and does not constitute investment advice. Markets involve risk, and every participant is responsible for their own decisions.