

“The market being in a trend is the main thing that eventually gets us in a trade. That is a pretty simple idea.
Being consistent and making sure you do that all the time is probably more important than the particular characteristics you use to define the trend.
Whatever method you use to enter trades, the most critical thing is that if there is a major trend, your approach should assure that you get in that trend.”
Richard Dennis
EQUITY MARKETS – INDICES
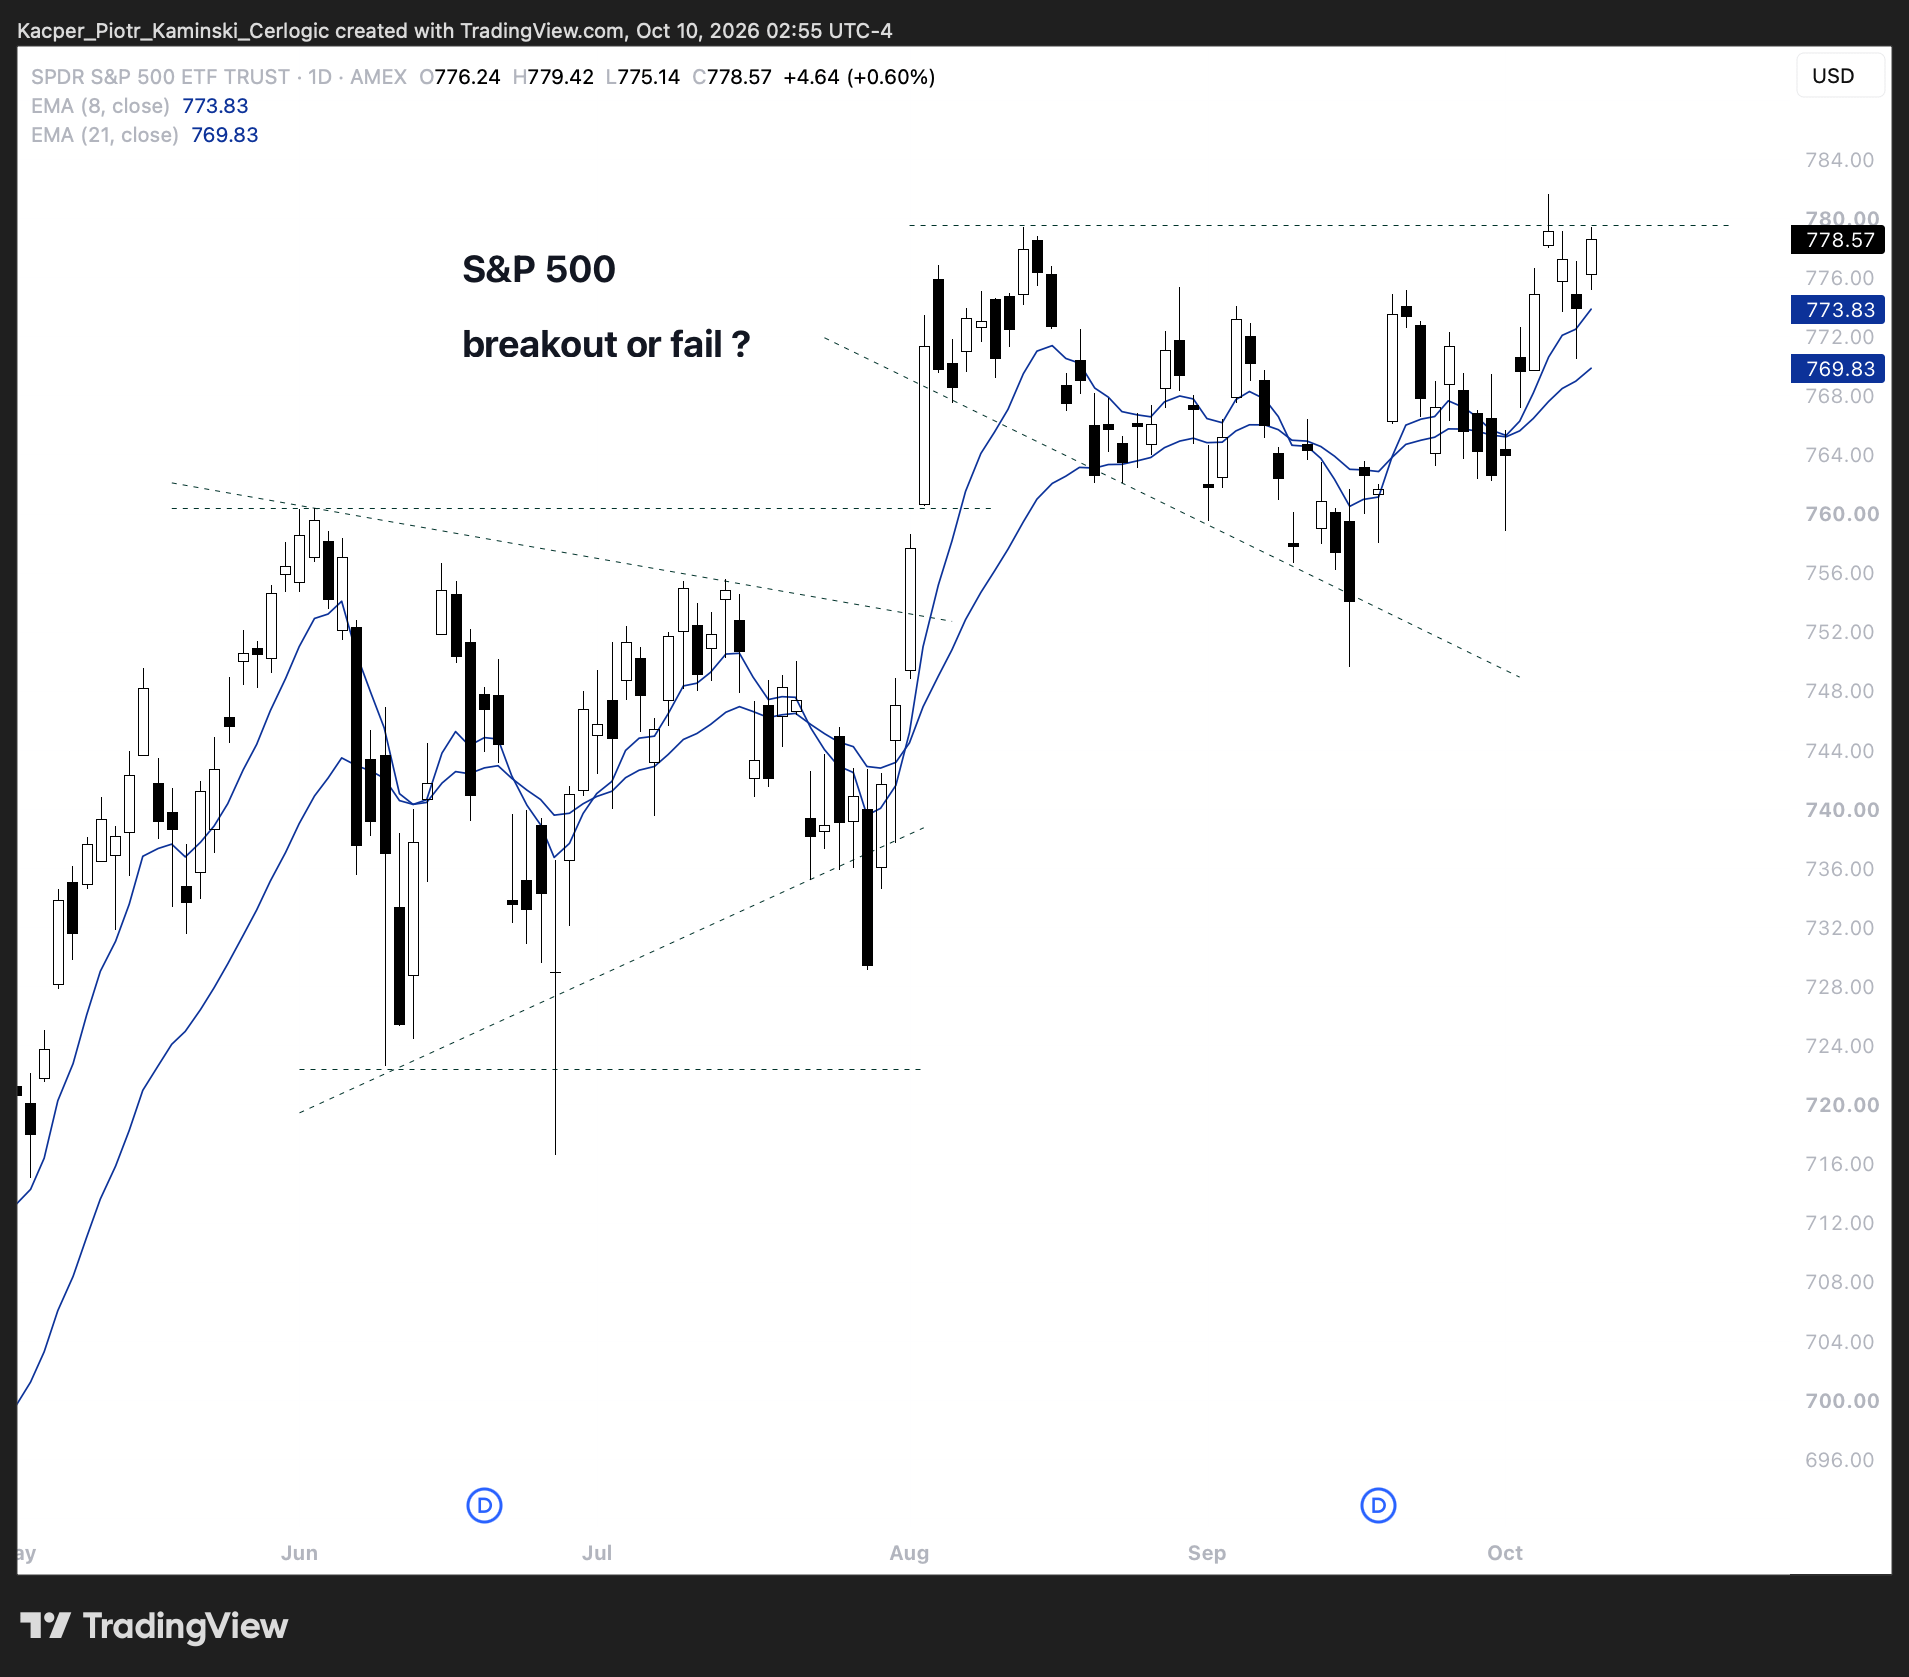
The split continues. It’s still mostly about US tech, at least for now, that’s where the money is going. The S&P and the Nasdaq, driven by the AI trade, or pardon me, the “SI trade”, are just about the last indices still trending up.
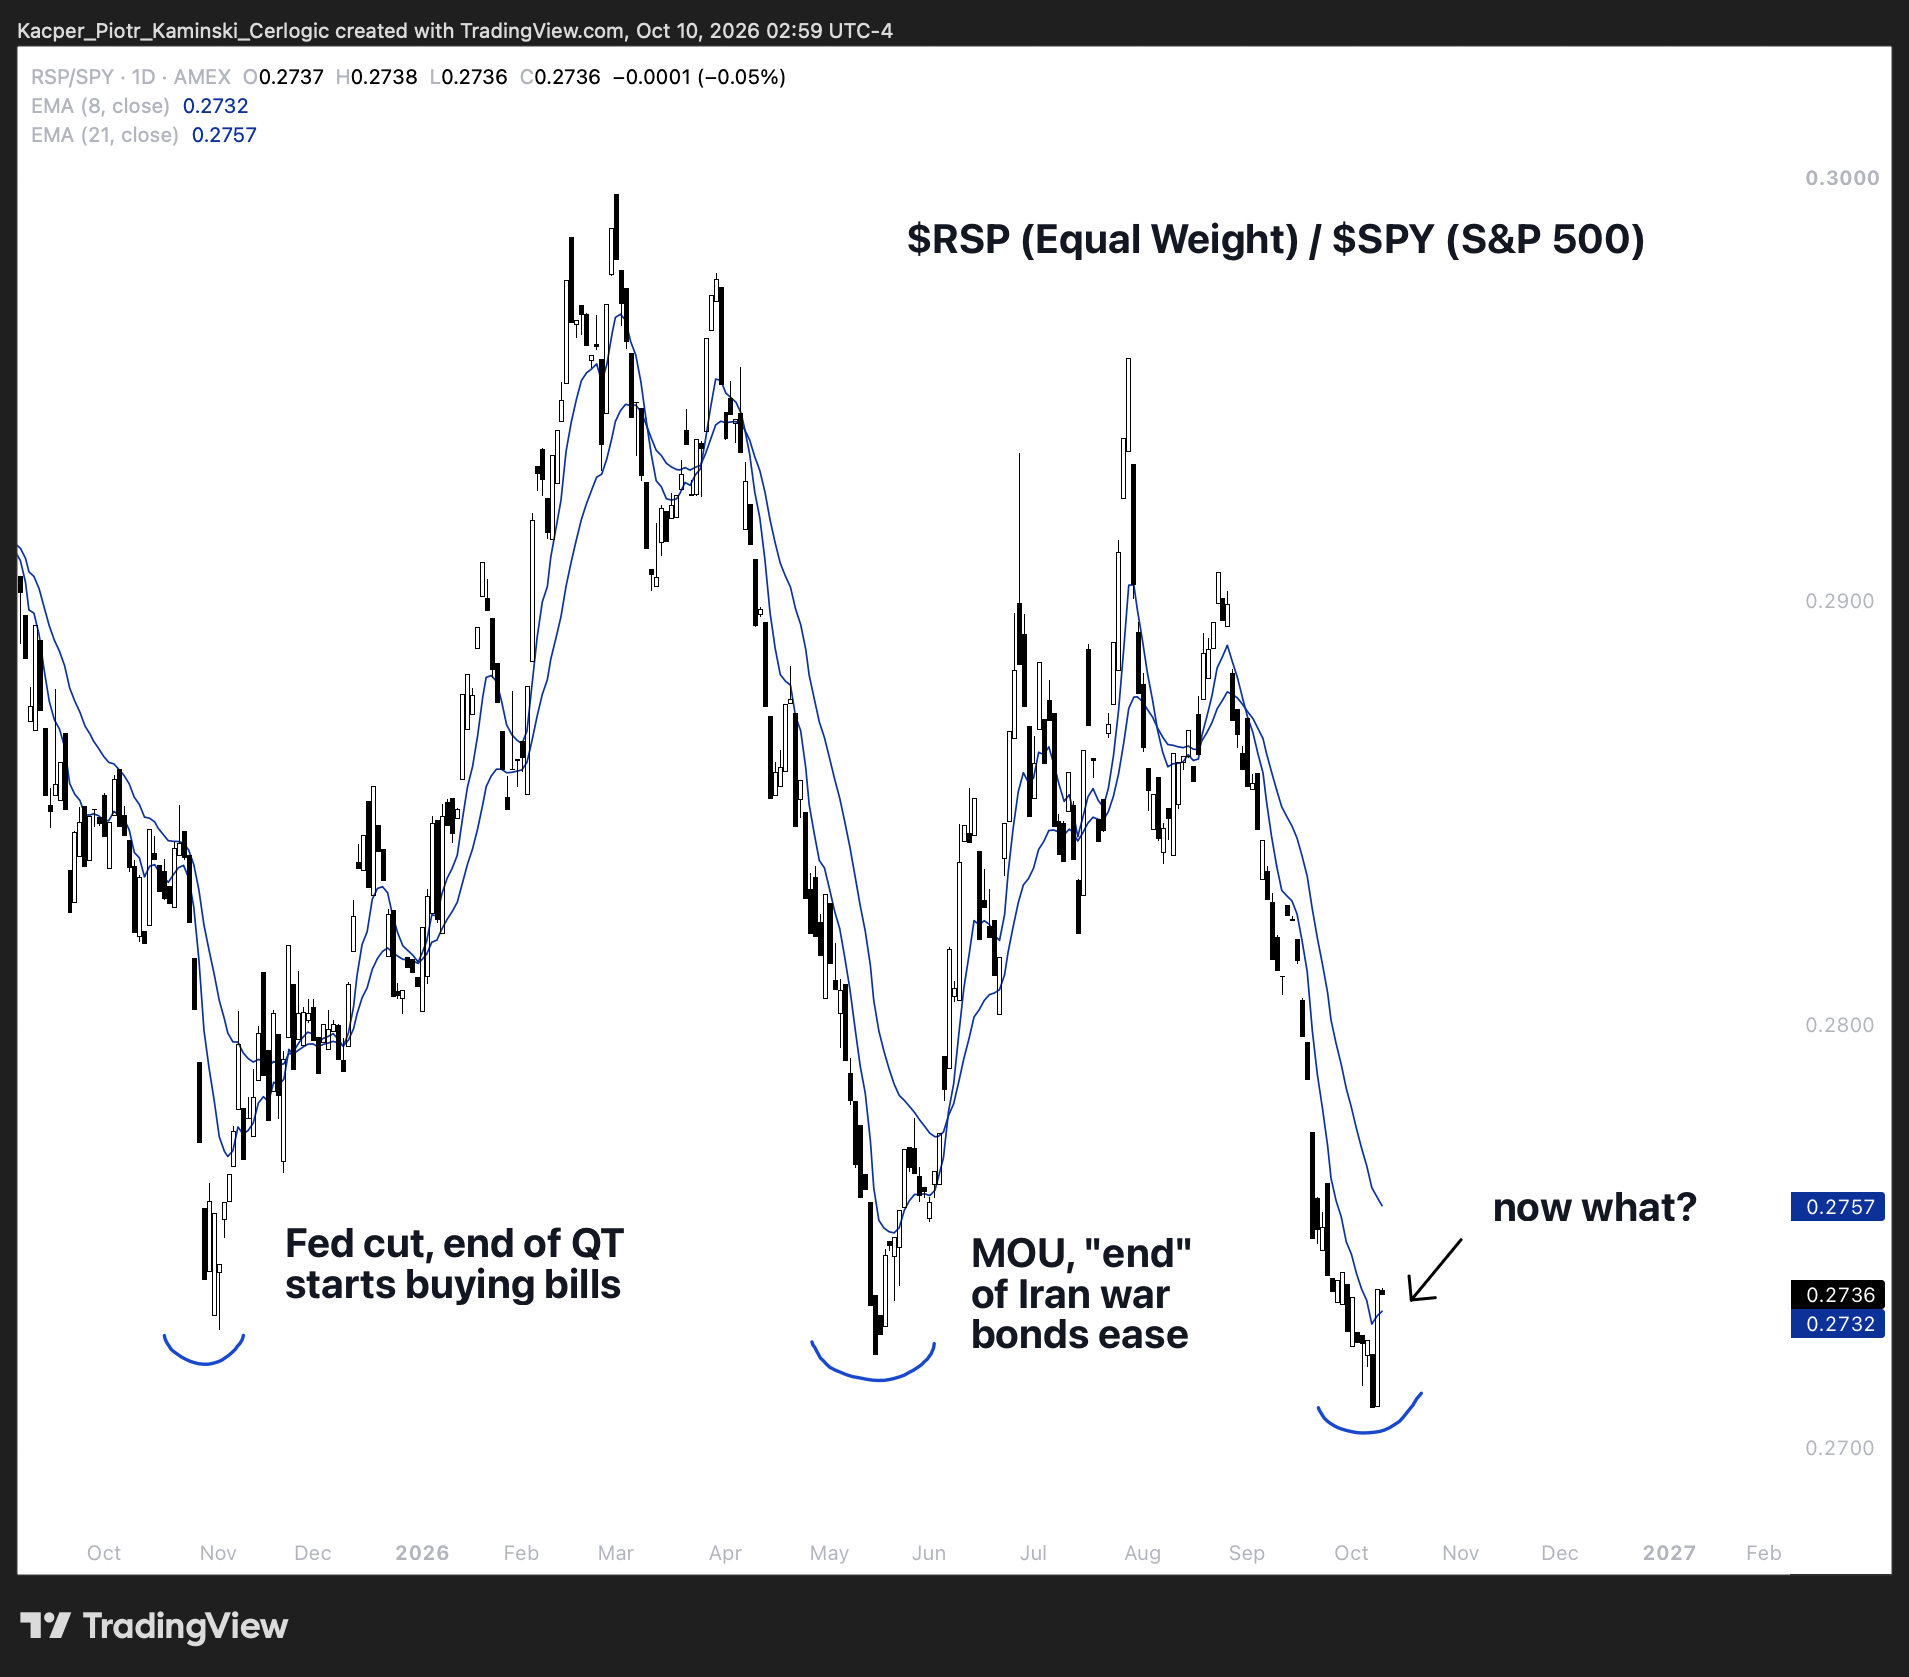
That said, there are signs of life elsewhere. Q4 opened with real buying in US financials, consumer defensive, utilities and energy, and the equal weighted S&P 500, $RSP, is ticking up against $SPY.
Now, if the index stays pinned and tech so much as stops advancing, some of that money could rotate into those sectors, and once it does, momentum piles in on top and it becomes the go-to trade for the quarter. That’s just one of the dynamics in these highly distorted, passive driven markets. Then we have elections, in US and so many other countries, and war. Lots of unknowns, so we’ll cut the noise and stick to the market action, we won’t fight it. One thing that appears entirely misplaced is volatility.
In the broader picture though, it’s still all about the AI trade, the enormous debt and the out of this world capex, backed by governments all over the world. The growth story is the AI story now. It can’t slow, because if it does, markets go down, capex goes away, earnings numbers driven by equity holdings collapse, and so does the nominal value of savings, insurance and retirement accounts, restricting spending and feeding a recession loop.
That’s why they’ll print it away, or, as they say, “grow our way out of it”. Or they’ll try, because you can’t grow your way out of government debt when the inflation itself comes from that debt rising. You’d need enormous private bank lending for that, but hey, that too is brand new money creation.
And so, structurally nothing changes. They spend like there’s no tomorrow, social transfers, defense, some infrastructure, maybe the private AI tab too. The only real question is about the debt-driven money creation. For now, it’s going at full speed, feeding the K-shaped economy, globally. If it just slows down, then markets get in serious trouble.
Whatever policy they choose, we’ll be ready. We go with the trends, as you know. We’re hunting for the next major move, ideally from depressed levels. The real money is made by going with major trends, and we see almost none of that out there right now. Patience is key at this very moment. So we keep trading what’s in front of us, hold what’s still working, and otherwise keep the dry powder for the next big opportunity.
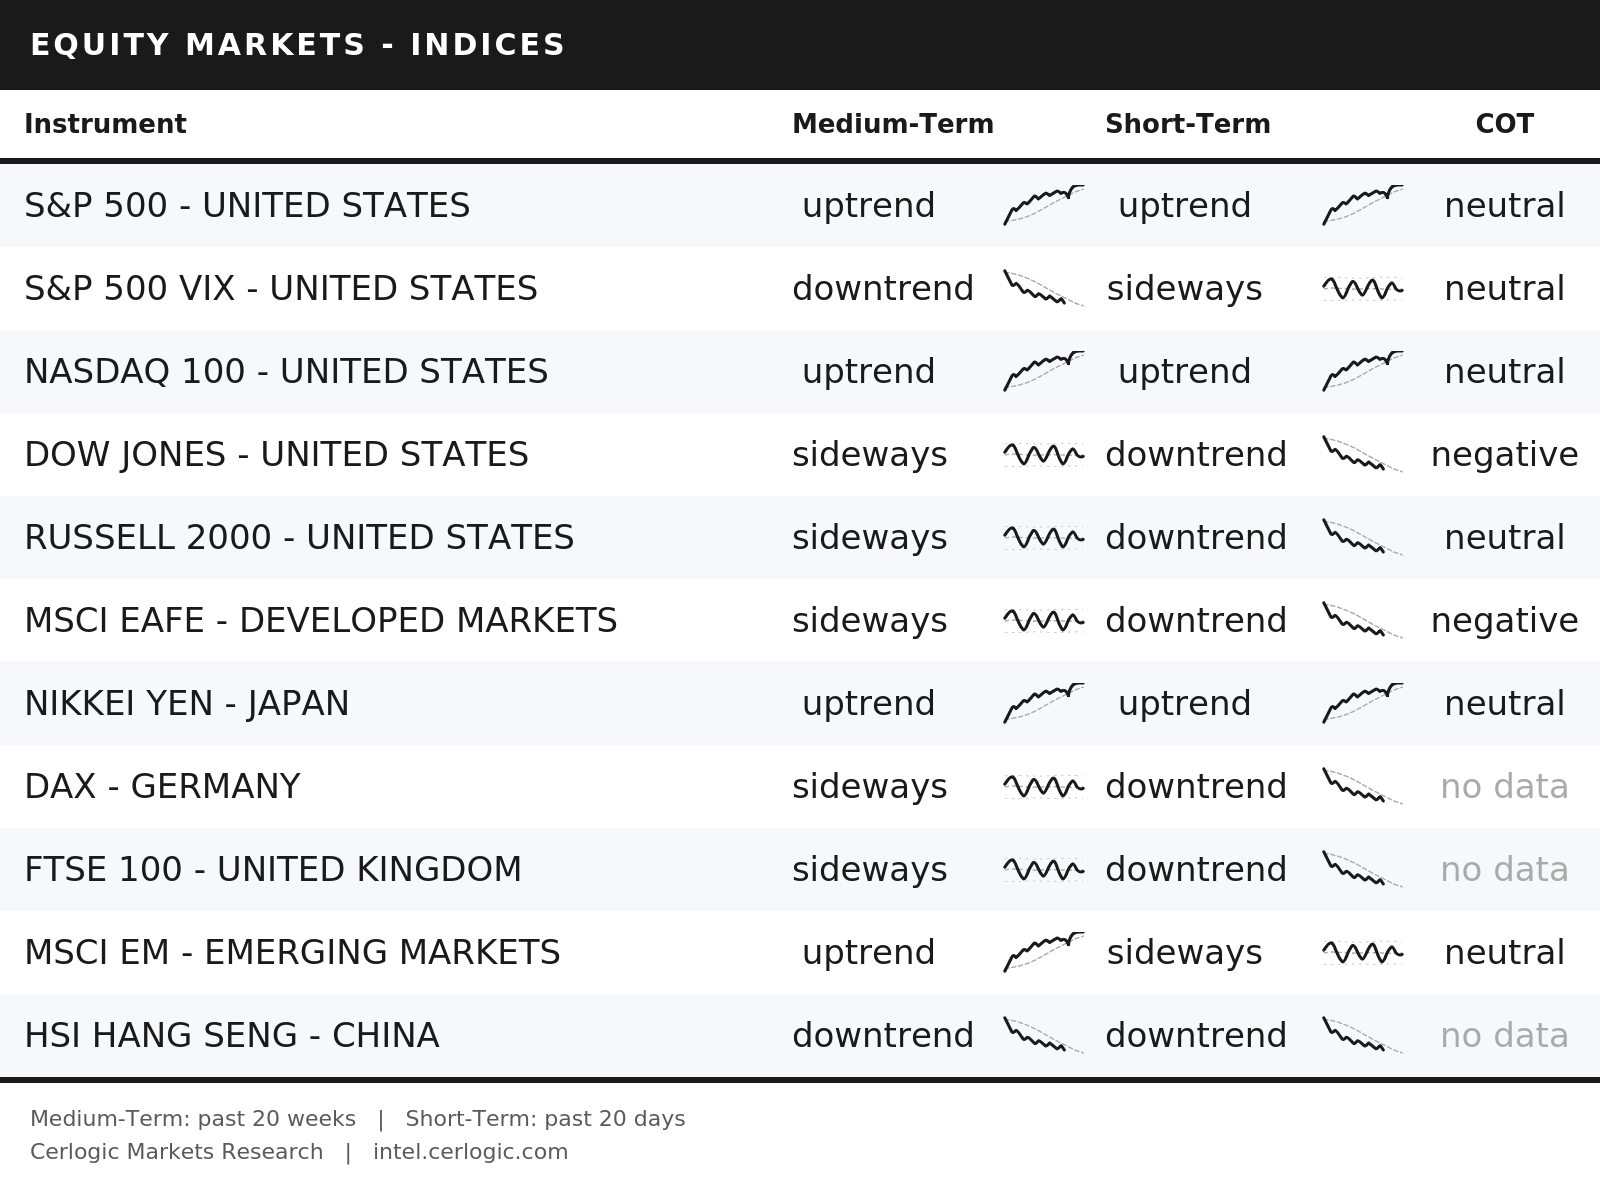
SHORT-TERM TREND CHANGES SINCE LAST WEEK
• S&P 500 – UNITED STATES: sideways ➝ uptrend
MEDIUM-TERM TREND CHANGES SINCE LAST WEEK
• NONE
COT CHANGES SINCE LAST WEEK
• RUSSELL 2000 – UNITED STATES: negative ➝ neutral
CHARTS OF THE WEEK :
FOREX
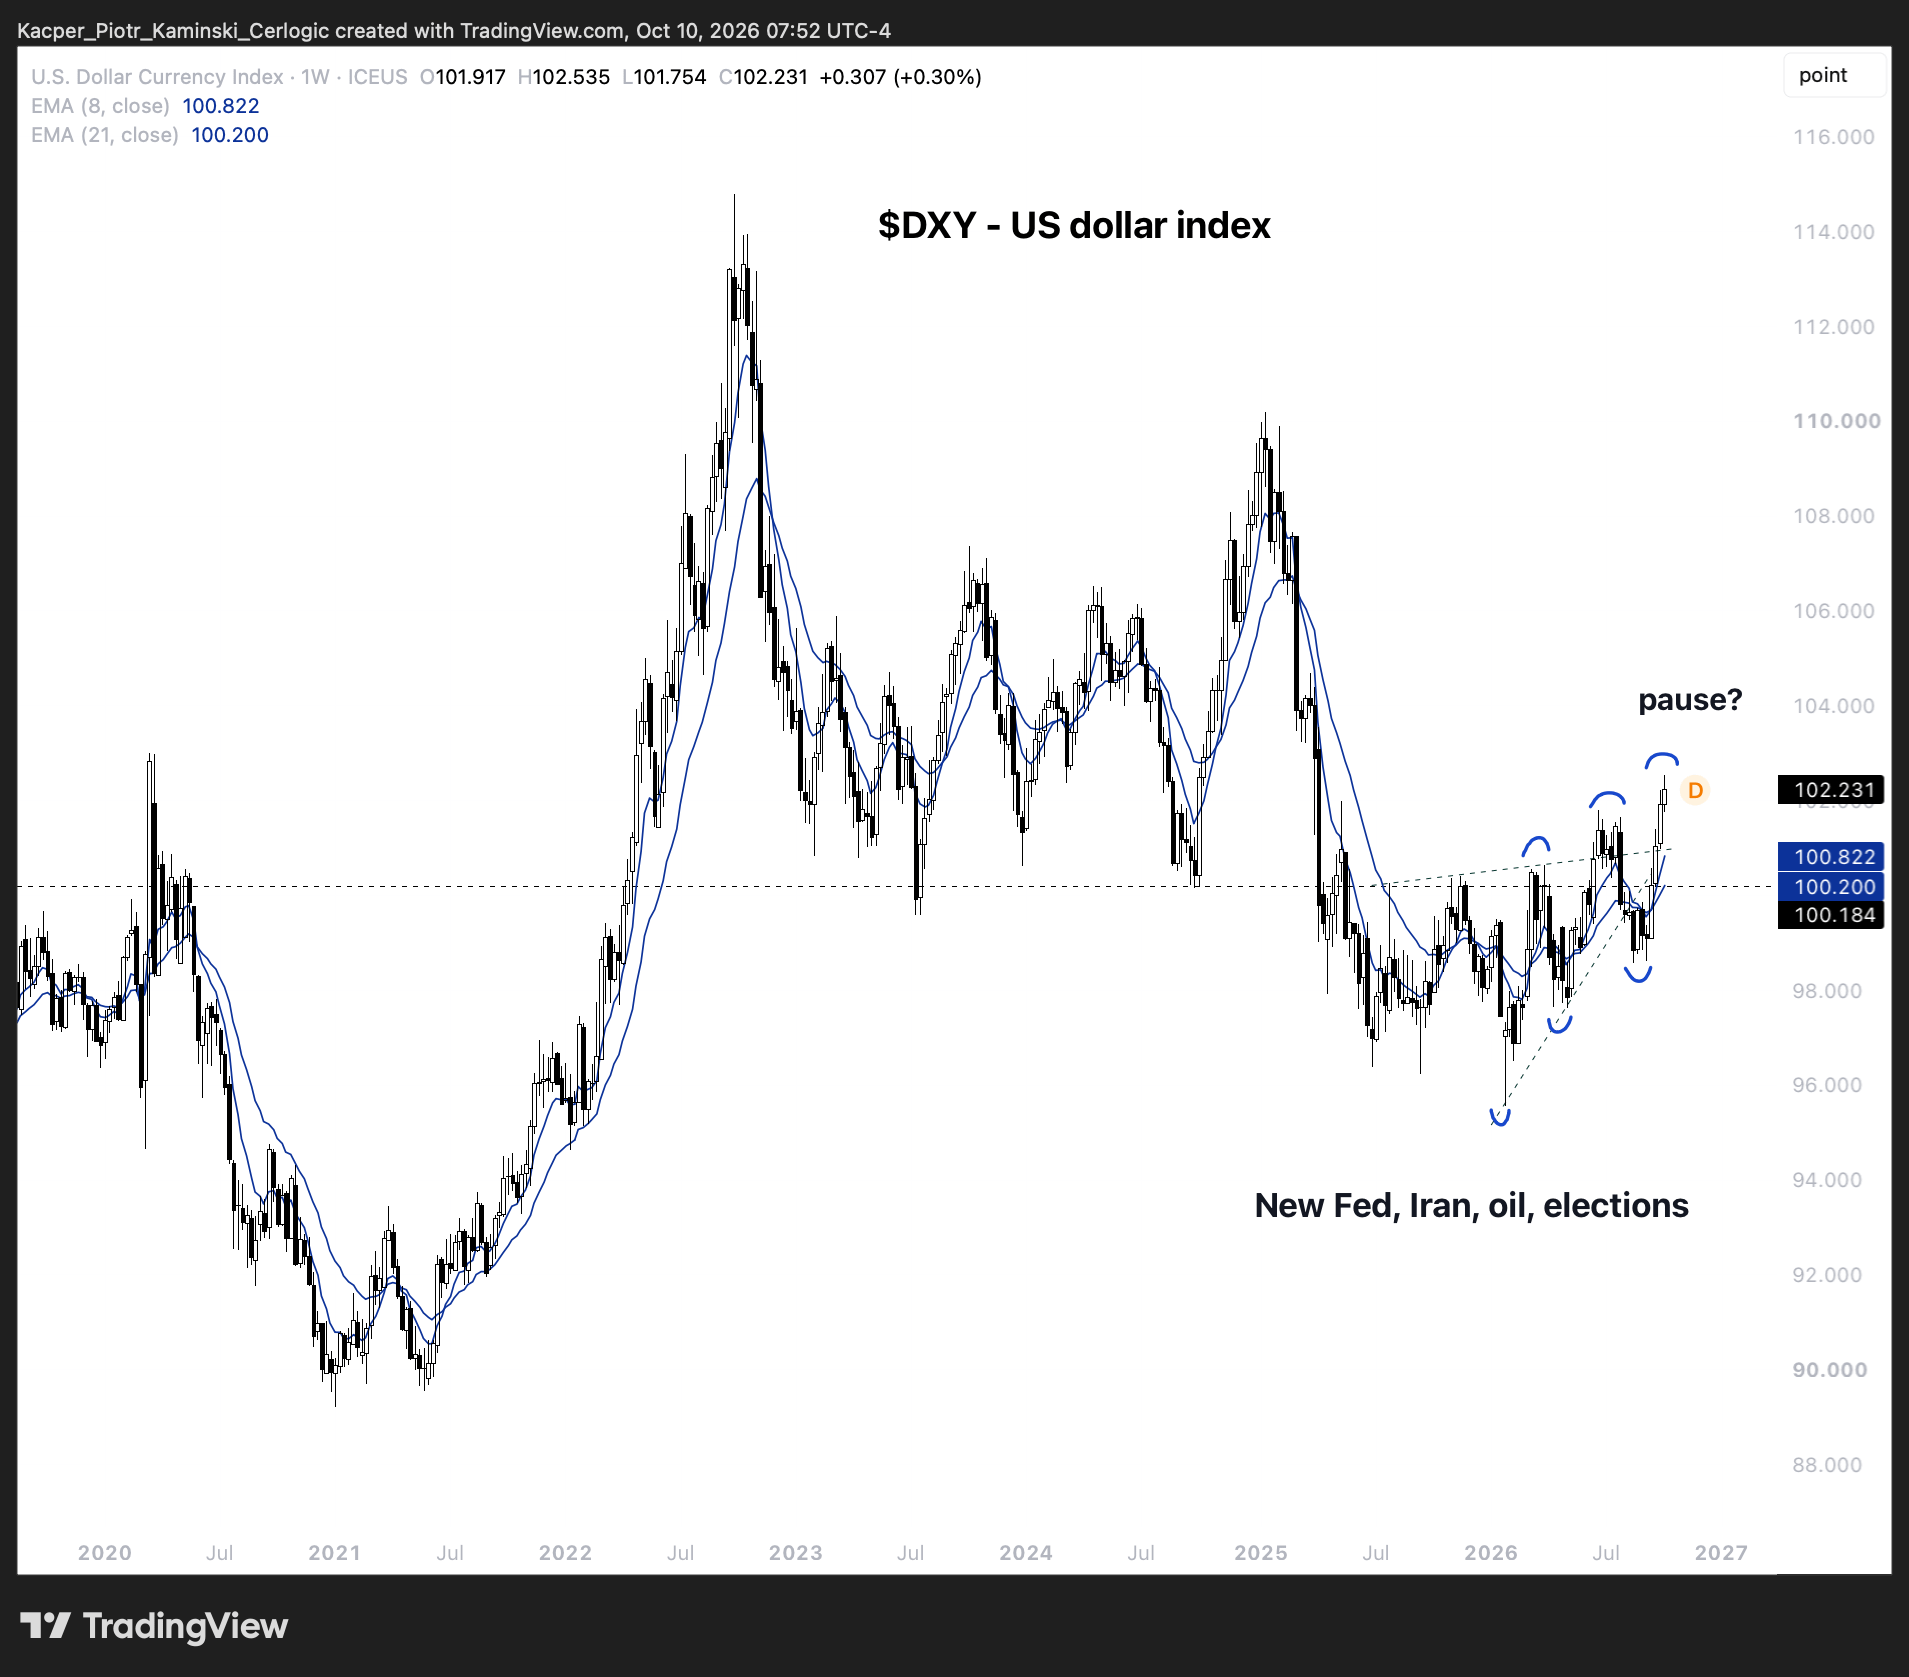
The dollar’s run paused a little last week, finally. Will it continue is still the political question, war, oil, the TGA account, a Fed flip. Trend will tell us first.
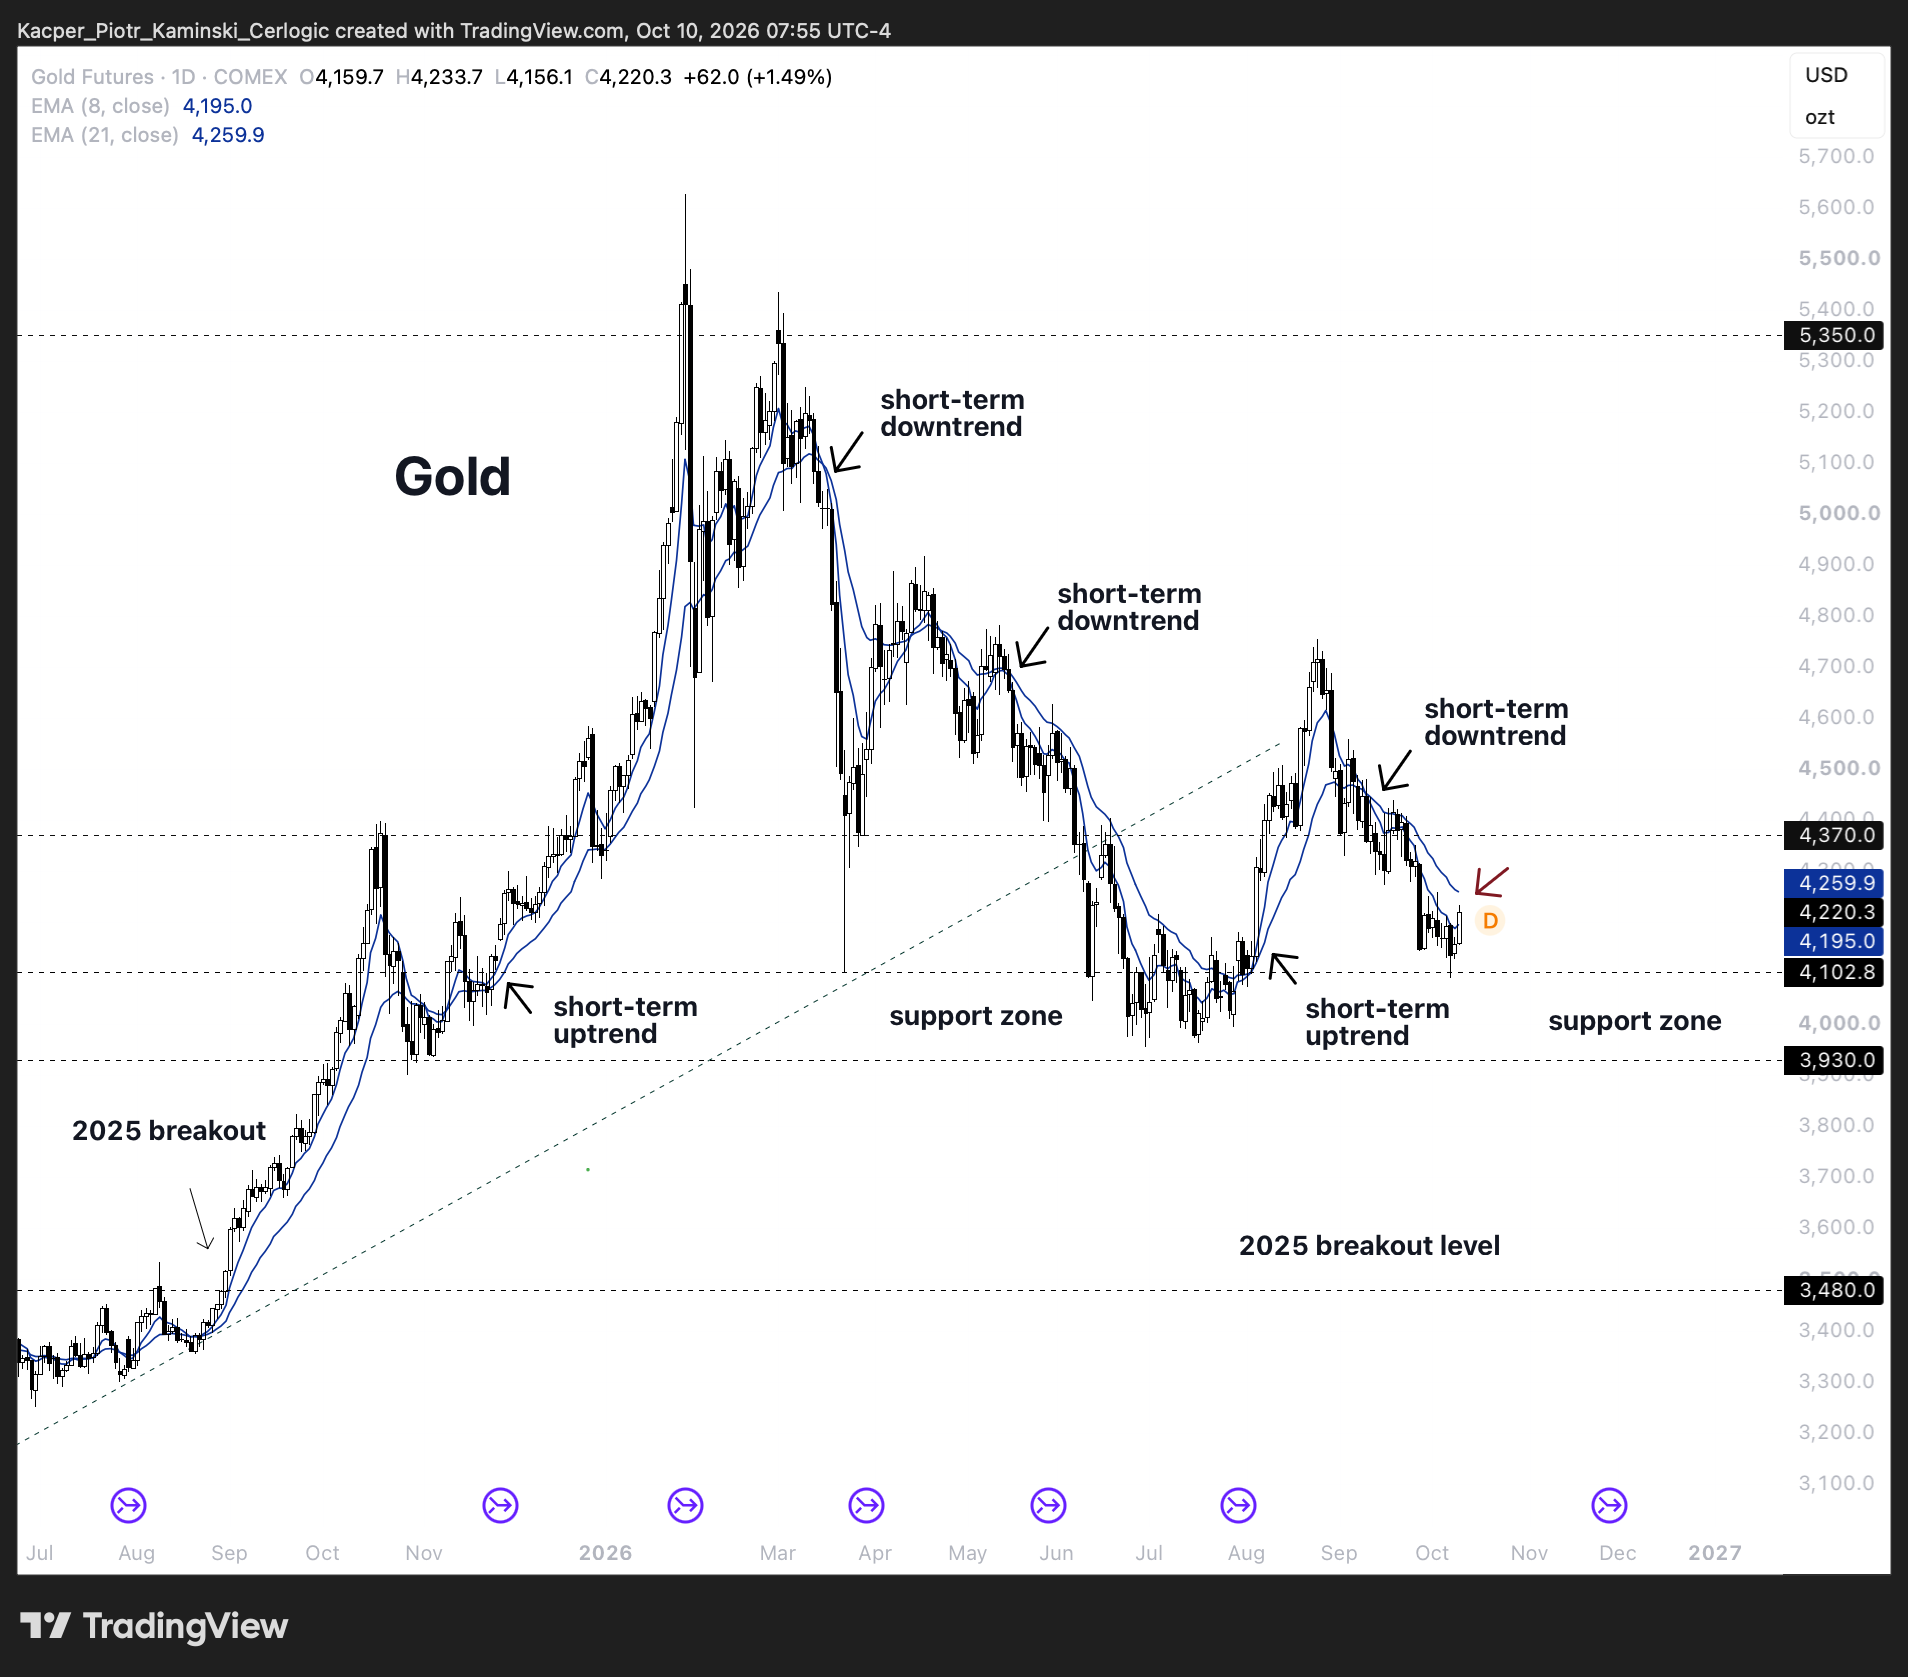
Dollar paused, and so, gold stabilized, actually closed green on the week. The positioning turned as well, coming back from negative to neutral, which means not many are long here. Still in downtrend, so no longs in trading, but harvest and accumulation in the Gold Strategy.
Crypto cooled off, $BTC and $ETH both easing back to sideways, worth a note.
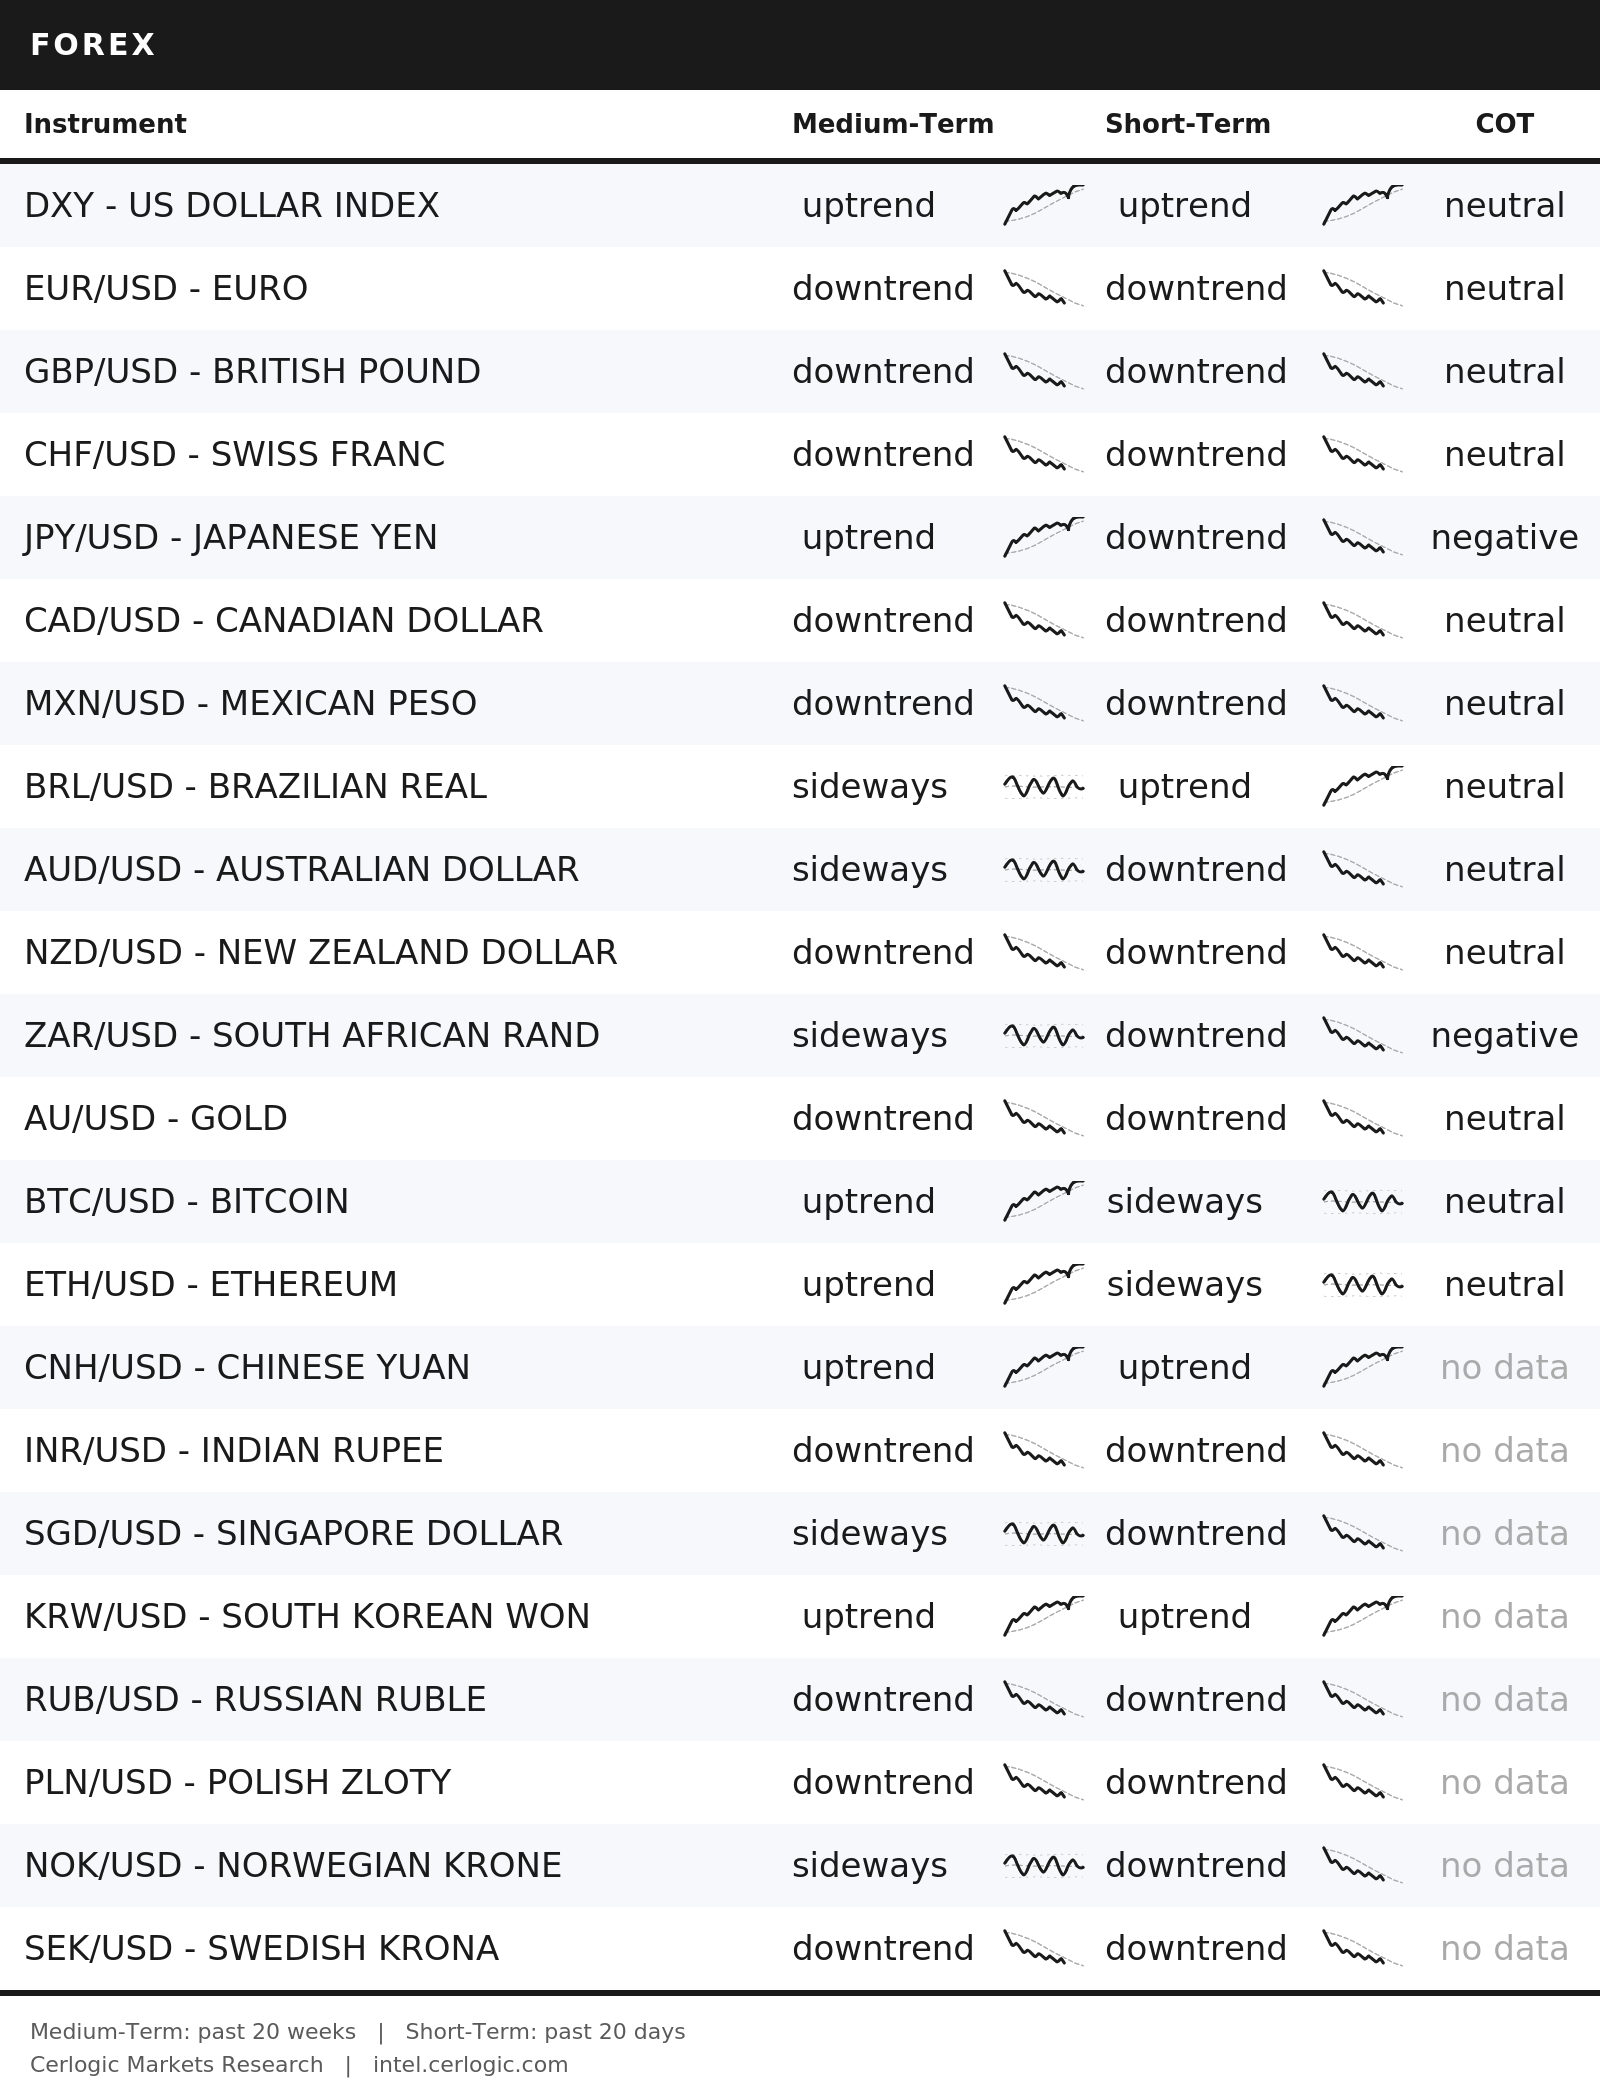
SHORT-TERM TREND CHANGES SINCE LAST WEEK
• BRL/USD – BRAZILIAN REAL: downtrend ➝ uptrend
• BTC/USD – BITCOIN: uptrend ➝ sideways
• ETH/USD – ETHEREUM: uptrend ➝ sideways
• CNH/USD – CHINESE YUAN: sideways ➝ uptrend
• RUB/USD – RUSSIAN RUBLE: uptrend ➝ downtrend
MEDIUM-TERM TREND CHANGES SINCE LAST WEEK
• BRL/USD – BRAZILIAN REAL: downtrend ➝ sideways
COT CHANGES SINCE LAST WEEK
• BRL/USD – BRAZILIAN REAL: negative ➝ neutral
• AU/USD – GOLD: negative ➝ neutral
CHARTS OF THE WEEK :
INDUSTRIAL METALS
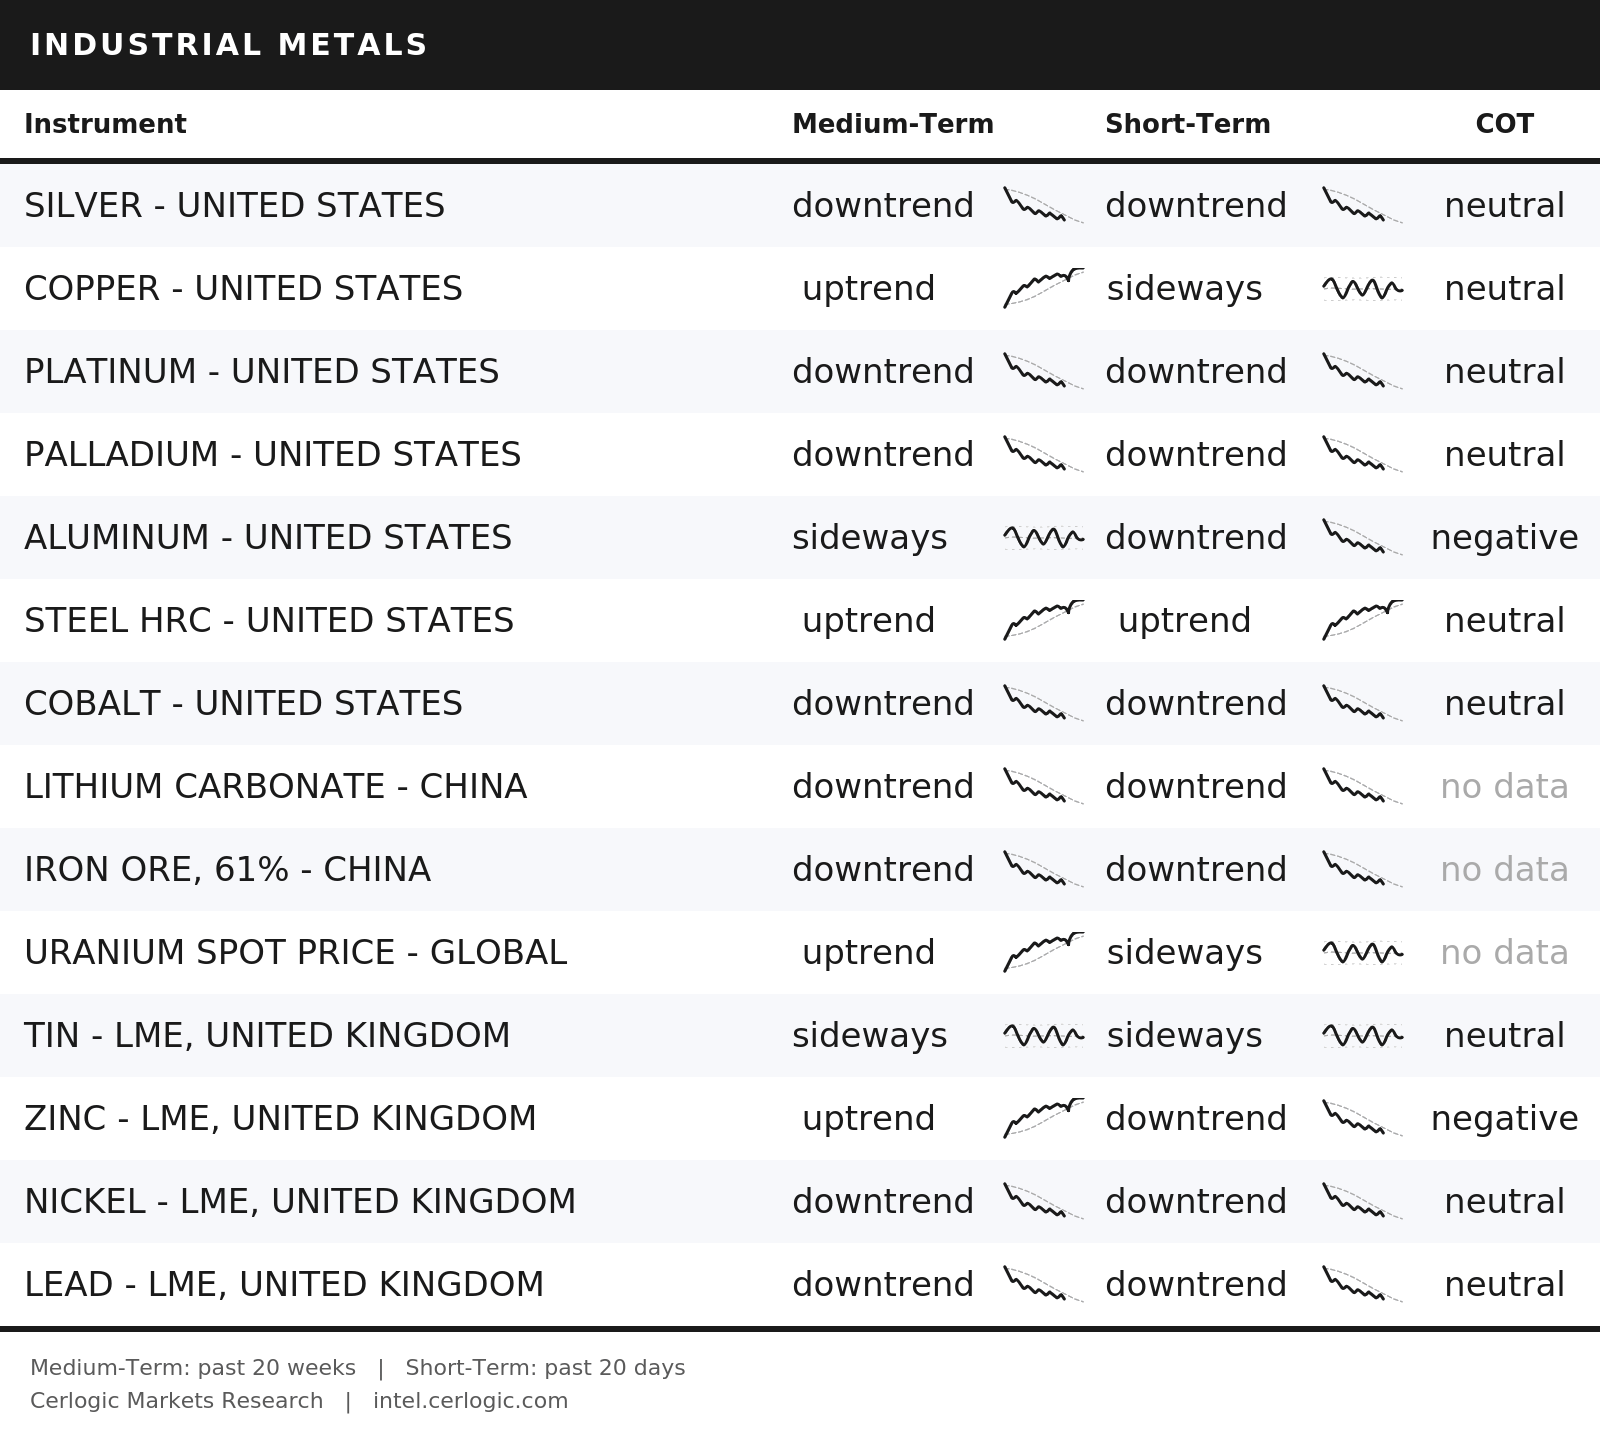
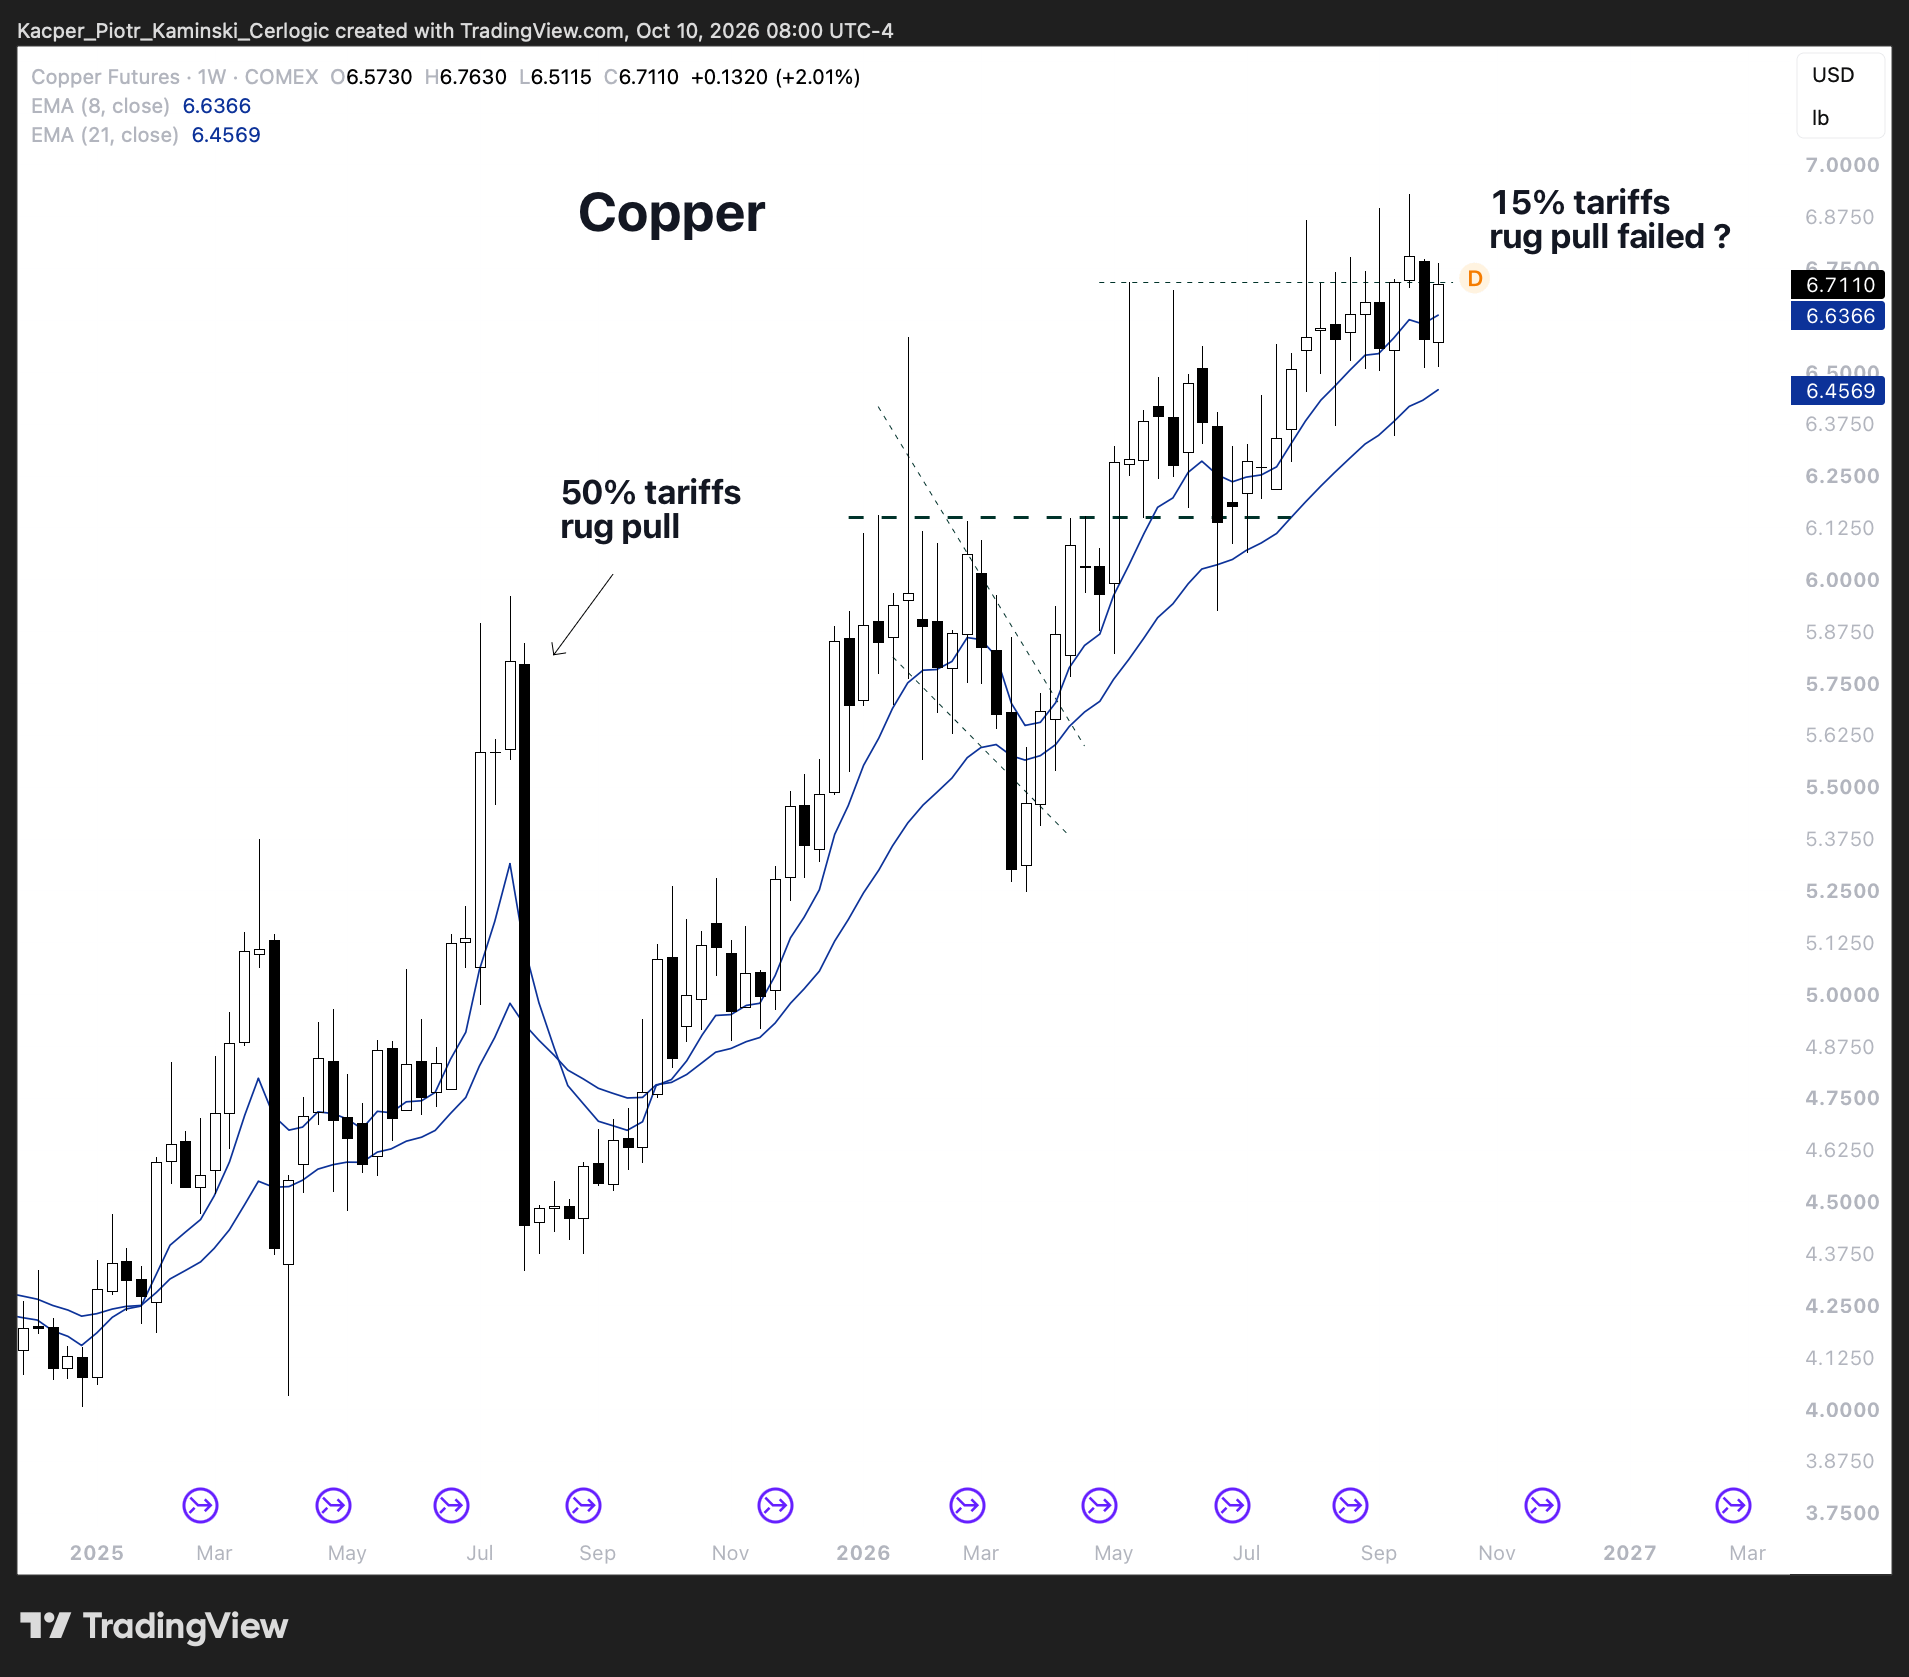
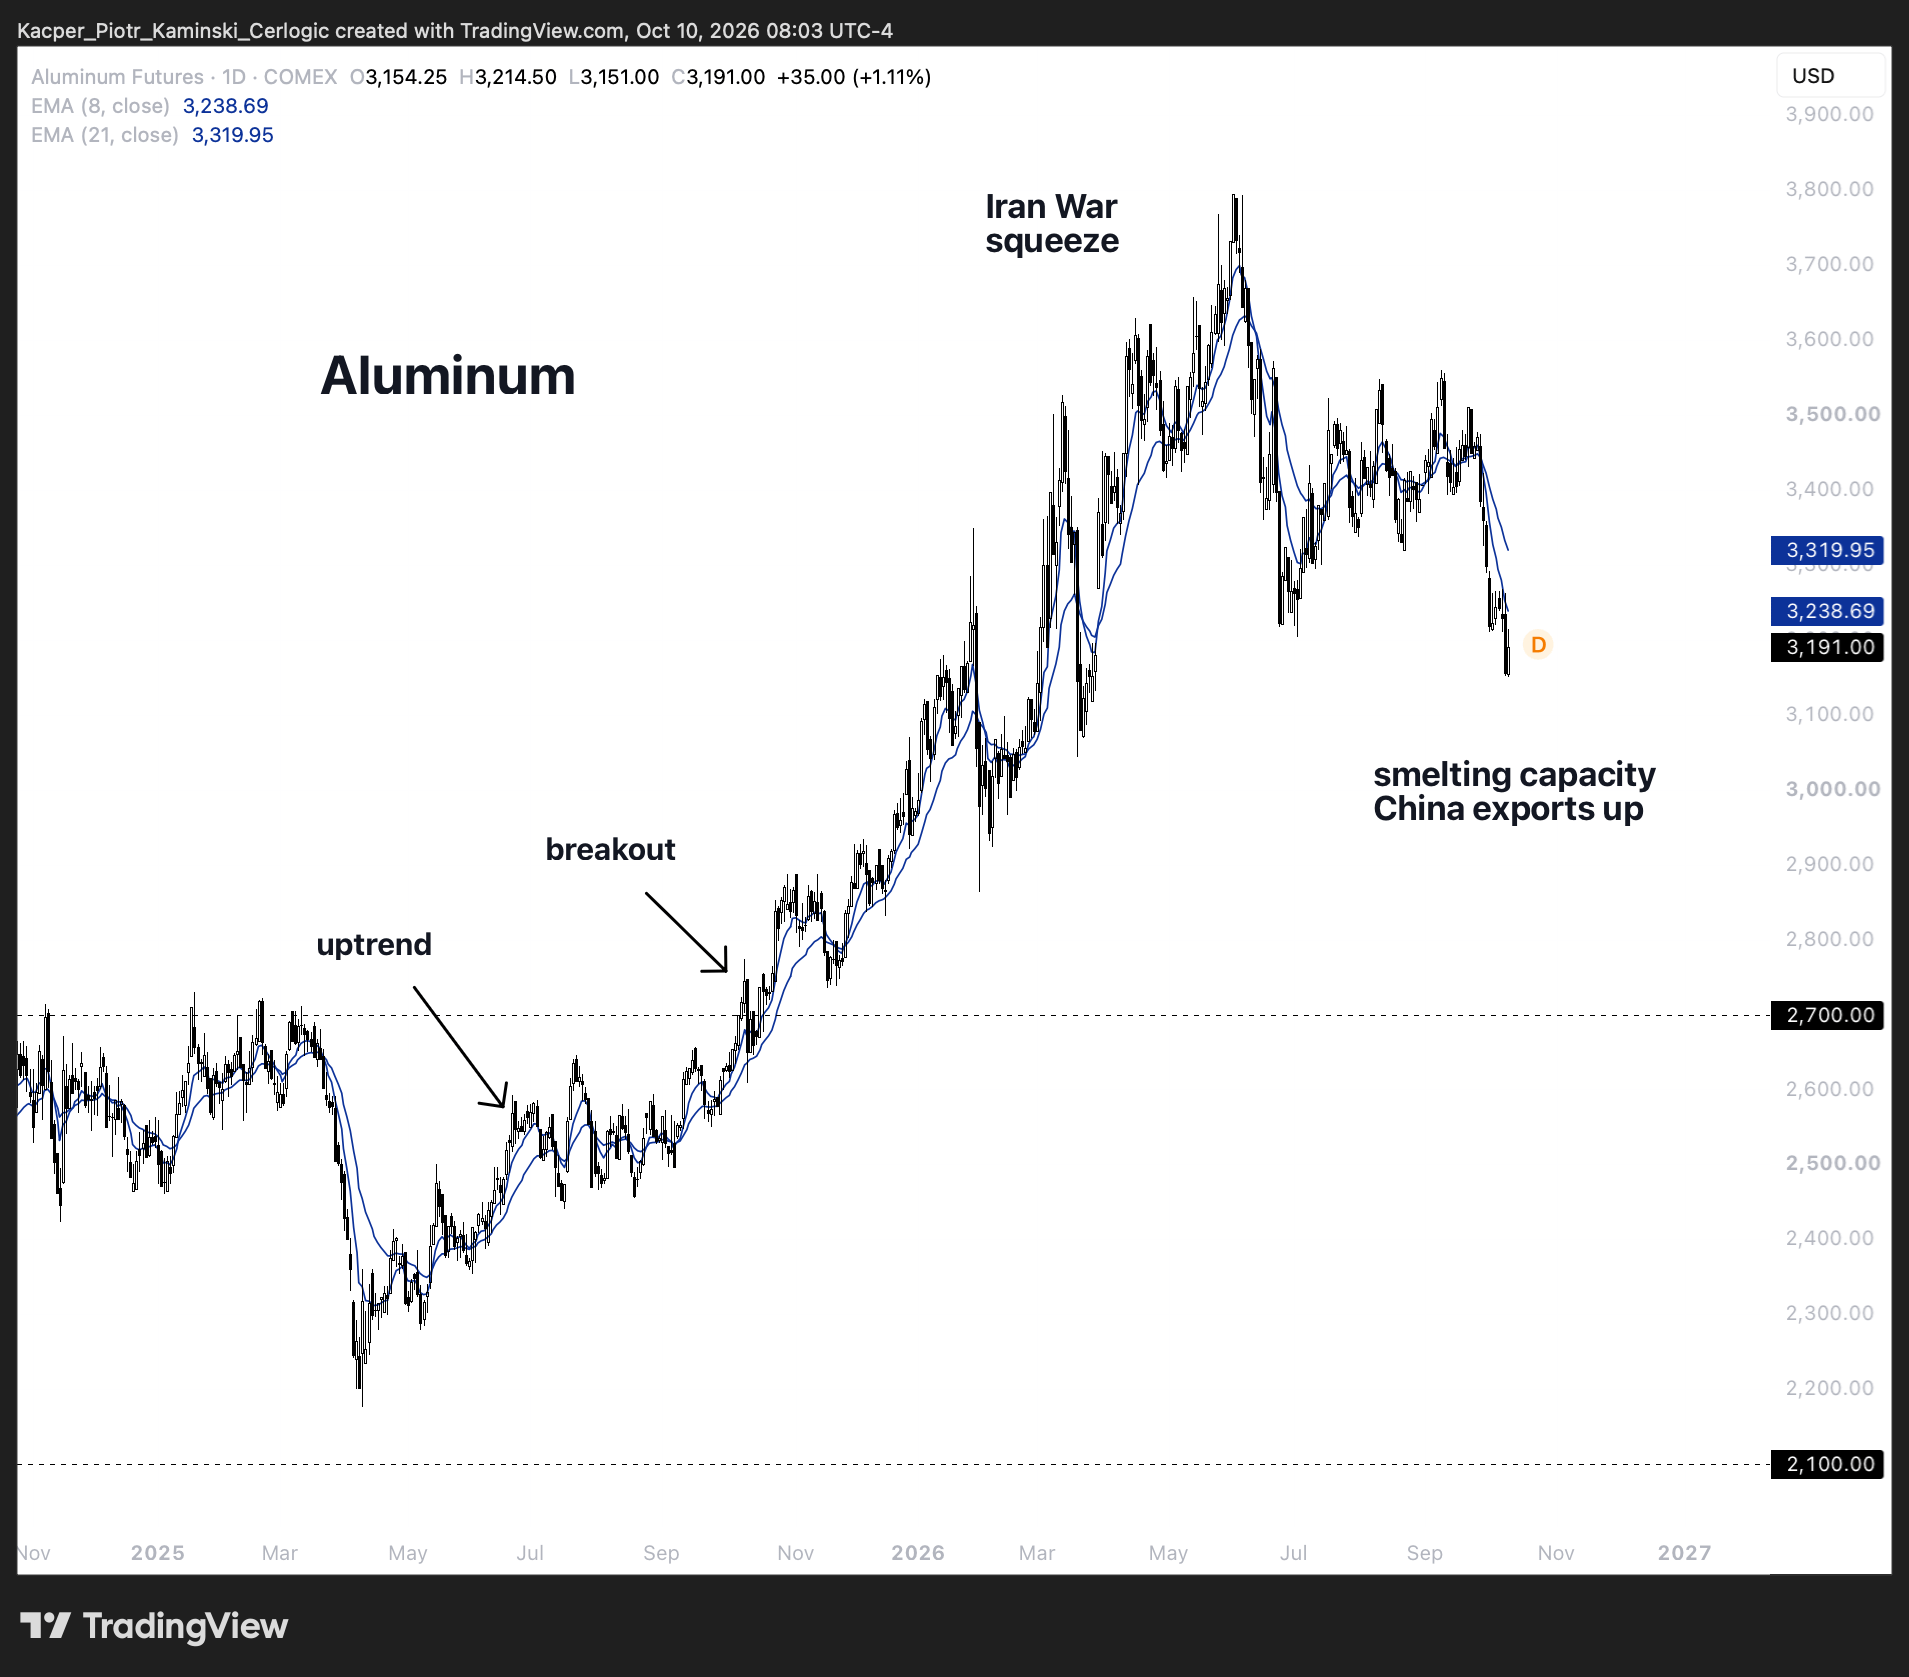
The pressure is working deeper into the metals now. Tin, aluminum, zinc, cobalt, iron ore, all weaker. The precious side stays heavy, same story. Only copper still holds the bigger picture, the king is resting.
Where we go from here is still largely a political question, tied to the energy crisis, hence global economy, same as pretty much every week since March. In the short term anything can happen, so we stay flexible.
SHORT-TERM TREND CHANGES SINCE LAST WEEK
• ZINC – LME, UNITED KINGDOM: sideways ➝ downtrend
MEDIUM-TERM TREND CHANGES SINCE LAST WEEK
• PLATINUM – UNITED STATES: sideways ➝ downtrend
• TIN – LME, UNITED KINGDOM: uptrend ➝ sideways
• LEAD – LME, UNITED KINGDOM: sideways ➝ downtrend
COT CHANGES SINCE LAST WEEK
• ZINC – LME, UNITED KINGDOM: neutral ➝ negative
CHARTS OF THE WEEK :
ENERGIES
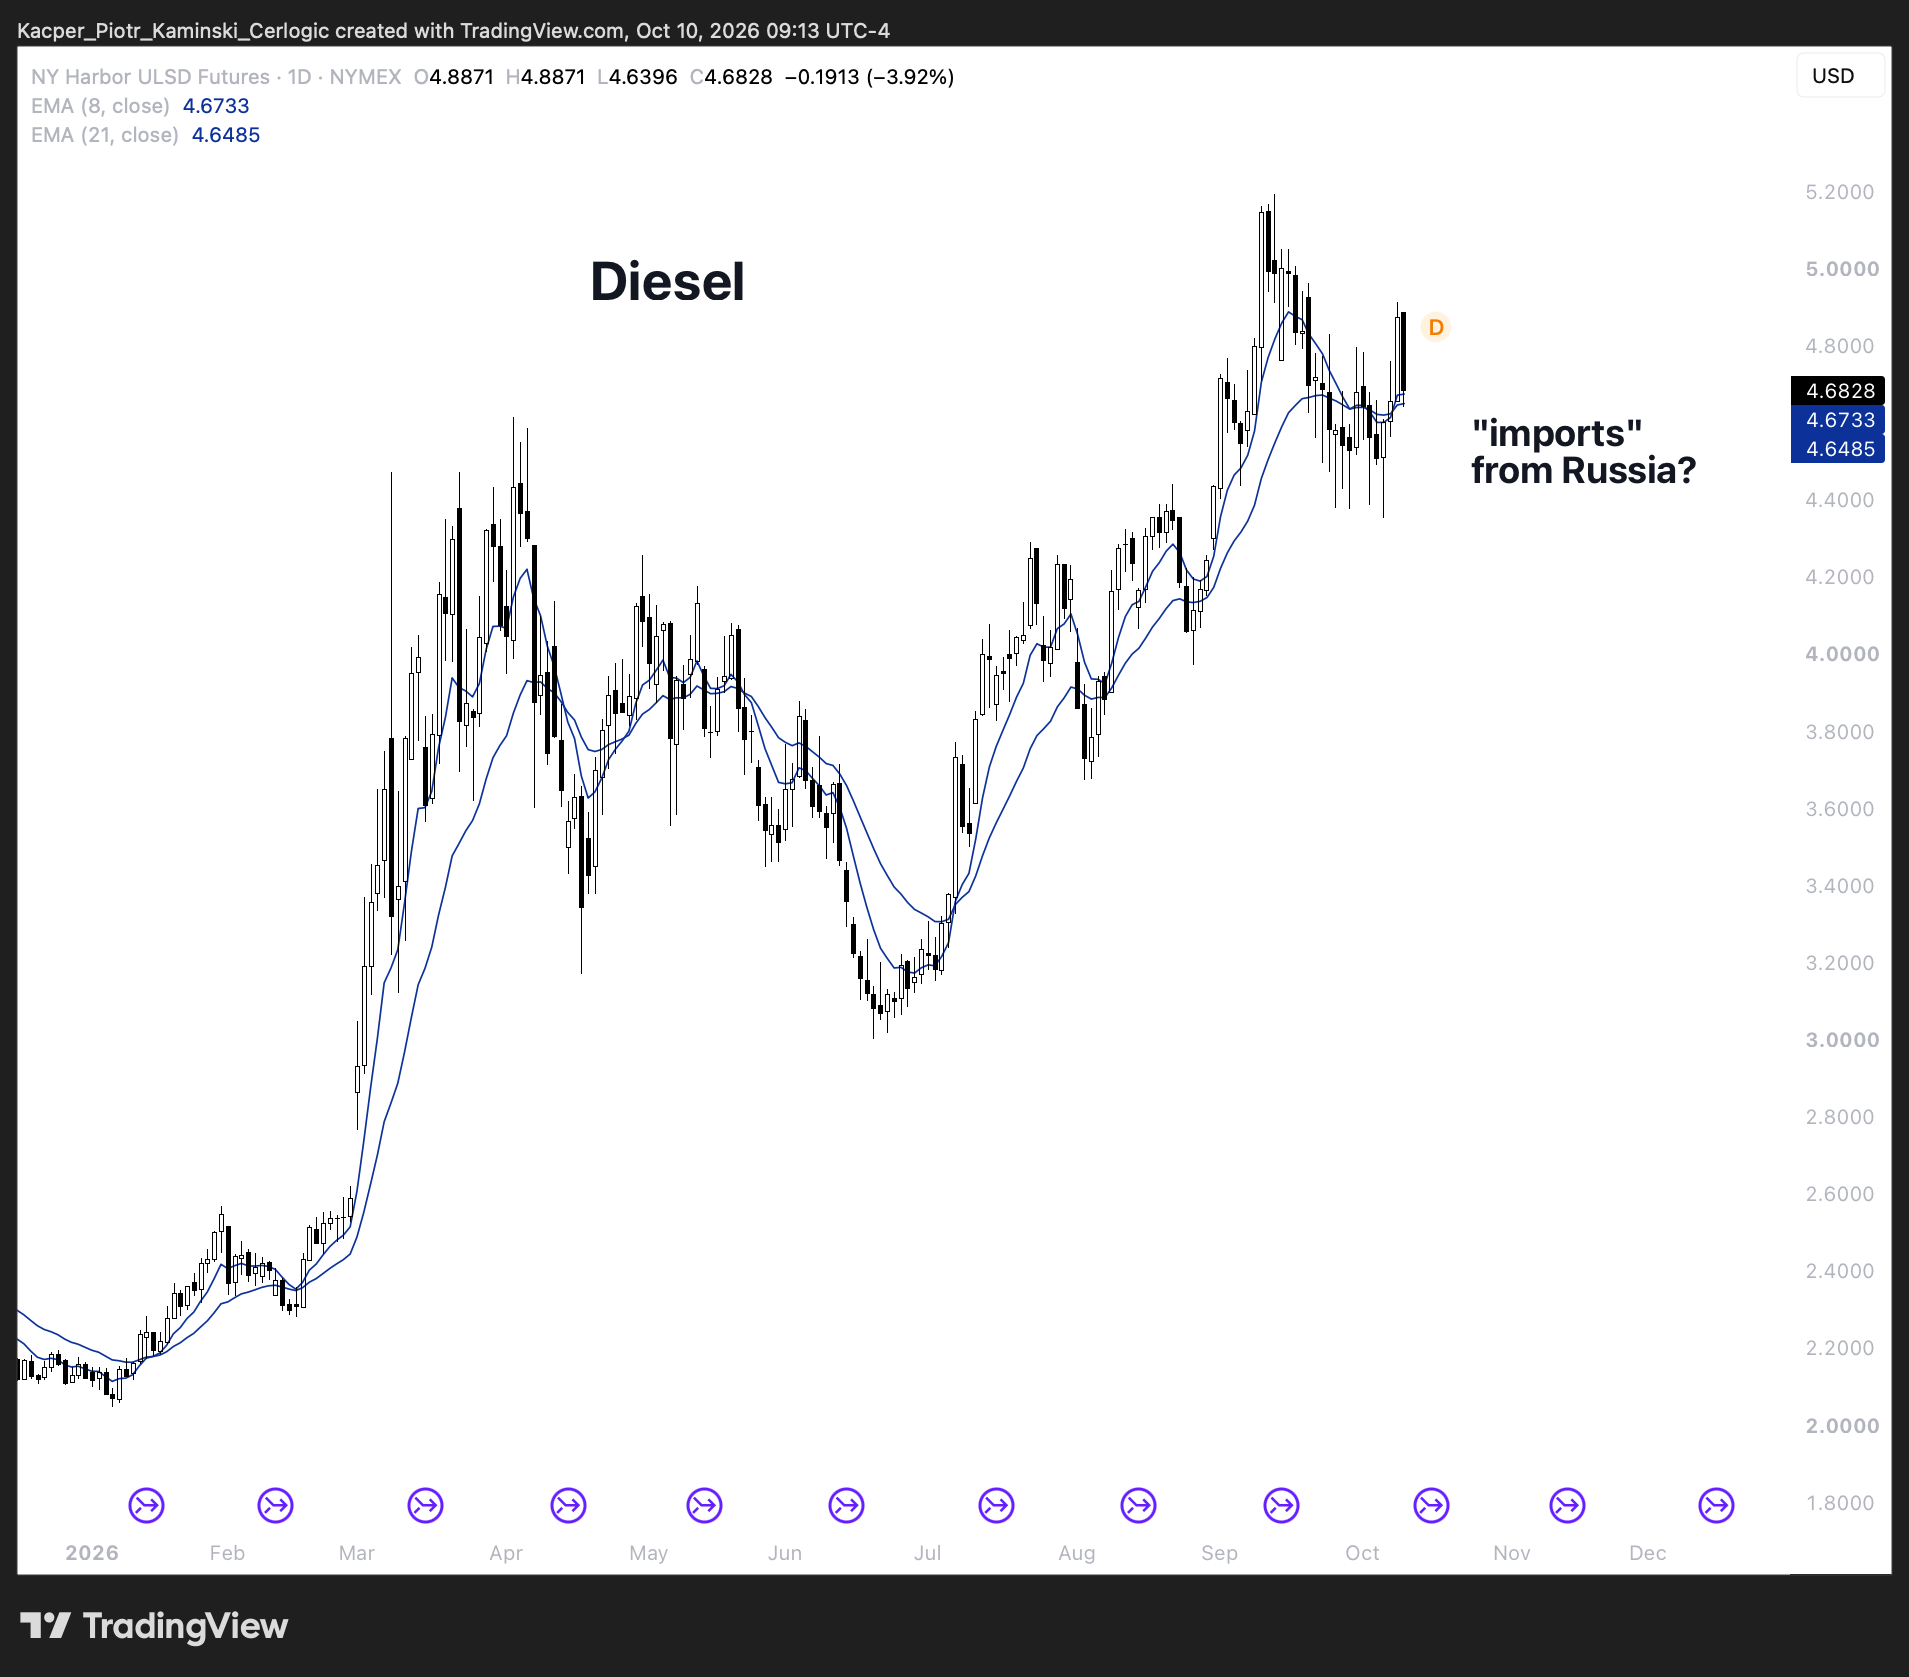
A lot is happening out there, all at once. We had the G7 release announcement, then the “imports from Russia”, a hurricane; meanwhile tankers and pipelines seem to go up in flames, almost every day.
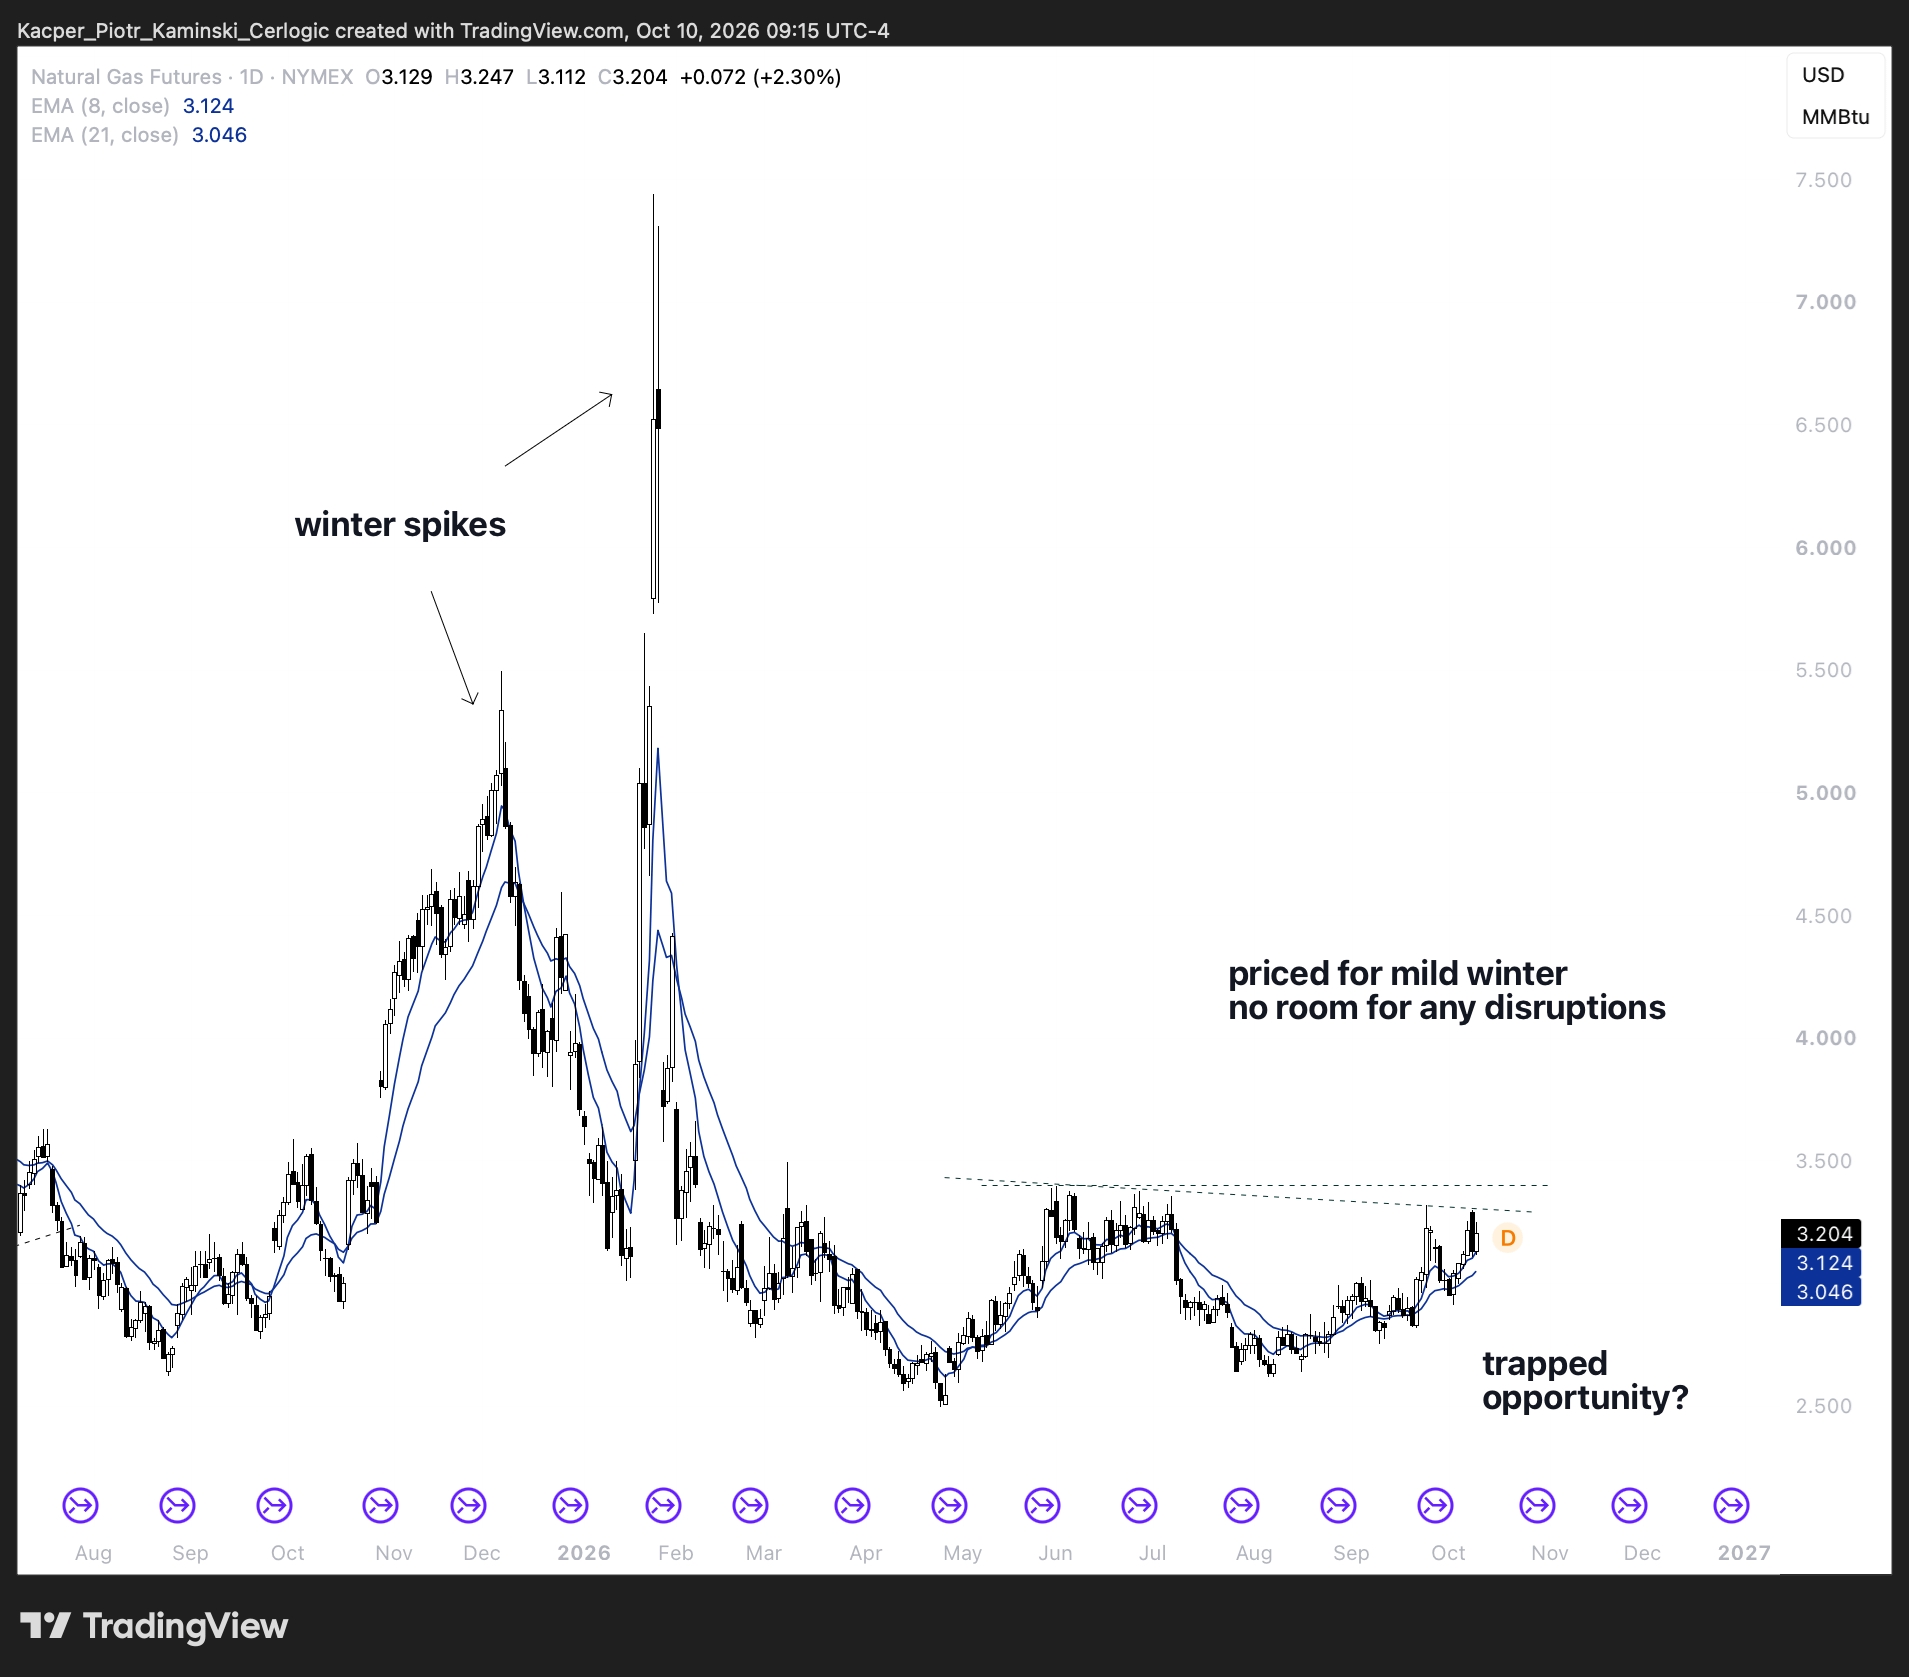
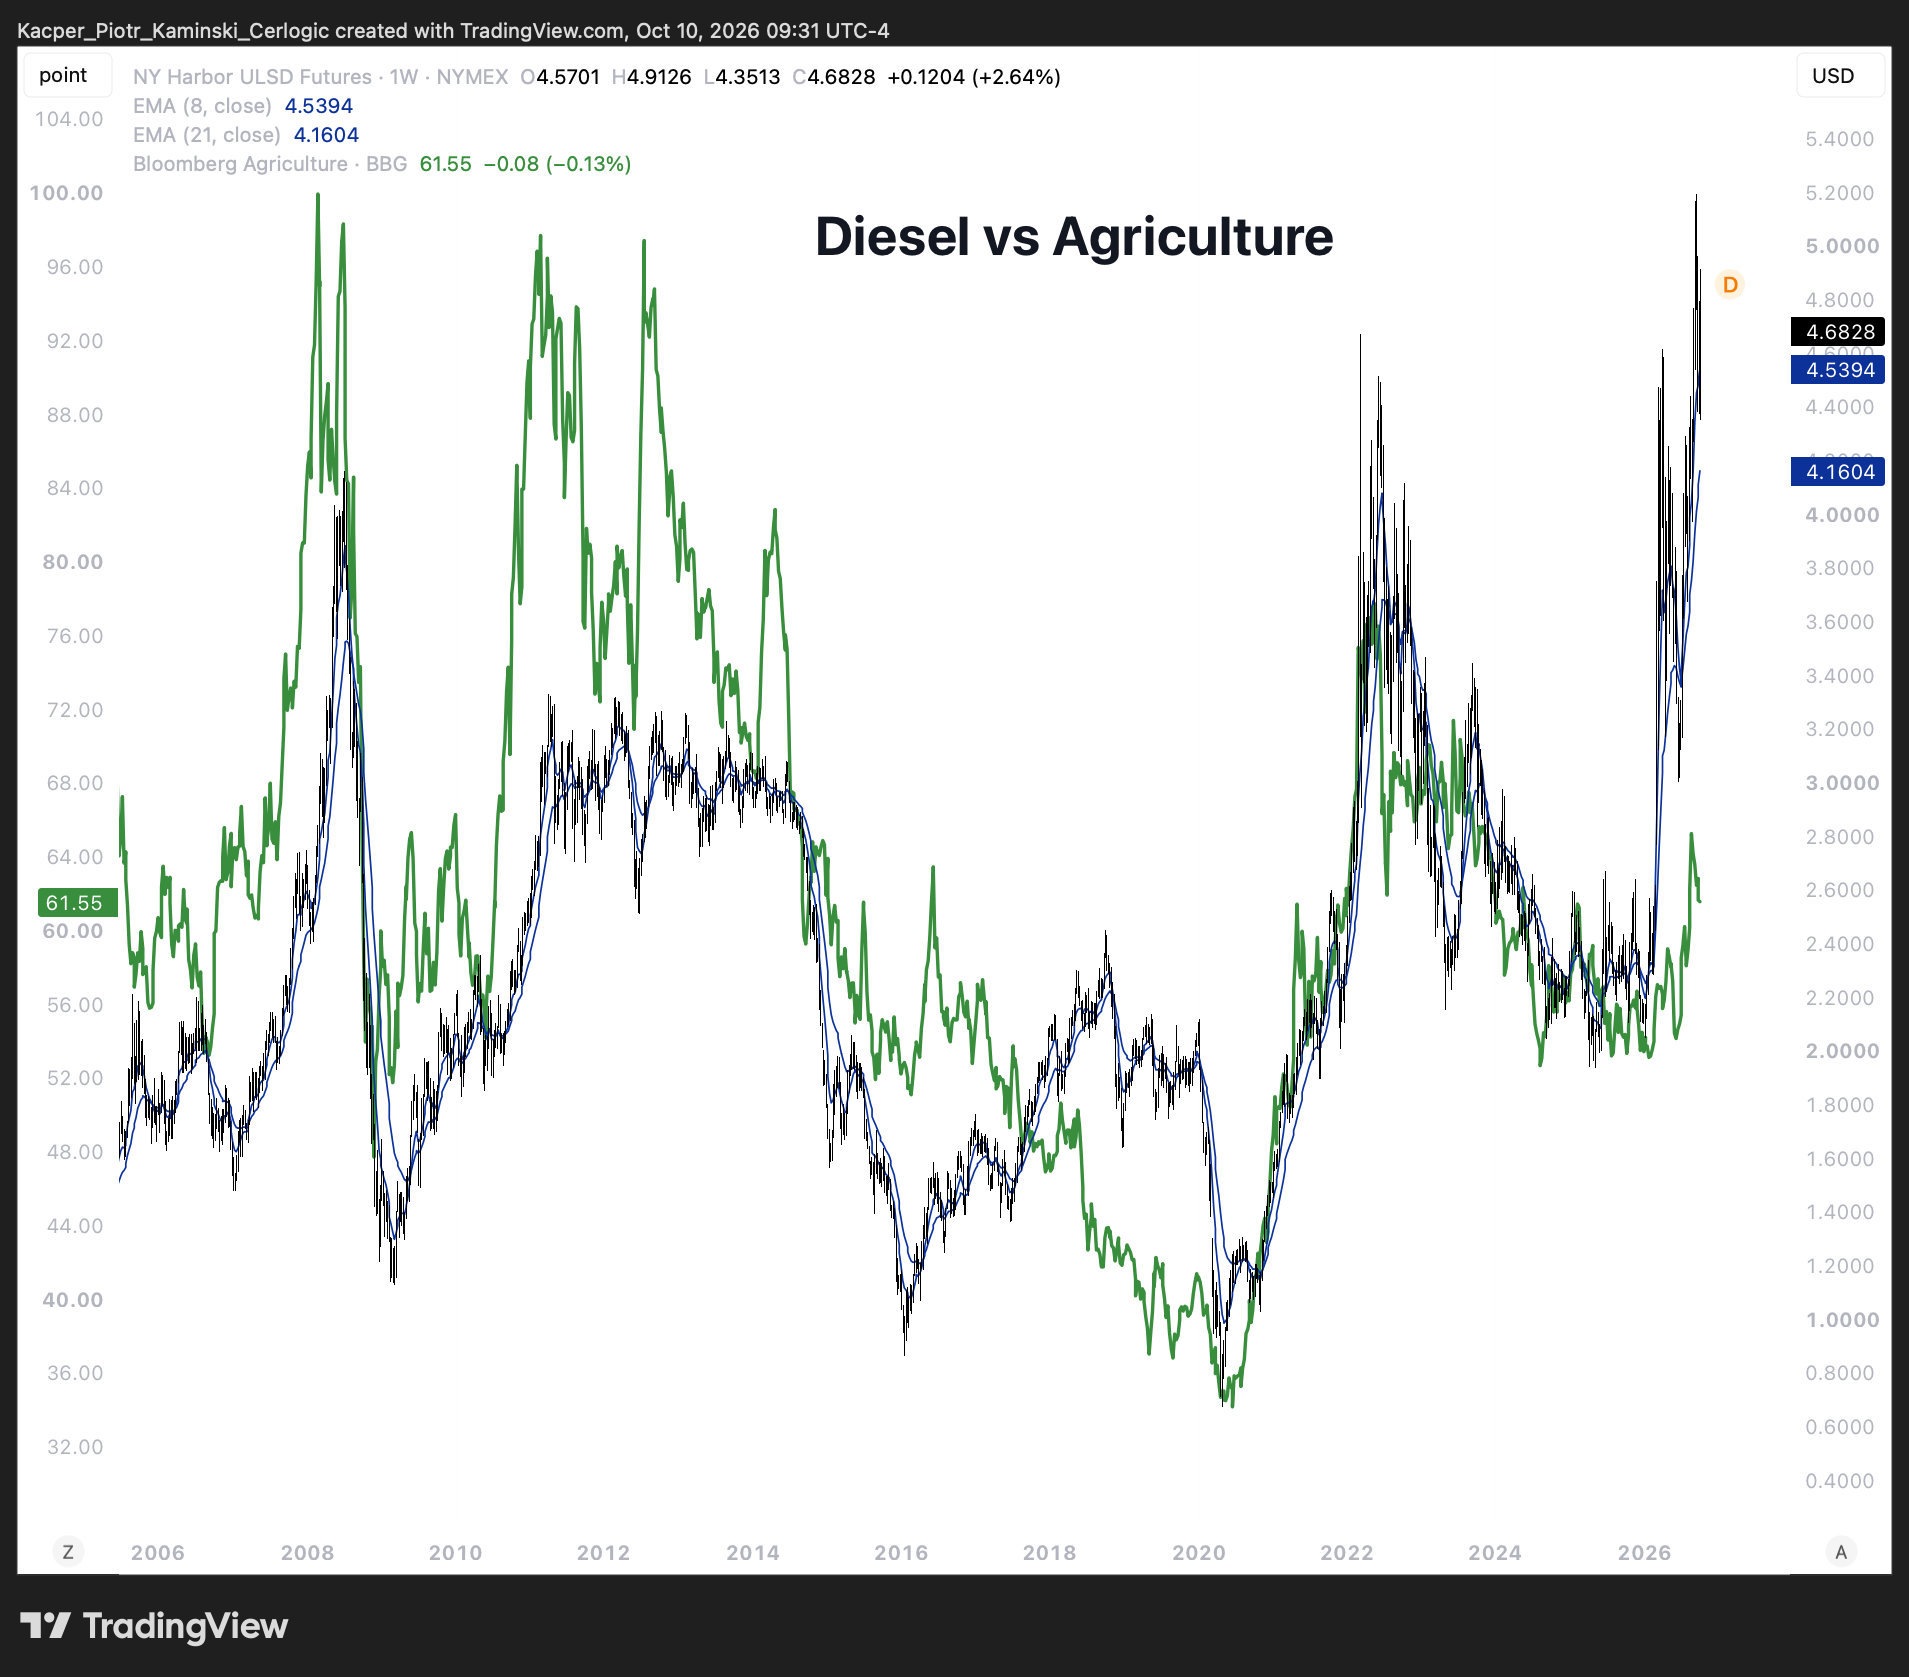
We cut the noise and go straight to the facts and the price. Despite demand destruction, particularly across the developing economies, the tightness still shows up where it matters, with diesel going back to an uptrend. Natural gas did the same, its positioning turning positive, with so many shorts to squeeze.
Short-term direction stays dependent on the political decisions, the Middle East, the Houthis and the Saudis, still Russia, and it doesn’t look like it’ll be over anytime soon. Nothing changes the facts though, the damage to production capacity and the depletion of reserves is done, and it’ll be with us for years, right into what would anyway be an underinvestment crisis, the one set to bite by the end of this decade.
The easy money has been made, but there are still plenty of opportunities here for patient traders and investors, upstream, midstream, downstream, services, you name it. In any case, our core long-term energy equity positions stay on, just hedged for the moment.
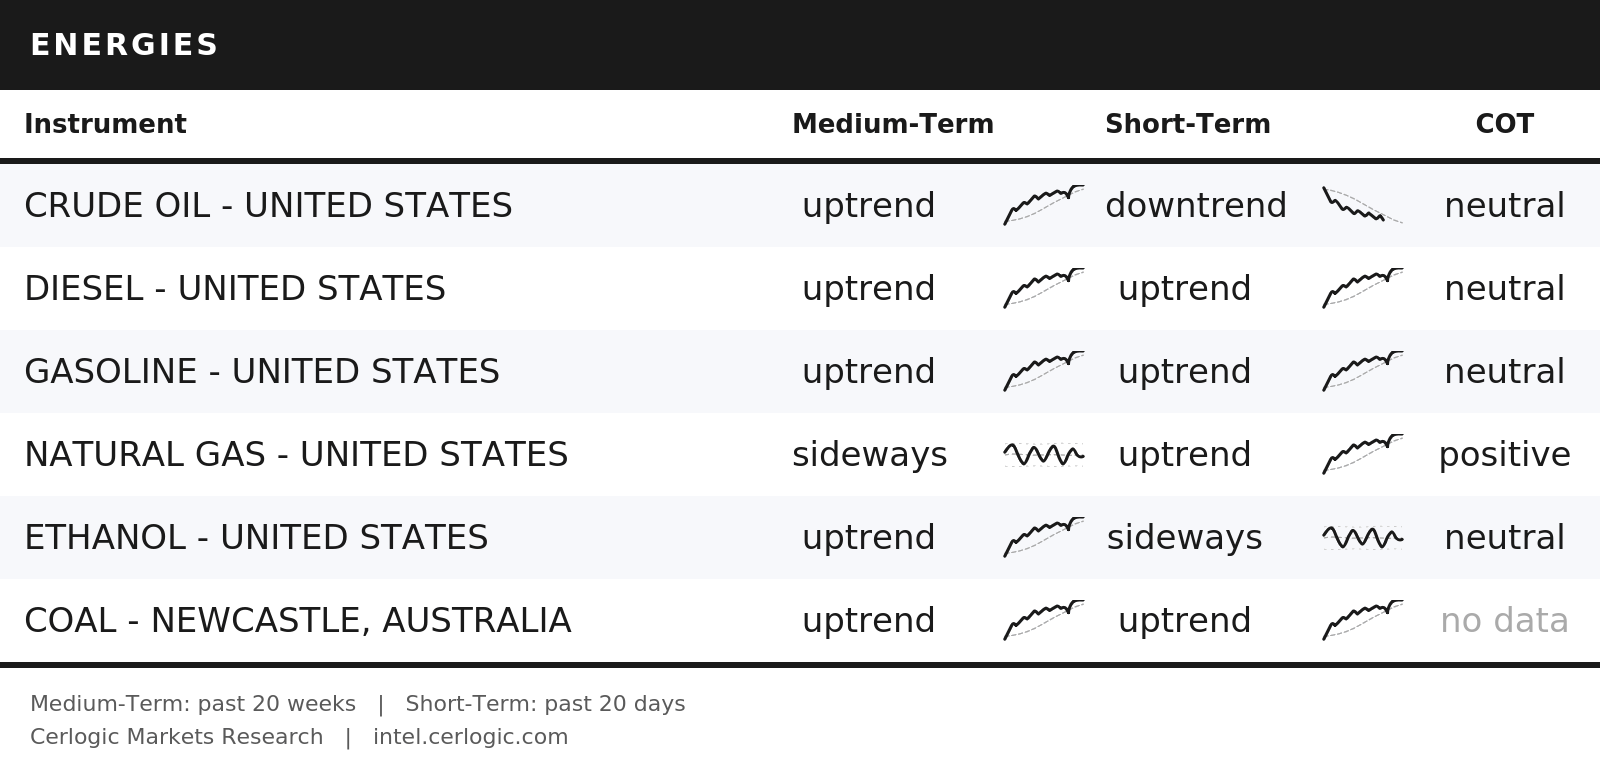
SHORT-TERM TREND CHANGES SINCE LAST WEEK
• CRUDE OIL – UNITED STATES: sideways ➝ downtrend
• DIESEL – UNITED STATES: sideways ➝ uptrend
• NATURAL GAS – UNITED STATES: sideways ➝ uptrend
• ETHANOL – UNITED STATES: uptrend ➝ sideways
MEDIUM-TERM TREND CHANGES SINCE LAST WEEK
• NONE
COT CHANGES SINCE LAST WEEK
• NATURAL GAS – UNITED STATES: neutral ➝ positive
CHARTS OF THE WEEK :
TREASURIES
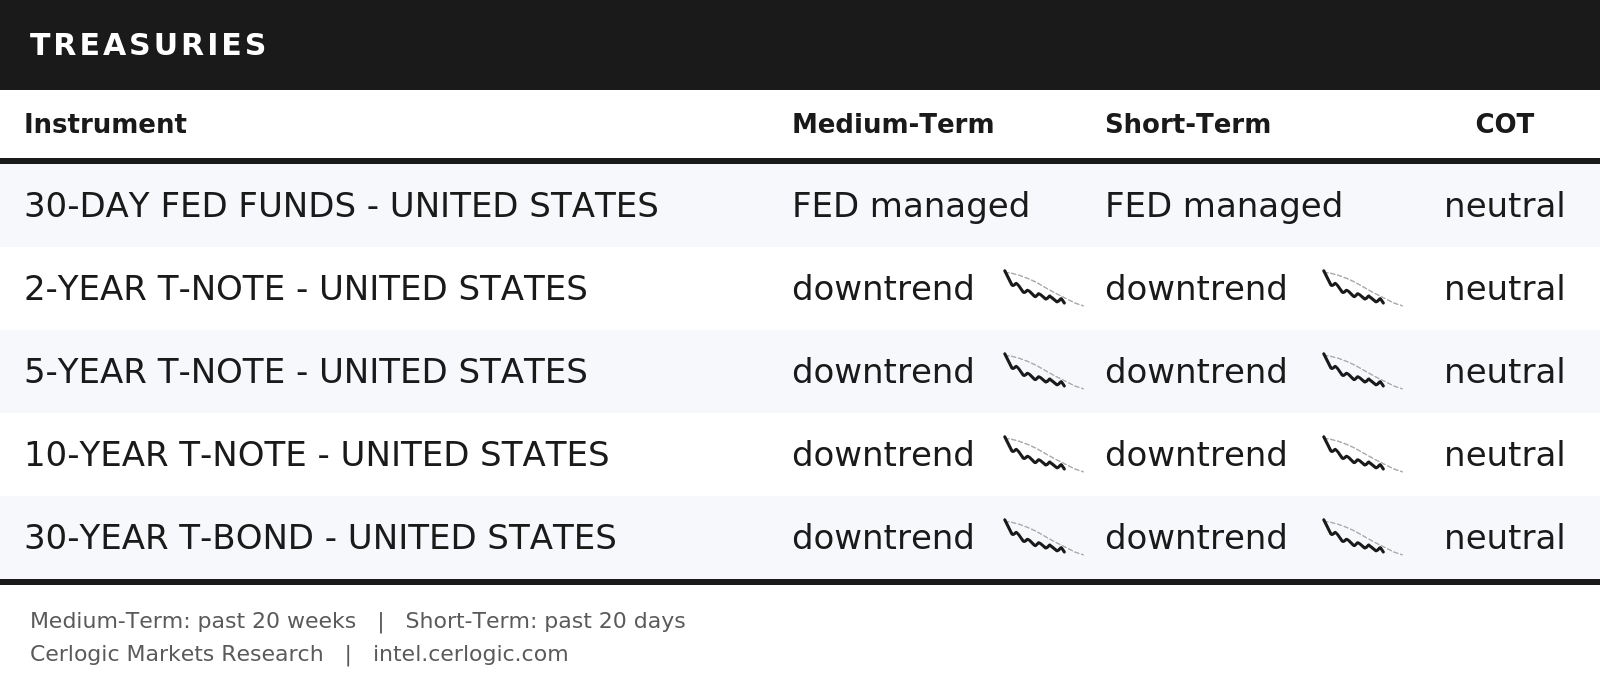
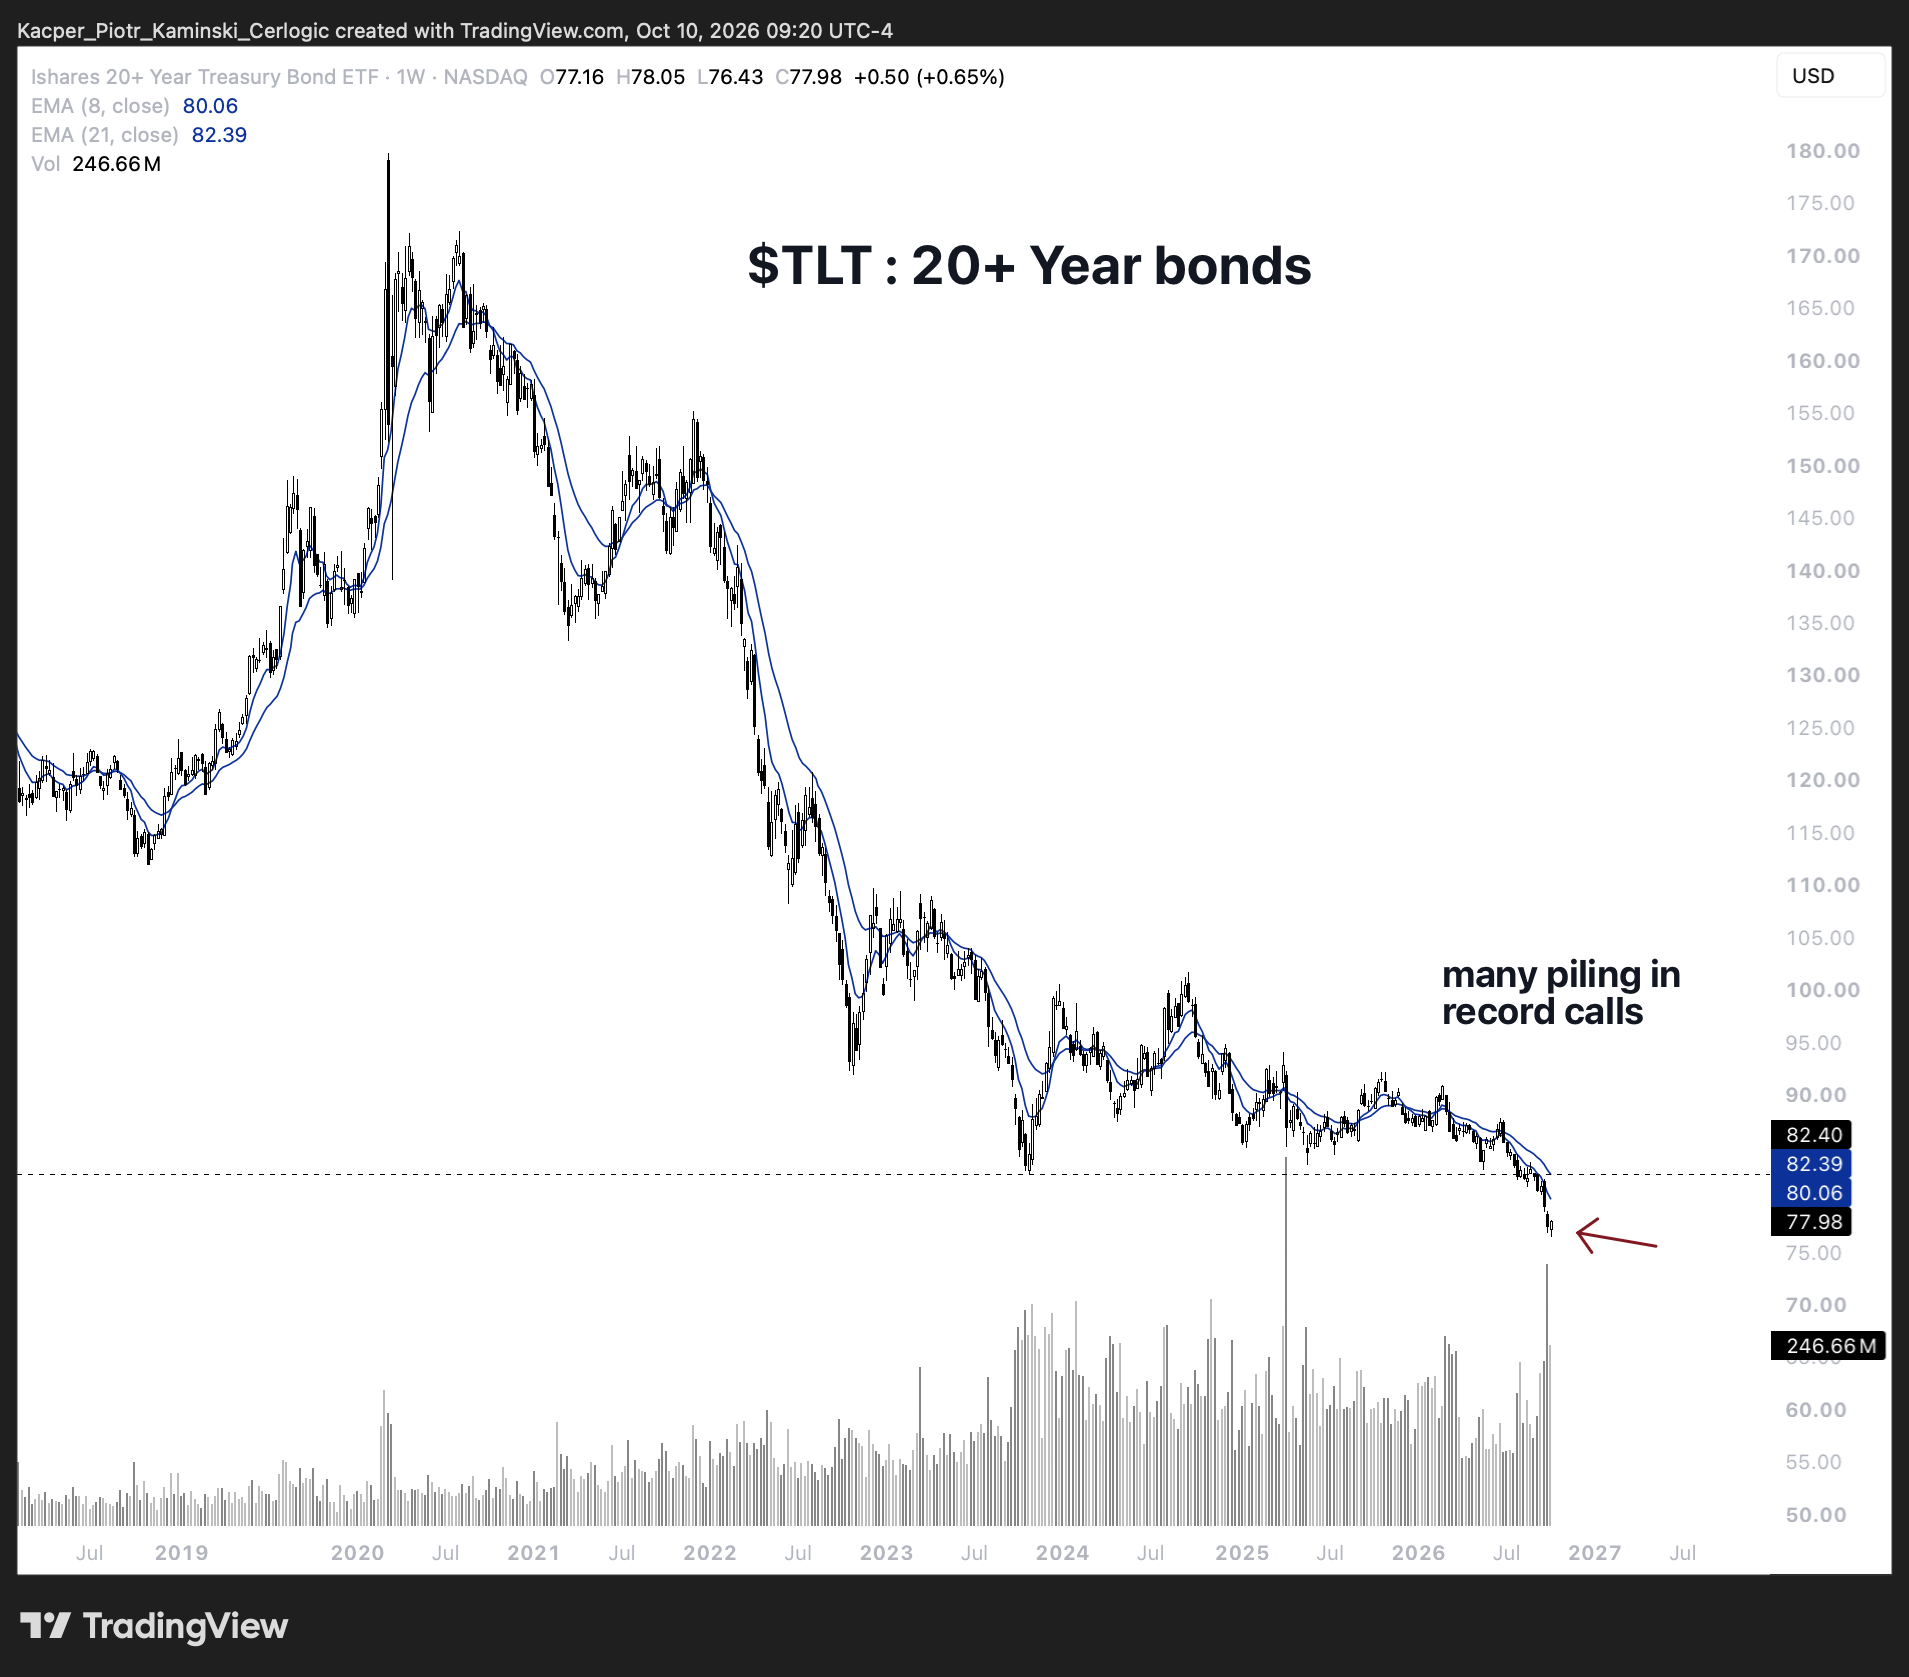
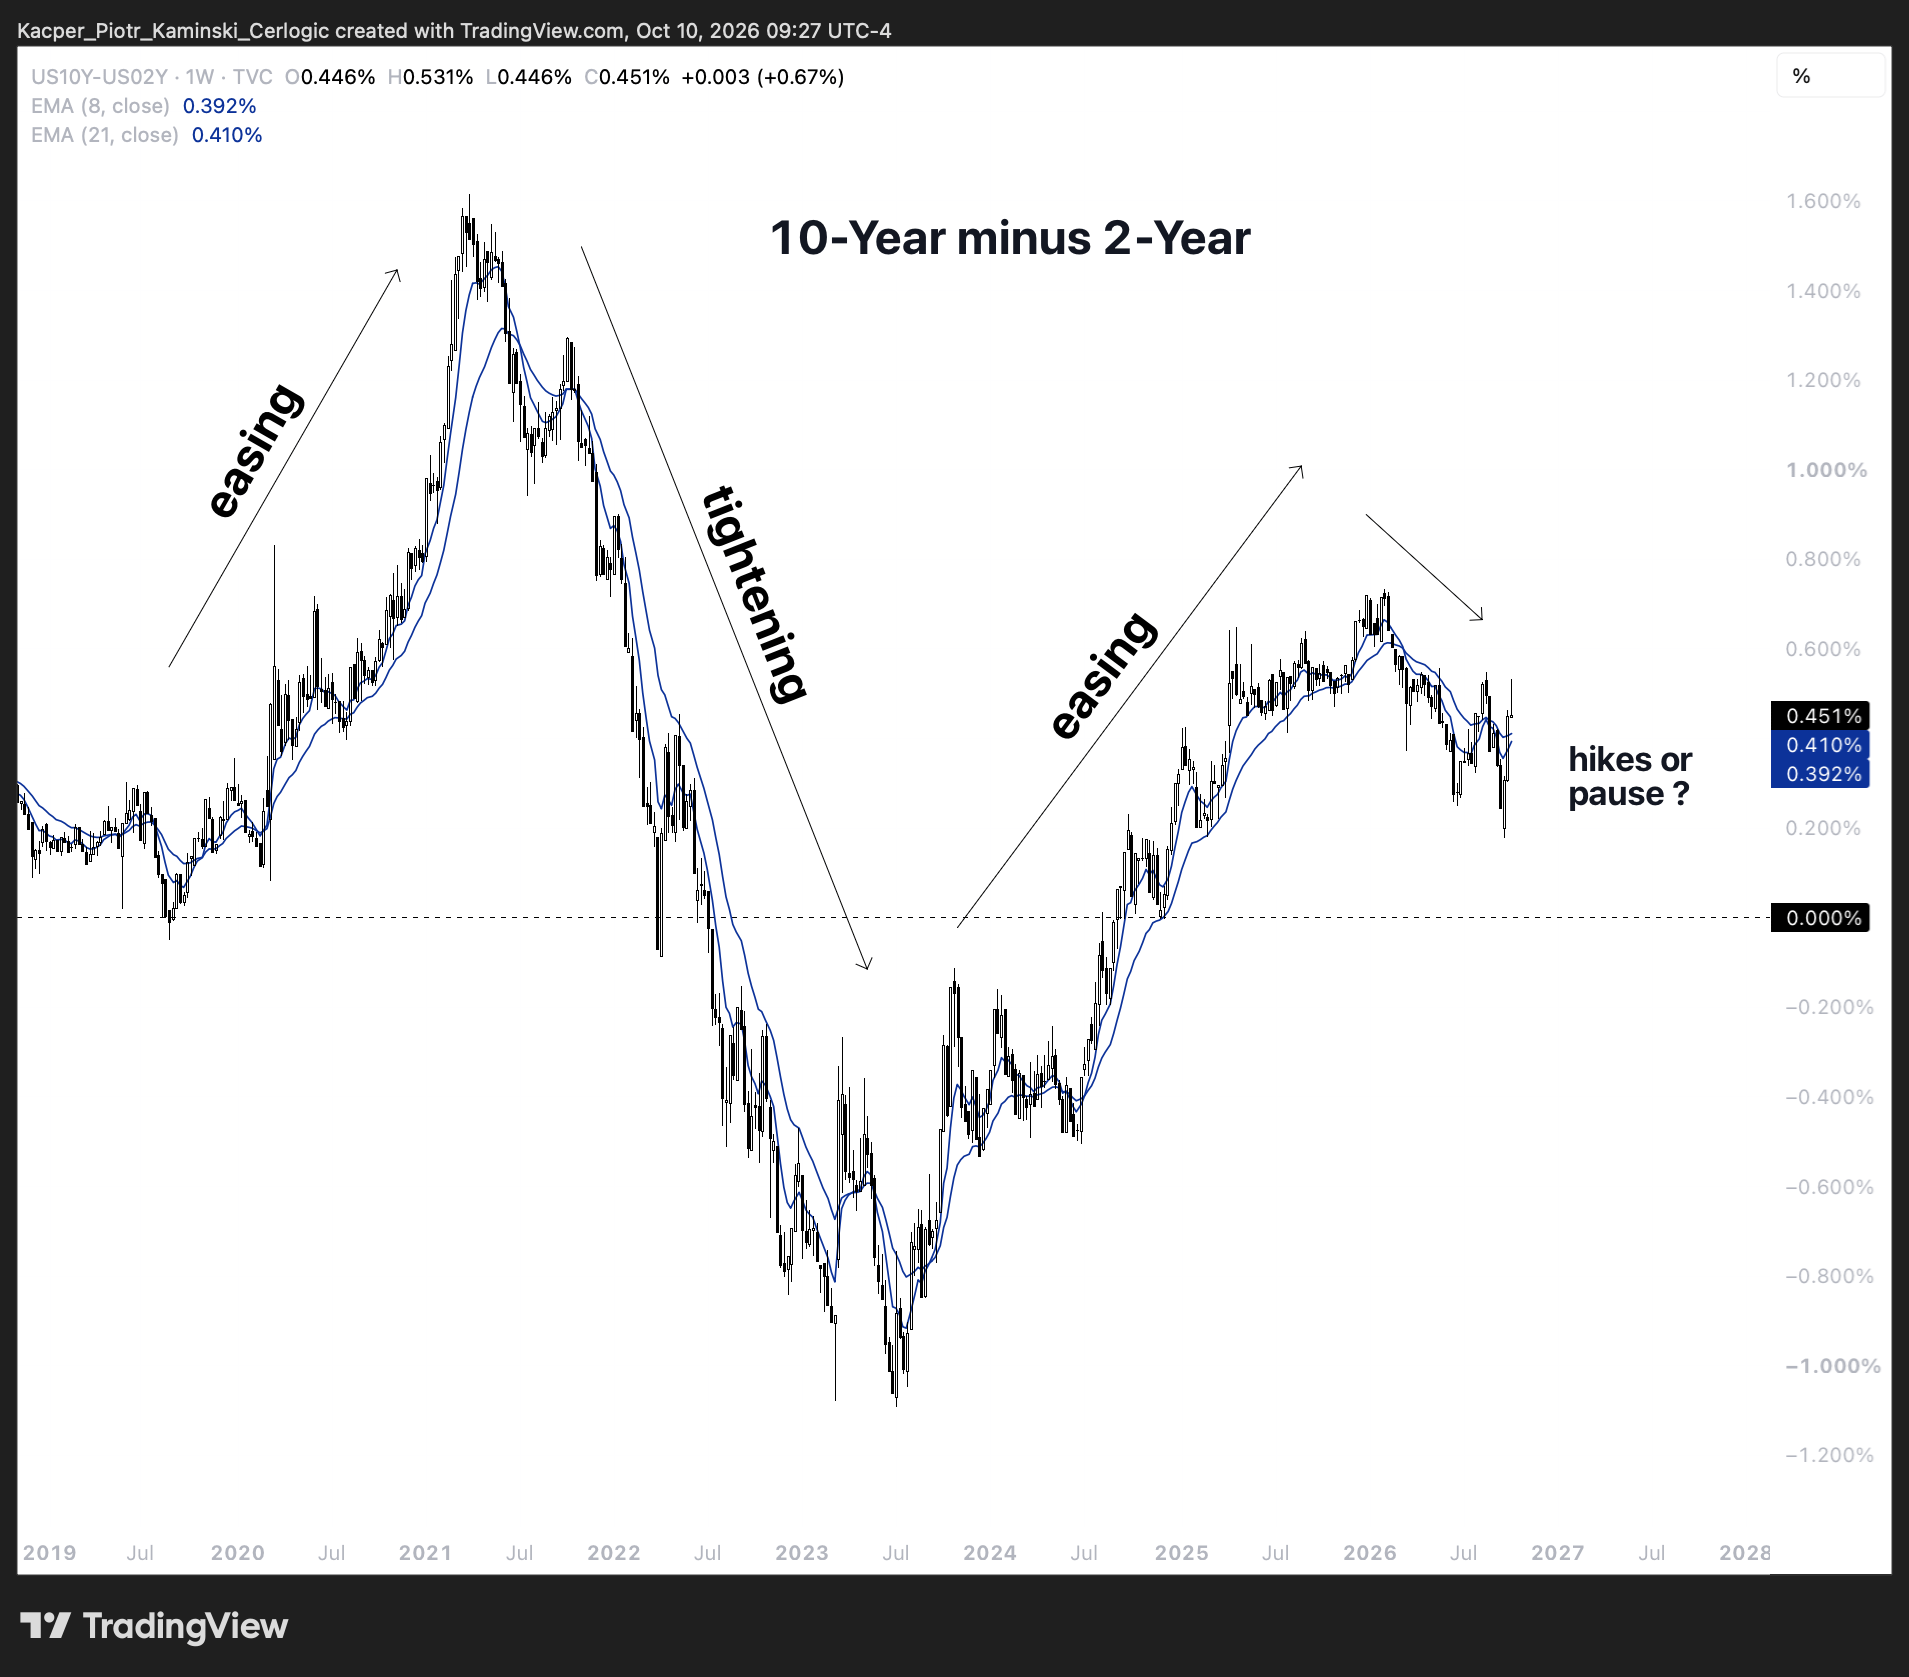
Beatings will continue until morale improves, so, did it? We saw first green week for $TLT in a while, let’s see, a solid bounce would not be surprising. Still, the whole curve still in a downtrend, nothing changed there.
The path stays clear as long as the energy crisis is unresolved. If they reach some kind of arrangement, we’ll likely see a pause, but it has to be real, and it has to hold, at least for a longer while. Short of that, oil and yields will find a way to cause a global slowdown on their own, and where exactly that breaking point is, we’ll see.
As to interventions, the bond markets are simply too large to be moved that easily, it may take trillions, like in 2020. Nothing structural has changed, more deficits, more issuance, more money supply. We still take no longs here.
SHORT-TERM TREND CHANGES SINCE LAST WEEK
• NONE
MEDIUM-TERM TREND CHANGES SINCE LAST WEEK
• NONE
COT CHANGES SINCE LAST WEEK
• NONE
CHARTS OF THE WEEK :
AGRICULTURE
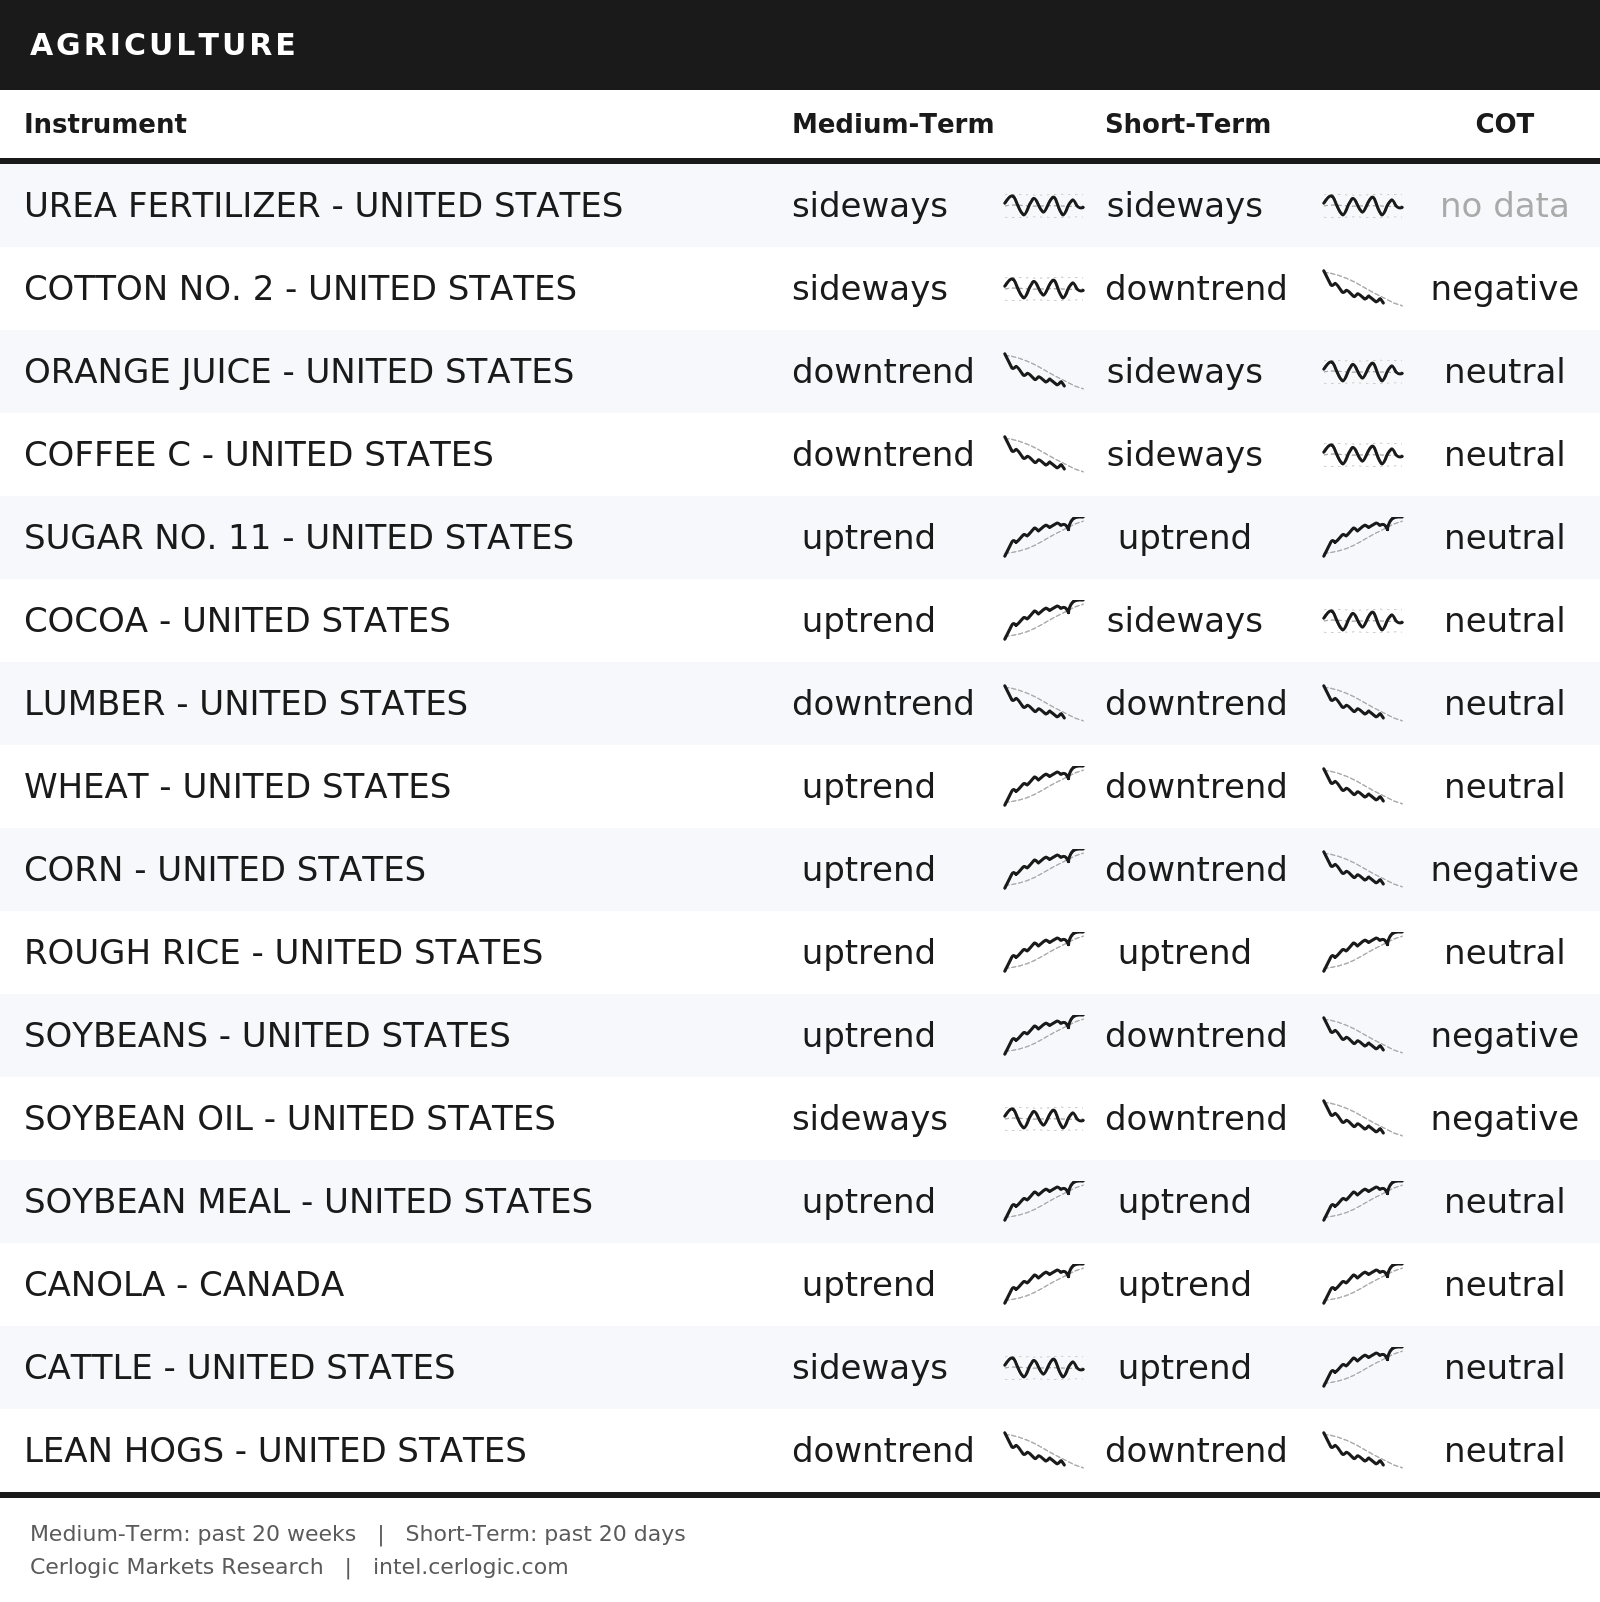
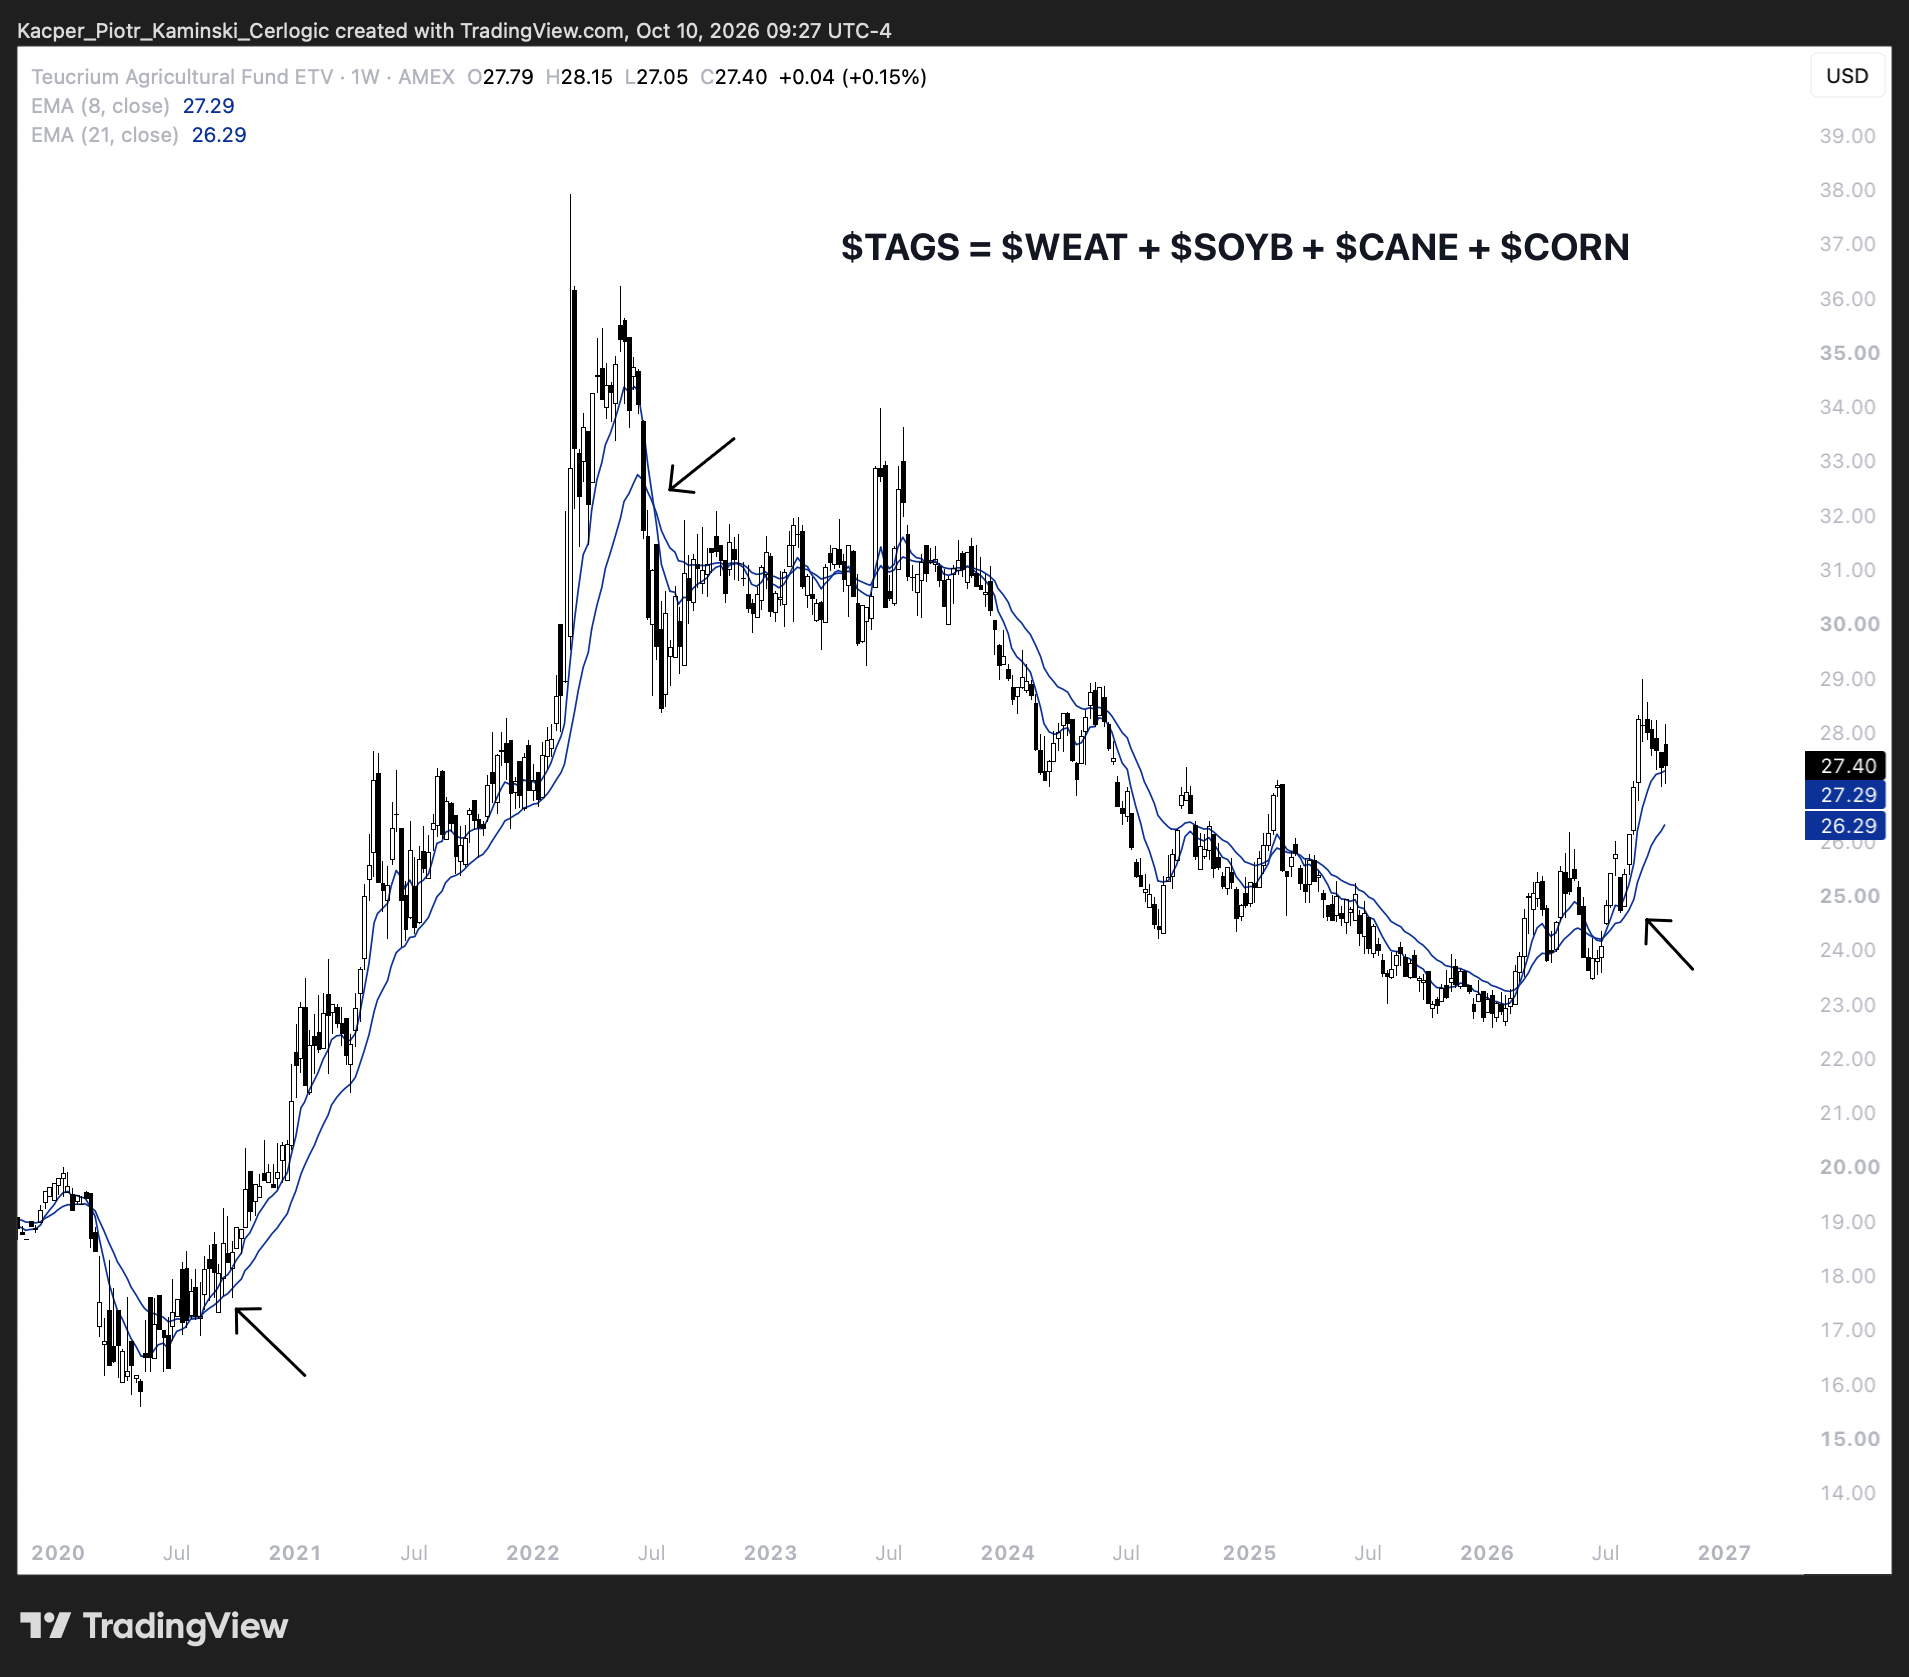
The ags are weaker, in the short-term for now. Same story as always in a bull market like this, sharp moves to new highs then violent pullbacks to higher lows, usually driven by headlines, it’s just how they behave.
We’re looking at several setups to trade long here, off weekly trends. Our core longs stay where they are. As always, two ways to play it this sector, swing the individual commodities short-term, or hold long-term and take the good with the bad of the bull run. Both depend on the trader’s psychology.
The bigger picture stays the same, and it points up. The fertilizer and energy damage is done, and El Niño is still out there. We stay long where the trends hold, and let the prices move as far as necessary to incentivize production. The crush spread setup we’ve got our eye on is still moving, way ahead of our 2027 base case, we won’t complain, it’s working.
And on fertilizer equities, they typically move well into an ags bull market. Farmers need the money to buy them, so they need to sell their production at high prices into the future. Right now they’re struggling, fuel prices through the roof, and it’s usually right here that governments step in, subsidies, tax breaks, that’s the tell, it’s where the fertilizer cycle begins.
SHORT-TERM TREND CHANGES SINCE LAST WEEK
• UREA FERTILIZER – UNITED STATES: uptrend ➝ sideways
• COCOA – UNITED STATES: downtrend ➝ sideways
• SOYBEANS – UNITED STATES: sideways ➝ downtrend
• SOYBEAN MEAL – UNITED STATES: sideways ➝ uptrend
• CANOLA – CANADA: sideways ➝ uptrend
MEDIUM-TERM TREND CHANGES SINCE LAST WEEK
• CATTLE – UNITED STATES: downtrend ➝ sideways
COT CHANGES SINCE LAST WEEK
• SOYBEANS – UNITED STATES: neutral ➝ negative
CHARTS OF THE WEEK :
That’s it for now. Stay safe out there!
Kacper Piotr Kaminski, Cerlogic Markets Research – intel.cerlogic.com
This publication is for informational and educational purposes only and does not constitute investment advice. Markets involve risk, and every participant is responsible for their own decisions.